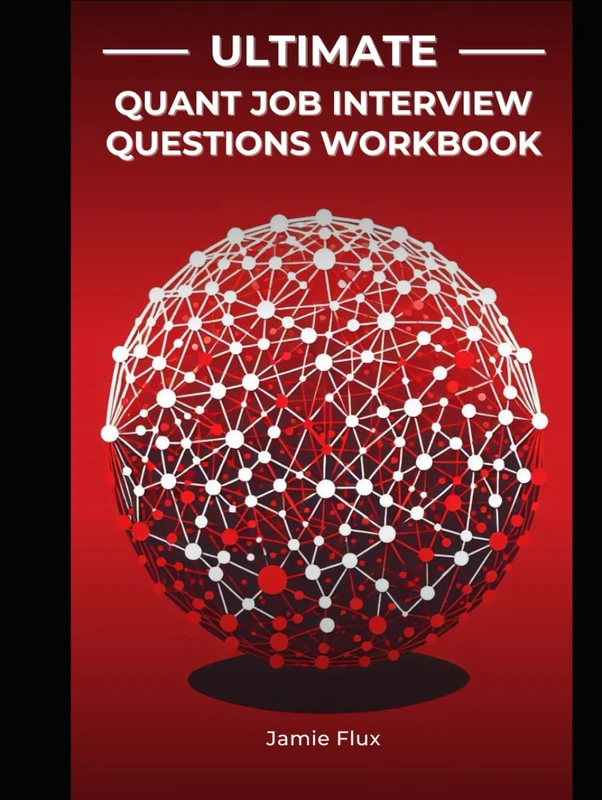
Out of stock

This item is currently unavailable

Gone for 126 days. Could come back at any time — we're watching for you.

Out of stock 126 days · last price £53

Ultimate Quant Job Interview Questions Workbook: Brief Crash Courses and Real Interview Questions taking you from Beginner to Wall Street Offers (The ... Quantitative Trading Strategies with Python)

Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 616 days · 616 data points (no recent data)

Historical
Generating forecast…
£53.15 £50.49 £51.56 £52.62 £53.68 £54.74 £55.81 23 October 2024 25 March 2025 26 August 2025 27 January 2026 30 June 2026
View at Amazon ↗
Out of stock

Price data last checked 115 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 616 days • 1 price levels

Days at Price
616 days 0 154 308 462 616 £53 Days at Price

Price Analysis

Most common price: £53 (616 days, 100.0%)

Price range: £53 - £53

Price levels: 1 different prices over 616 days

Description

Discover the ultimate resource for mastering quantitative finance and acing your interviews with this comprehensive workbook designed to take you from beginner to Wall Street offers. Tailored for aspiring quants and seasoned financial professionals alike, this guide dives deep into the concepts, models, and techniques critical to succeeding in the competitive world of quantitative finance. Key Features: - Comprehensive coverage of essential quant finance topics. - Practical insights with real interview questions for job success. - Step-by-step crash courses designed to enhance understanding. - A balance of theoretical principles and practical applications. What You Will Learn: - Master the derivation and application of the Black-Scholes equation. - Understand Monte Carlo methods for pricing and risk management. - Explore Brownian motion and its implications for stock price modeling. - Learn the intricacies of Itô’s Lemma in financial modeling. - Solve stochastic differential equations in market modeling scenarios. - Apply GARCH models for forecasting volatility. - Analyze the CAPM model and its practical limitations. - Calculate and interpret Value at Risk for risk exposure. - Model interest rates with the Cox-Ingersoll-Ross framework. - Explore mean-reverting processes with the Ornstein-Uhlenbeck model. - Delve into the Hull-White model for interest rate curve movements. - Utilize partial differential equations like the Heat Equation in pricing. - Incorporate Lévy processes for modeling market jumps. - Execute stochastic volatility pricing with the Heston model. - Estimate variables using Kalman Filters from noisy data. - Leverage ARIMA models for robust time series forecasting. - Integrate machine learning into quantitative strategies. - Employ neural networks to predict market trends effectively. - Implement Support Vector Machines for financial classification. - Harness copulas for joint distribution simulation of assets. - Reduce dimensionality with Principal Component Analysis. - Use factor models for asset pricing and portfolio construction. - Explore the binomial model for option pricing insights. - Understand martingale theory applications in derivatives. - Advance your knowledge of risk-neutral valuation methods. - Apply quantitative methods to fixed-income securities. - Construct and evaluate yield curves in bond markets. - Develop models for pricing and managing credit risk. - Value interest rate derivatives with cutting-edge methodologies. - Compute Monte Carlo Greeks for derivative sensitivities. - Solve PDEs with finite difference methods for option pricing. - Adjust to market shifts using regime-switching models. - Optimize asset allocation through advanced portfolio techniques. - Explore quantitative hedge fund strategies for risk management.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
18 September 2024
Listed Since
19 September 2024

Barcode

No barcode data available

Similar Products You Might Like
Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)
98% match

Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)

Wiley
£45.99 11 Aug 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
98% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
98% match

Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation

MACMILLAN
£52.36 11 Sep 2026
Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)
98% match

Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)

Wiley
£63.98 19 Aug 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
98% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
98% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Option Valuation under Stochastic Volatility II: With Mathematica Code
97% match

Option Valuation under Stochastic Volatility II: With Mathematica Code

Finance Press
£78.48 06 Oct 2026
Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models
97% match

Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models

Wiley
£160.65 15 Aug 2026
MODELING AND PRICING OF SWAPS FOR FINANCIAL AND ENERGY MARKETS WITH STOCHASTIC VOLATILITIES
97% match

MODELING AND PRICING OF SWAPS FOR FINANCIAL AND ENERGY MARKETS WITH STOCHASTIC VOLATILITIES

World Scientific Publishing Company
£64.46 10 Sep 2026
Mathematical Methods for Finance: Tools for Asset and Risk Management: 207 (Frank J. Fabozzi Series)
97% match

Mathematical Methods for Finance: Tools for Asset and Risk Management: 207 (Frank J. Fabozzi Series)

Wiley
£93.39 06 Oct 2026
CRC Press Quantitative Finance C++ Object-Oriented Approach
97% match

CRC Press Quantitative Finance C++ Object-Oriented Approach

CRC Press
£75.00 28 Aug 2026
Equity Derivatives and Hybrids: Markets, Models and Methods (Applied Quantitative Finance)
97% match

Equity Derivatives and Hybrids: Markets, Models and Methods (Applied Quantitative Finance)

MACMILLAN
£67.87 21 Aug 2026
Chapman and Hall/CRC Malliavin Calculus in Finance Textbook
97% match

Chapman and Hall/CRC Malliavin Calculus in Finance Textbook

Chapman and Hall/CRC
£104.00 15 Aug 2026
Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)
97% match

Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)

Springer
£82.06 24 Sep 2026
Wiley Paul Wilmott on Quantitative Finance 2nd Edition
97% match

Wiley Paul Wilmott on Quantitative Finance 2nd Edition

Wiley
£160.98 21 Oct 2026
An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)
97% match

An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.82 20 Aug 2026
Empirical Dynamic Asset Pricing: Model Specification and Econometric Assessment
97% match

Empirical Dynamic Asset Pricing: Model Specification and Econometric Assessment

Princeton University Press
£69.91 14 Aug 2026
Quantitative Finance: An Introduction to Investments, Asset Pricing, and Derivatives
97% match

Quantitative Finance: An Introduction to Investments, Asset Pricing, and Derivatives

Princeton University Press
£49.38 22 Oct 2026
Springer Martingale Methods in Financial Modelling - 2nd Ed
97% match

Springer Martingale Methods in Financial Modelling - 2nd Ed

Springer
£96.99 21 Aug 2026
Computation and Simulation for Finance: An Introduction with Python (Springer Undergraduate Texts in Mathematics and Technology)
97% match

Computation and Simulation for Finance: An Introduction with Python (Springer Undergraduate Texts in Mathematics and Technology)

Springer
£46.51 11 Aug 2026
Options, futures et autres actifs dérivés : manuel - 11e édition
97% match

Options, futures et autres actifs dérivés : manuel - 11e édition

PEARSON EDUCATION
£49.93 26 Aug 2026
Advanced Asset Pricing Theory: 2 (SERIES IN QUANTITATIVE FINANCE)
97% match

Advanced Asset Pricing Theory: 2 (SERIES IN QUANTITATIVE FINANCE)

Imperial College Press
£82.96 02 Oct 2026
World Scientific Quantitative Analysis and Derivatives Modeling
97% match

World Scientific Quantitative Analysis and Derivatives Modeling

World Scientific Publishing Company
£82.86 02 Oct 2026
Implementing Models in Quantitative Finance: Methods and Cases (Springer Finance)
97% match

Implementing Models in Quantitative Finance: Methods and Cases (Springer Finance)

Springer

£57.69 02 Oct 2026