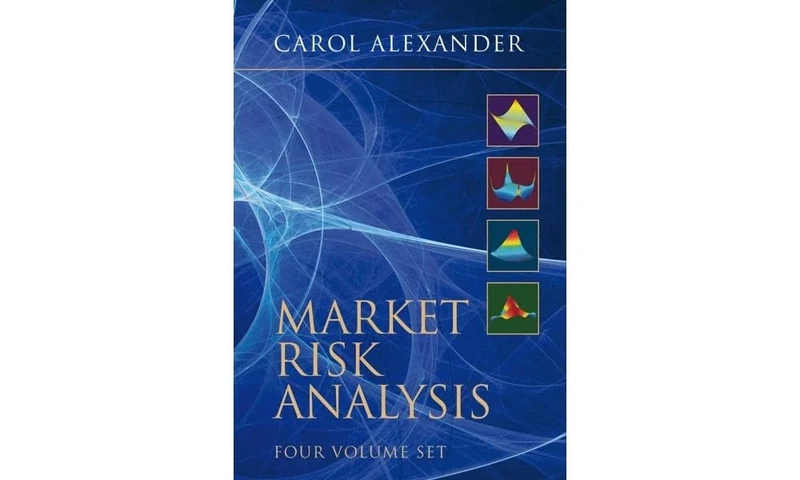
£160.65

It has never been this cheap. We have no record of a lower price.

£161 today · cheaper than every other day in the last 3 months

Wiley Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 22 days · 22 data points (no recent data)

Historical
Generating forecast…
£160.65 £152.62 £155.83 £159.04 £162.26 £165.47 £168.68 25 July 2026 30 July 2026 04 August 2026 09 August 2026 15 August 2026
View at Amazon ↗

Price data last checked 69 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 22 days • 1 price levels

Days at Price
22 days 0 6 11 17 22 £161 Days at Price

Price Analysis

Most common price: £161 (22 days, 100.0%)

Price range: £161 - £161

Price levels: 1 different prices over 22 days

Description

Market Risk Analysis is the most comprehensive, rigorous and detailed resource available on market risk analysis. Written as a series of four interlinked volumes each title is self-contained, although numerous cross-references to other volumes enable readers to obtain further background knowledge and information about financial applications. Volume I: Quantitative Methods in Finance covers the essential mathematical and financial background for subsequent volumes. Although many readers will already be familiar with this material, few competing texts contain such a complete and pedagogical exposition of all the basic quantitative concepts required for market risk analysis. There are six comprehensive chapters covering all the calculus, linear algebra, probability and statistics, numerical methods and portfolio mathematics that are necessary for market risk analysis. This is an ideal background text for a Masters course in finance. Volume II: Practical Financial Econometrics provides a detailed understanding of financial econometrics, with applications to asset pricing and fund management as well as to market risk analysis. It covers equity factor models, including a detailed analysis of the Barra model and tracking error, principal component analysis, volatility and correlation, GARCH, cointegration, copulas, Markov switching, quantile regression, discrete choice models, non-linear regression, forecasting and model evaluation. Volume III: Pricing, Hedging and Trading Financial Instruments has five very long chapters on the pricing, hedging and trading of bonds and swaps, futures and forwards, options and volatility as well detailed descriptions of mapping portfolios of these financial instruments to their risk factors. There are numerous examples, all coded in interactive Excel spreadsheets, including many pricing formulae for exotic options but excluding the calibration of stochastic volatility models, for which Matlab code is provided. The chapters on options and volatility together constitute 50% of the book, the slightly longer chapter on volatility concentrating on the dynamic properties the two volatility surfaces the implied and the local volatility surfaces that accompany an option pricing model, with particular reference to hedging. Volume IV: Value at Risk Models builds on the three previous volumes to provide by far the most comprehensive and detailed treatment of market VaR models that is currently available in any textbook. The exposition starts at an elementary level but, as in all the other volumes, the pedagogical approach accompanied by numerous interactive Excel spreadsheets allows readers to experience the application of parametric linear, historical simulation and Monte Carlo VaR models to increasingly complex portfolios. Starting with simple positions, after a few chapters we apply value-at-risk models to interest rate sensitive portfolios, large international securities portfolios, commodity futures, path dependent options and much else. This rigorous treatment includes many new results and applications to regulatory and economic capital allocation, measurement of VaR model risk and stress testing.

Product Specifications

Brand
Wiley
Format
hardcover
Domain
Amazon UK
Release Date
23 January 2009
Listed Since
26 September 2007

Barcode

No barcode data available

Similar Products You Might Like
Wiley Value at Risk Models - Market Risk Analysis Book
98% match

Wiley Value at Risk Models - Market Risk Analysis Book

Wiley
£66.79 11 Aug 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
98% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)
98% match

Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)

Wiley
£63.98 19 Aug 2026
Wiley Machine Learning for Risk Calculations Book
98% match

Wiley Machine Learning for Risk Calculations Book

Wiley
£56.59 21 Oct 2026
Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)
98% match

Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)

Wiley
£45.99 11 Aug 2026
Ultimate Quant Job Interview Questions Workbook: Brief Crash Courses and Real Interview Questions taking you from Beginner to Wall Street Offers (The ... Quantitative Trading Strategies with Python)
97% match

Ultimate Quant Job Interview Questions Workbook: Brief Crash Courses and Real Interview Questions taking you from Beginner to Wall Street Offers (The ... Quantitative Trading Strategies with Python)

Price unavailable
Numerical Methods for Finance (Chapman & Hall/CRC Financial Mathematics)
97% match

Numerical Methods for Finance (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£66.87 01 Oct 2026
Market Risk Analysis, Practical Financial Econometrics (The Wiley Finance Series)
97% match

Market Risk Analysis, Practical Financial Econometrics (The Wiley Finance Series)

Wiley
£53.68 21 Oct 2026
World Scientific Quantitative Analysis and Derivatives Modeling
97% match

World Scientific Quantitative Analysis and Derivatives Modeling

World Scientific Publishing Company
£82.86 02 Oct 2026
Handbook of Quantitative Finance and Risk Management
97% match

Handbook of Quantitative Finance and Risk Management

Springer
£674.19 12 Aug 2026
Risk and Financial Management: Mathematical and Computational Methods
97% match

Risk and Financial Management: Mathematical and Computational Methods

Wiley
£93.99 11 Sep 2026
Economic Foundations Of Risk Management, The: Theory, Practice, And Applications
97% match

Economic Foundations Of Risk Management, The: Theory, Practice, And Applications

Scientific Publishing
£50.88 17 Sep 2026
Counterparty Risk and Funding: A Tale of Two Puzzles (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Counterparty Risk and Funding: A Tale of Two Puzzles (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£49.76 02 Sep 2026
Numerical Methods for Finance - Chapman & Hall/CRC
97% match

Numerical Methods for Finance - Chapman & Hall/CRC

CRC Press
£190.00 13 Oct 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
97% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
97% match

Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation

MACMILLAN
£52.36 11 Sep 2026
MODELING AND PRICING OF SWAPS FOR FINANCIAL AND ENERGY MARKETS WITH STOCHASTIC VOLATILITIES
97% match

MODELING AND PRICING OF SWAPS FOR FINANCIAL AND ENERGY MARKETS WITH STOCHASTIC VOLATILITIES

World Scientific Publishing Company
£64.46 10 Sep 2026
Springer Martingale Methods in Financial Modelling - 2nd Ed
97% match

Springer Martingale Methods in Financial Modelling - 2nd Ed

Springer
£96.99 21 Aug 2026
Chapman and Hall/CRC Malliavin Calculus in Finance Textbook
97% match

Chapman and Hall/CRC Malliavin Calculus in Finance Textbook

Chapman and Hall/CRC
£104.00 15 Aug 2026
Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)
97% match

Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)

Springer
£82.06 24 Sep 2026
Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-Income Market
97% match

Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-Income Market

World Scientific Publishing Company
£53.52 06 Sep 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
97% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Market Risk Management for Hedge Funds: Foundations of the Style and Implicit Value-at-risk (Wiley Finance)
97% match

Market Risk Management for Hedge Funds: Foundations of the Style and Implicit Value-at-risk (Wiley Finance)

Wiley
£56.99 30 Sep 2026
Martingale Methods in Financial Modelling: 36 (Stochastic Modelling and Applied Probability, 36)
97% match

Martingale Methods in Financial Modelling: 36 (Stochastic Modelling and Applied Probability, 36)

Springer

£92.55 26 Aug 2026