£64.46

About as cheap as it gets — within 5% of the all-time low it hit 1 month ago.

£64 today · all-time low £63 (Aug 2026) · usually the usual

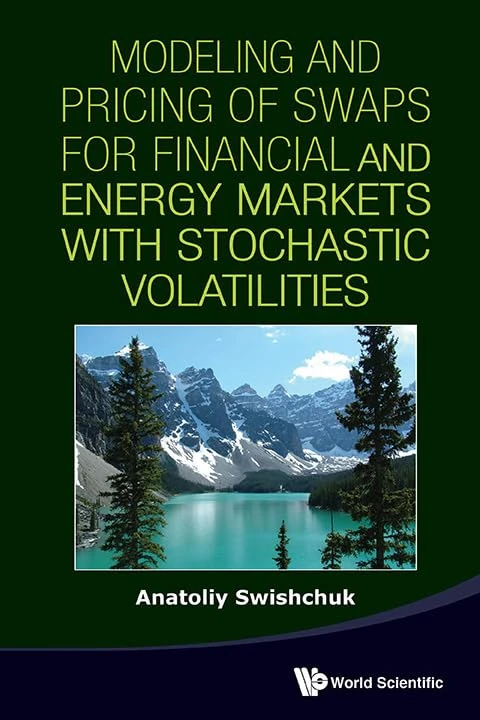
World Scientific Publishing Company MODELING AND PRICING OF SWAPS FOR FINANCIAL AND ENERGY MARKETS WITH STOCHASTIC VOLATILITIES

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 47 days · 47 data points (no recent data)

Historical
Generating forecast…
£64.88 £63.35 £63.68 £64.02 £64.35 £64.69 £65.02 26 July 2026 06 August 2026 18 August 2026 29 August 2026 10 September 2026
View at Amazon ↗

Price data last checked 44 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 47 days • 2 price levels

Days at Price
Current Price
13 days 34 days · current 0 9 17 26 34 £63 £65 Days at Price

Price Analysis

Most common price: £65 (34 days, 72.3%)

Price range: £63 - £65

Price levels: 2 different prices over 47 days

Description

Modeling and Pricing of Swaps for Financial and Energy Markets with Stochastic Volatilities is devoted to the modeling and pricing of various kinds of swaps, such as those for variance, volatility, covariance, correlation, for financial and energy markets with different stochastic volatilities, which include CIR process, regime-switching, delayed, mean-reverting, multi-factor, fractional, Levy-based, semi-Markov and COGARCH(1,1). One of the main methods used in this book is change of time method. The book outlines how the change of time method works for different kinds of models and problems arising in financial and energy markets and the associated problems in modeling and pricing of a variety of swaps. The book also contains a study of a new model, the delayed Heston model, which improves the volatility surface fitting as compared with the classical Heston model. The author calculates variance and volatility swaps for this model and provides hedging techniques. The book considers content on the pricing of variance and volatility swaps and option pricing formula for mean-reverting models in energy markets. Some topics such as forward and futures in energy markets priced by multi-factor Levy models and generalization of Black-76 formula with Markov-modulated volatility are part of the book as well, and it includes many numerical examples such as S&P60 Canada Index, S&P500 Index and AECO Natural Gas Index.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
03 August 2013
Listed Since
25 October 2012

Barcode

No barcode data available

Similar Products You Might Like
Chapman and Hall/CRC Malliavin Calculus in Finance Textbook
98% match

Chapman and Hall/CRC Malliavin Calculus in Finance Textbook

Chapman and Hall/CRC
£104.00 15 Aug 2026
The Heston Model and Its Extensions in VBA (Wiley Finance)
98% match

The Heston Model and Its Extensions in VBA (Wiley Finance)

Wiley
£94.33 06 Sep 2026
An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)
98% match

An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.82 20 Aug 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
98% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)
97% match

Market Risk Analysis, Quantitative Methods in Finance (The Wiley Finance Series)

Wiley
£45.99 11 Aug 2026
Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£105.00 20 Aug 2026
Ultimate Quant Job Interview Questions Workbook: Brief Crash Courses and Real Interview Questions taking you from Beginner to Wall Street Offers (The ... Quantitative Trading Strategies with Python)
97% match

Ultimate Quant Job Interview Questions Workbook: Brief Crash Courses and Real Interview Questions taking you from Beginner to Wall Street Offers (The ... Quantitative Trading Strategies with Python)

Price unavailable
Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)
97% match

Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)

Wiley
£63.98 19 Aug 2026
Option Pricing Models and Volatility Using Excel-VBA
97% match

Option Pricing Models and Volatility Using Excel-VBA

Wiley
£49.01 03 Sep 2026
Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models
97% match

Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models

Wiley
£160.65 15 Aug 2026
Volatility Surface and Term Structure - Options Trading Strategies
97% match

Volatility Surface and Term Structure - Options Trading Strategies

Routledge
£145.15 06 Oct 2026
The Heston Model and its Extensions in Matlab and C#, + Website (Wiley Finance)
97% match

The Heston Model and its Extensions in Matlab and C#, + Website (Wiley Finance)

Wiley
£69.23 14 Aug 2026
Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)
97% match

Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)

Routledge
£48.99 09 Sep 2026
Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives
97% match

Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives

Cambridge University Press
£49.79 07 Oct 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
97% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Stochastic Finance with Python: Design Financial Models from Probabilistic Perspective
97% match

Stochastic Finance with Python: Design Financial Models from Probabilistic Perspective

Apress
£39.55 12 Aug 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
97% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Aug 2026
Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)
97% match

Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)

Springer
£82.06 24 Sep 2026
Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)
97% match

Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)

Wiley
£60.99 17 Sep 2026
Change of Time Methods in Quantitative Finance - Springer
97% match

Change of Time Methods in Quantitative Finance - Springer

Springer
£49.14 21 Oct 2026
Springer Martingale Methods in Financial Modelling - 2nd Ed
97% match

Springer Martingale Methods in Financial Modelling - 2nd Ed

Springer
£96.99 21 Aug 2026
Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)
97% match

Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)

Springer
£46.51 10 Sep 2026
Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models
97% match

Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models

VDM Verlag

£61.00 11 Sep 2026