We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£108.68
This is the most expensive it has ever been. Walk away.
£109 today · previous high £109 · all-time low £103
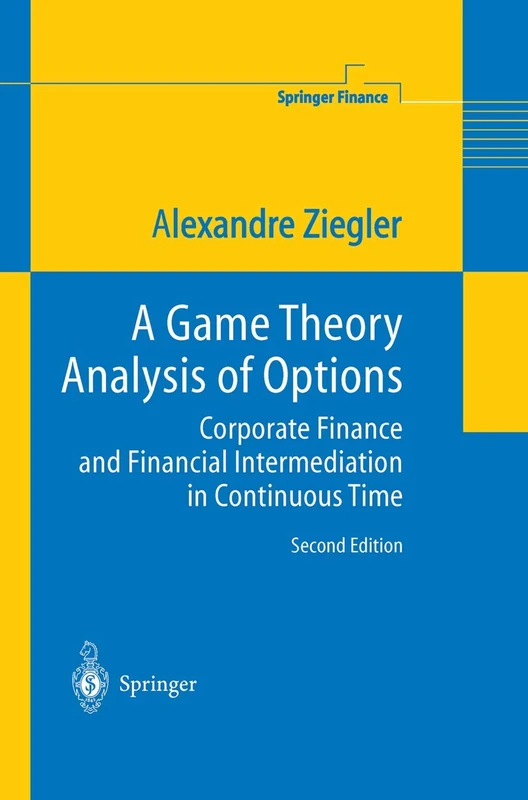
Springer - A Game Theory Analysis of Options Book
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 71 days · 71 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 71 days • 4 price levels
Price Analysis
Most common price: £108 (44 days, 62.0%)
Price range: £103 - £109
Price levels: 4 different prices over 71 days
Description
Key Features
This Springer Finance publication provides a deep look into modern option pricing theory and its mathematical foundations.
The text covers the historical development of analytical tools used for pricing and hedging option contracts and warrants.
Learn how levered firm equity can be treated as an option on firm value using advanced valuation techniques.
The content explores the relationship between option pricing and the default risk structure of firms.
This book is categorized under Game Theory and Optimization for advanced mathematical study.
Product Specifications
- Brand
- Springer
- Model
- biography
- Format
- paperback
- ASIN
- 3642058469
- Domain
- Amazon UK
- Release Date
- 07 December 2010
- Listed Since
- 13 June 2010
Barcode
No barcode data available
Similar Products You Might Like
Financial Markets and Corporate Finance: Selected Papers of Michael J. Brennan (Financial Economists of the Twentieth Century series)
Edward Elgar Publishing
Optionsbewertung und Risikomanagement unter gemischten Verteilungen: Theoretische Analyse und empirische Evaluation am europäischen Terminmarkt (Empirische Finanzmarktforschung/Empirical Finance)
Deutscher Universitätsverlag
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
MACMILLAN
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
MACMILLAN
CRC Press Financial Mathematics of Market Liquidity Book
CRC Press
An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)
CRC Press
Quantitative Finance: An Introduction to Investments, Asset Pricing, and Derivatives
Princeton University Press
Positional Option Trading: Advanced Guide - Wiley Trading
Wiley
Advanced Asset Pricing Theory: 2 (SERIES IN QUANTITATIVE FINANCE)
Imperial College Press
Options and Derivatives Programming in C++23: Algorithms and Programming Techniques for the Financial Industry
Apress
Real Options Theory: 24 (Advances in Strategic Management, 24)
Jai Press Inc.
World Scientific Fitting Local Volatility - Finance Book
World Scientific Publishing Company
Exotic Option Pricing and Advanced Lévy Models (Wilmott Collection)
Wiley
Wiley Derivatives: Models on Models - Finance Series Book
Wiley
Louis Bachelier's Theory of Speculation: The Origins of Modern Finance
Princeton University Press
Volatility and Correlation: The Perfect Hedger and the Fox: 278 (The Wiley Finance Series)
Wiley
Stochastic Finance: An Introduction in Discrete Time (De Gruyter Textbook)
De Gruyter
Portfolios of Real Options: 611 (Lecture Notes in Economics and Mathematical Systems, 611)
Springer
Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Financial Engineering: Derivatives and Risk Management
Wiley
Mathematical Finance: Theory, Modeling, Implementation
Wiley
Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)
Chapman and Hall/CRC
Genetic Adaptive Neural Networks for Option Pricing - Routledge
Routledge
Option Valuation under Stochastic Volatility II: With Mathematica Code
Finance Press