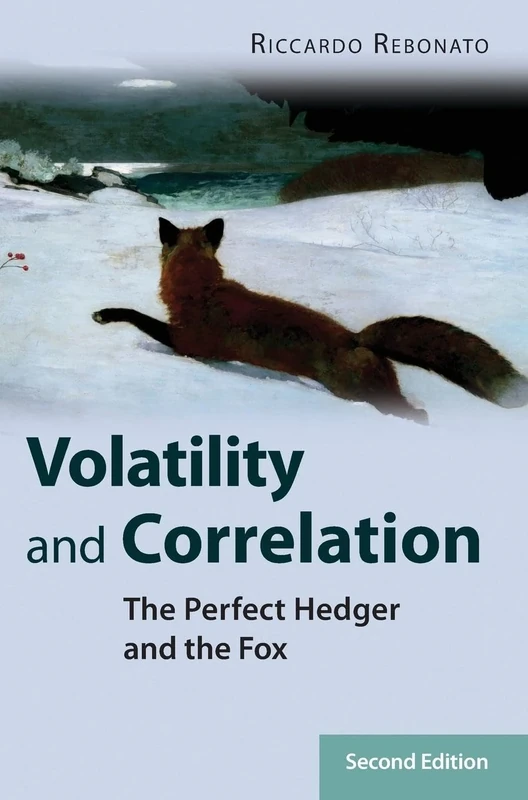
£94.68

This is the most expensive it has ever been. Walk away.

£95 today · previous high £95 · all-time low £86

Wiley Volatility and Correlation: The Perfect Hedger and the Fox: 278 (The Wiley Finance Series)

Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 89 days · 89 data points

Historical
Generating forecast…
£94.68 £85.15 £87.23 £89.31 £91.39 £93.47 £95.55 25 July 2026 16 August 2026 07 September 2026 29 September 2026 21 October 2026
View at Amazon ↗

Price data last checked 27 day(s) ago - will refresh soon

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 89 days • 7 price levels

Days at Price
Current Price
11 days 2 days 2 days 4 days 16 days 12 days 42 days · current 0 11 21 32 42 £86 £90 £91 £92 £93 £94 £95 Days at Price

Price Analysis

Most common price: £95 (42 days, 47.2%)

Price range: £86 - £95

Price levels: 7 different prices over 89 days

Description

In Volatility and Correlation 2nd edition: The Perfect Hedger and the Fox, Rebonato looks at derivatives pricing from the angle of volatility and correlation. With both practical and theoretical applications, this is a thorough update of the highly successful Volatility & Correlation – with over 80% new or fully reworked material and is a must have both for practitioners and for students. The new and updated material includes a critical examination of the ‘perfect-replication’ approach to derivatives pricing, with special attention given to exotic options; a thorough analysis of the role of quadratic variation in derivatives pricing and hedging; a discussion of the informational efficiency of markets in commonly-used calibration and hedging practices. Treatment of new models including Variance Gamma, displaced diffusion, stochastic volatility for interest-rate smiles and equity/FX options. The book is split into four parts. Part I deals with a Black world without smiles, sets out the author’s ‘philosophical’ approach and covers deterministic volatility. Part II looks at smiles in equity and FX worlds. It begins with a review of relevant empirical information about smiles, and provides coverage of local-stochastic-volatility, general-stochastic-volatility, jump-diffusion and Variance-Gamma processes. Part II concludes with an important chapter that discusses if and to what extent one can dispense with an explicit specification of a model, and can directly prescribe the dynamics of the smile surface. Part III focusses on interest rates when the volatility is deterministic. Part IV extends this setting in order to account for smiles in a financially motivated and computationally tractable manner. In this final part the author deals with CEV processes, with diffusive stochastic volatility and with Markov-chain processes. Praise for the First Edition: “In this book, Dr Rebonato brings his penetrating eye to bear on option pricing and hedging.… The book is a must-read for those who already know the basics of options and are looking for an edge in applying the more sophisticated approaches that have recently been developed.” ―Professor Ian Cooper, London Business School “Volatility and correlation are at the very core of all option pricing and hedging. In this book, Riccardo Rebonato presents the subject in his characteristically elegant and simple fashion…A rare combination of intellectual insight and practical common sense.” ―Anthony Neuberger, London Business School

Product Specifications

Brand
Wiley
Format
hardcover
Domain
Amazon UK
Release Date
03 August 2004
Listed Since
20 December 2006

Barcode

No barcode data available

Similar Products You Might Like
Option Pricing Models and Volatility Using Excel-VBA
98% match

Option Pricing Models and Volatility Using Excel-VBA

Wiley
£49.01 03 Sep 2026
The Heston Model and Its Extensions in VBA (Wiley Finance)
97% match

The Heston Model and Its Extensions in VBA (Wiley Finance)

Wiley
£94.33 06 Sep 2026
Options and Derivatives Programming in C++23: Algorithms and Programming Techniques for the Financial Industry
97% match

Options and Derivatives Programming in C++23: Algorithms and Programming Techniques for the Financial Industry

Apress
£33.34 18 Sep 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
97% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
McGraw-Hill Option Volatility and Pricing 2nd Edition Book
97% match

McGraw-Hill Option Volatility and Pricing 2nd Edition Book

McGraw-Hill Education
£64.20 26 Sep 2026
World Scientific Fitting Local Volatility - Finance Book
97% match

World Scientific Fitting Local Volatility - Finance Book

World Scientific Publishing Company
£55.68 03 Sep 2026
Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£45.99 09 Sep 2026
Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£157.03 25 Aug 2026
Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£48.99 13 Sep 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
97% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Financial Engineering: Derivatives and Risk Management
97% match

Financial Engineering: Derivatives and Risk Management

Wiley
£46.54 08 Sep 2026
Stochastic Finance: An Introduction in Discrete Time (De Gruyter Textbook)
97% match

Stochastic Finance: An Introduction in Discrete Time (De Gruyter Textbook)

De Gruyter
£58.99 08 Sep 2026
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
97% match

Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation

MACMILLAN
£52.36 11 Sep 2026
Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)
97% match

Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)

Wiley
£49.61 29 Aug 2026
American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)
97% match

American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£63.17 19 Sep 2026
How to Price and Trade Options + Website: Identify, Analyze, and Execute the Best Trade Probabilities (Bloomberg Financial)
97% match

How to Price and Trade Options + Website: Identify, Analyze, and Execute the Best Trade Probabilities (Bloomberg Financial)

Wiley
£42.39 08 Sep 2026
Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£119.37 12 Sep 2026
Options, futures et autres actifs dérivés : manuel - 11e édition
97% match

Options, futures et autres actifs dérivés : manuel - 11e édition

PEARSON EDUCATION
£49.93 26 Aug 2026
Exotic Option Pricing and Advanced Lévy Models (Wilmott Collection)
97% match

Exotic Option Pricing and Advanced Lévy Models (Wilmott Collection)

Wiley
£88.99 11 Sep 2026
Uncertain Volatility Models: Theory and Application (Springer Finance)
97% match

Uncertain Volatility Models: Theory and Application (Springer Finance)

Springer
£36.68 18 Sep 2026
The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)
97% match

The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)

£30.33 22 Sep 2026
Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)
97% match

Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)

Routledge
£48.99 09 Sep 2026
Option Theory with Stochastic Analysis: An Introduction to Mathematical Finance (Universitext)
97% match

Option Theory with Stochastic Analysis: An Introduction to Mathematical Finance (Universitext)

Springer

£29.12 11 Sep 2026