£36.68

This is the most expensive it has ever been. Walk away.

£37 today · previous high £37 · all-time low £36

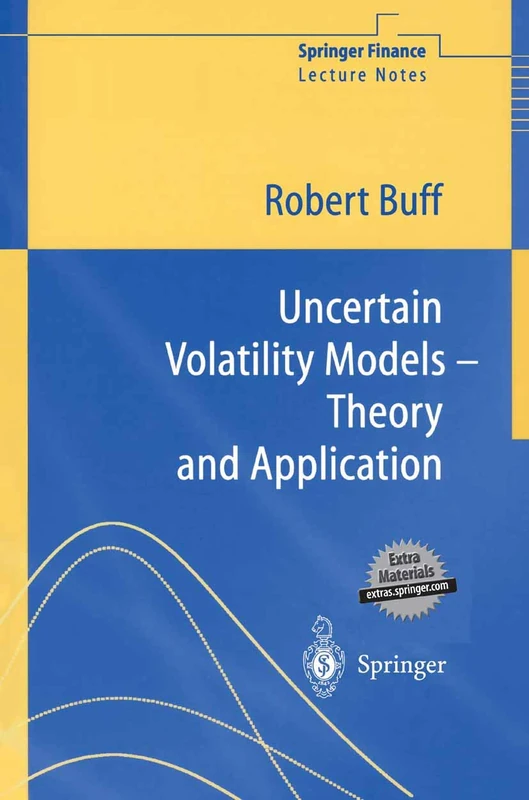
Springer Uncertain Volatility Models: Theory and Application (Springer Finance)

Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 56 days · 56 data points (no recent data)

Historical
Generating forecast…
£36.68 £35.86 £36.04 £36.21 £36.40 £36.58 £36.76 25 July 2026 07 August 2026 21 August 2026 04 September 2026 18 September 2026
View at Amazon ↗

A-109-615

Price data last checked 35 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 56 days • 1 price levels

Days at Price
56 days 0 14 28 42 56 £36 Days at Price

Price Analysis

Most common price: £36 (56 days, 100.0%)

Price range: £36 - £36

Price levels: 1 different prices over 56 days

Description

This book introduces Uncertain Volatility Models in mathematical finance. Uncertain Volatility Models evaluate option portfolios under worst- and best-case scenarios when the volatility coefficient of the pricing model cannot be determined exactly. The user defines subjective volatility constraints; within those constraints, extremal prices are computed. This book studies two types of constraints: volatility bands with upper and lower bounds, and shock scenarios with short periods of extreme volatility, but unkown timing. Uncertain Volatility Models are nonlinear. Worst- and best-case scenarios applied to isolated option positions do not always lead to the same extremal volatility. When applied to an options portfolio, a diversification effect reduces the overall exposure to volatility fluctuations within the subjective constraints. This book explores algorithmic issues that arise due to nonlinearity. Because Uncertain Volatility Models must be applied to option portfolios as a whole, they are difficult to implement on a computer if the portfolio contains barrier or American options. The accompanying CD contains a C++ implementation of Uncertain Volatility Models in source code. The software prices portfolios of vanilla, barrier and American options. This book is for graduate students, researchers and practitioners who wish to study advanced aspects of volatility risk in portfolios of vanilla and exotic options.

Product Specifications

Format
paperback
Domain
Amazon UK
Release Date
10 April 2002
Listed Since
01 February 2007

Barcode

No barcode data available

Similar Products You Might Like
Option Theory with Stochastic Analysis: An Introduction to Mathematical Finance (Universitext)
98% match

Option Theory with Stochastic Analysis: An Introduction to Mathematical Finance (Universitext)

Springer
£29.12 11 Sep 2026
Wiley The Volatility Smile - Finance Textbook for Students
98% match

Wiley The Volatility Smile - Finance Textbook for Students

Wiley
£39.28 19 Aug 2026
Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)
98% match

Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)

Routledge
£48.99 09 Sep 2026
Chapman and Hall/CRC Malliavin Calculus in Finance Textbook
98% match

Chapman and Hall/CRC Malliavin Calculus in Finance Textbook

Chapman and Hall/CRC
£104.00 15 Aug 2026
Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£48.99 13 Sep 2026
Volatility: Practical Options Theory (Wiley Finance)
98% match

Volatility: Practical Options Theory (Wiley Finance)

Wiley
£43.39 19 Aug 2026
Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£105.00 20 Aug 2026
An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)
97% match

An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.82 20 Aug 2026
World Scientific Fitting Local Volatility - Finance Book
97% match

World Scientific Fitting Local Volatility - Finance Book

World Scientific Publishing Company
£55.68 03 Sep 2026
The Heston Model and Its Extensions in VBA (Wiley Finance)
97% match

The Heston Model and Its Extensions in VBA (Wiley Finance)

Wiley
£94.33 06 Sep 2026
Volatility Surface and Term Structure - Options Trading Strategies
97% match

Volatility Surface and Term Structure - Options Trading Strategies

Routledge
£145.15 06 Oct 2026
Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£45.99 09 Sep 2026
Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)
97% match

Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments (The Wiley Finance Series)

Wiley
£63.98 19 Aug 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
97% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Pricing Models of Volatility Products and Exotic Variance Derivatives (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£119.37 12 Sep 2026
PRICING DERIVATIVE SECURITIES (2ND EDITION): Second Edition
97% match

PRICING DERIVATIVE SECURITIES (2ND EDITION): Second Edition

World Scientific Publishing Company
£38.10 07 Oct 2026
Option Pricing Models and Volatility Using Excel-VBA
97% match

Option Pricing Models and Volatility Using Excel-VBA

Wiley
£49.01 03 Sep 2026
Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Nonlinear Option Pricing (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£157.03 25 Aug 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£49.93 28 Aug 2026
Financial Mathematics, Derivatives and Structured Products - Springer Finance
97% match

Financial Mathematics, Derivatives and Structured Products - Springer Finance

Springer
£55.90 09 Oct 2026
Wiley Levy Processes in Finance: Pricing Financial Derivatives
97% match

Wiley Levy Processes in Finance: Pricing Financial Derivatives

Wiley
£93.72 18 Aug 2026
Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)
97% match

Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)

Wiley
£60.99 17 Sep 2026
Emerging Financial Derivatives - Exotic Options & Structured Products
97% match

Emerging Financial Derivatives - Exotic Options & Structured Products

Routledge
£65.35 03 Oct 2026
Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models
97% match

Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models

VDM Verlag

£61.00 11 Sep 2026