We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£50.86
About as cheap as it gets — within 5% of the all-time low it hit 2 months ago.
£51 today · all-time low £50 (Aug 2026) · usually the usual
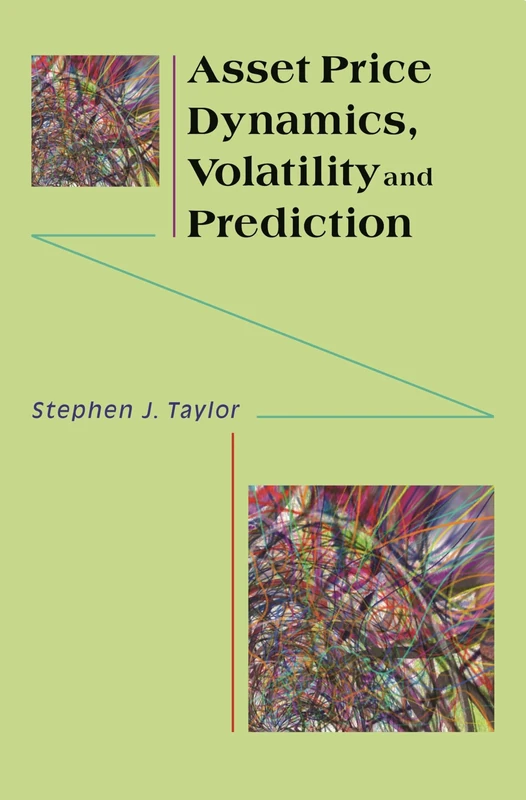
Princeton University Press - Asset Price Dynamics Book
Price data last checked 64 day(s) ago - refreshing...
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 27 days · 27 data points (no recent data)
Price data last checked 64 day(s) ago - refreshing...
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 27 days • 4 price levels
Price Analysis
Most common price: £51 (17 days, 63.0%)
Price range: £50 - £56
Price levels: 4 different prices over 27 days
Description
Key Features
This book by Princeton University Press covers asset price dynamics, volatility, and prediction methods.
Author Stephen Taylor applies empirical research methods from equity and foreign exchange markets.
Learn to use daily asset prices and option contract prices to construct predictions about future volatility.
The text provides a comprehensive introduction to the dynamic behavior of asset prices using finance methods.
This used book is delivered in good condition for your studies or professional research.
Product Specifications
- Format
- paperback
- ASIN
- 0691134790
- Domain
- Amazon UK
- Release Date
- 14 September 2007
- Listed Since
- 02 May 2007
Barcode
No barcode data available
Similar Products You Might Like
Stock Market Volatility (Chapman & Hall/CRC Finance Series)
CRC Press
Stock Market Volatility (Chapman & Hall/CRC Finance Series)
CRC Press
Dynamic Asset Pricing Theory: Third Edition (Princeton Series in Finance)
Princeton University Press
Handbook of Volatility Models and Their Applications: 03 (Wiley Handbooks in Financial Engineering and Econometrics)
Wiley
Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)
Wiley
Stochastic Volatility in Financial Markets: Crossing the Bridge to Continuous Time: 3 (Dynamic Modeling and Econometrics in Economics and Finance, 3)
Springer
Oxford Asset Pricing and Portfolio Choice Theory - 2nd Edition
Oxford University Press
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
Equity Derivatives and Hybrids: Markets, Models and Methods (Applied Quantitative Finance)
MACMILLAN
Econophysics of Stock and other Markets: Proceedings of the Econophys-Kolkata II (New Economic Windows)
Springer
Pathwise Estimation and Inference for Diffusion Market Models
CRC Press
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
Springer
DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE
World Scientific Publishing Company
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Asset Pricing: Modeling and Estimation (Springer Finance)
Springer
Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives
Cambridge University Press
Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R
Wiley
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Stochastic Volatility Modeling (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Financial Models with Levy Processes and Volatility Clustering: 187 (Frank J. Fabozzi Series)
Wiley
Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach
Wiley
Dynamics of Markets: The New Financial Economics
Cambridge University Press
Security Market Imperfections in Worldwide Equity Markets
Cambridge University Press