£49.33

This is the most expensive it has ever been. Walk away.

£49 today · previous high £49 · all-time low £47

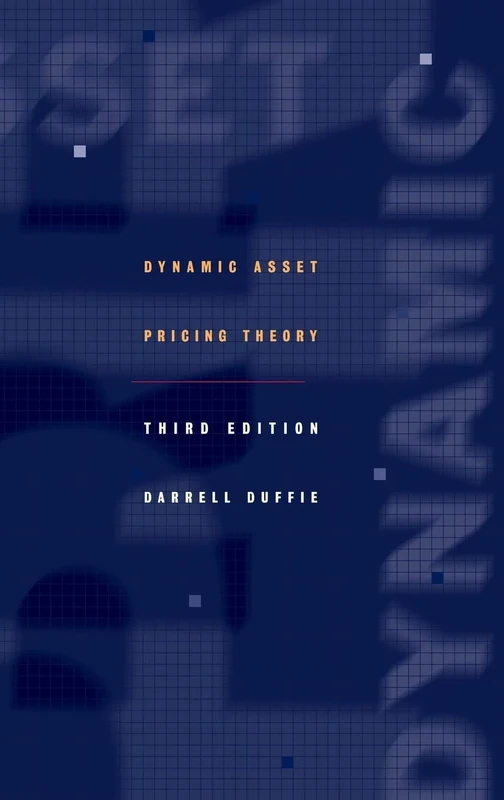
Princeton University Press Dynamic Asset Pricing Theory: Third Edition (Princeton Series in Finance)

Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 41 days · 41 data points (no recent data)

Historical
Generating forecast…
£49.33 £46.88 £47.41 £47.95 £48.48 £49.02 £49.55 25 July 2026 04 August 2026 14 August 2026 24 August 2026 03 September 2026
View at Amazon ↗

Navy, YES277874

Price data last checked 50 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 41 days • 2 price levels

Days at Price
Current Price
27 days 14 days · current 0 7 14 20 27 £47 £49 Days at Price

Price Analysis

Most common price: £47 (27 days, 65.9%)

Price range: £47 - £49

Price levels: 2 different prices over 41 days

Description

This is a thoroughly updated edition of Dynamic Asset Pricing Theory, the standard text for doctoral students and researchers on the theory of asset pricing and portfolio selection in multiperiod settings under uncertainty. The asset pricing results are based on the three increasingly restrictive assumptions: absence of arbitrage, single-agent optimality, and equilibrium. These results are unified with two key concepts, state prices and martingales. Technicalities are given relatively little emphasis, so as to draw connections between these concepts and to make plain the similarities between discrete and continuous-time models. Readers will be particularly intrigued by this latest edition's most significant new feature: a chapter on corporate securities that offers alternative approaches to the valuation of corporate debt. Also, while much of the continuous-time portion of the theory is based on Brownian motion, this third edition introduces jumps--for example, those associated with Poisson arrivals--in order to accommodate surprise events such as bond defaults. Applications include term-structure models, derivative valuation, and hedging methods. Numerical methods covered include Monte Carlo simulation and finite-difference solutions for partial differential equations. Each chapter provides extensive problem exercises and notes to the literature. A system of appendixes reviews the necessary mathematical concepts. And references have been updated throughout. With this new edition, Dynamic Asset Pricing Theory remains at the head of the field.

Key Features

New

Mint Condition

Dispatch same day for order received before 12 noon

Guaranteed packaging

No quibbles returns

Product Specifications

Colour
Navy
Format
hardcover
Domain
Amazon UK
Release Date
21 October 2001
Listed Since
16 December 2006

Barcode

No barcode data available

Similar Products You Might Like
Oxford Asset Pricing and Portfolio Choice Theory - 2nd Edition
98% match

Oxford Asset Pricing and Portfolio Choice Theory - 2nd Edition

Oxford University Press
£91.97 23 Oct 2026
Arbitrage Theory In Discrete And Continuous Time
98% match

Arbitrage Theory In Discrete And Continuous Time

World Scientific Publishing Company
£52.51 02 Oct 2026
Advanced Asset Pricing Theory: 2 (SERIES IN QUANTITATIVE FINANCE)
98% match

Advanced Asset Pricing Theory: 2 (SERIES IN QUANTITATIVE FINANCE)

Imperial College Press
£82.96 02 Oct 2026
Financial Mathematics: From Discrete to Continuous Time (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Financial Mathematics: From Discrete to Continuous Time (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.94 25 Sep 2026
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Sep 2026
DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE
98% match

DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE

World Scientific Publishing Company
£68.33 13 Sep 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£49.93 28 Aug 2026
The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)
98% match

The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)

£30.33 22 Sep 2026
MIT Press - The Economics of Continuous-Time Finance Book
98% match

MIT Press - The Economics of Continuous-Time Finance Book

MIT Press
£44.21 22 Oct 2026
Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£95.72 25 Sep 2026
A Factor Model Approach to Derivative Pricing
97% match

A Factor Model Approach to Derivative Pricing

CRC Press
£183.52 03 Sep 2026
Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)
97% match

Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)

Springer
£46.51 10 Sep 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
97% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
97% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Quantitative Finance: A Simulation-Based Introduction Using Excel
97% match

Quantitative Finance: A Simulation-Based Introduction Using Excel

CRC Press
£68.99 16 Sep 2026
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
97% match

Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)

Springer
£94.74 24 Sep 2026
Options Pricing and Portfolio Optimization: Modern Methods of Financial Mathematics (Graduate Studies in Mathematics)
97% match

Options Pricing and Portfolio Optimization: Modern Methods of Financial Mathematics (Graduate Studies in Mathematics)

Brand: Amer Mathematical Society
£47.50 08 Sep 2026
Springer Monte Carlo Methods in Financial Engineering Book
97% match

Springer Monte Carlo Methods in Financial Engineering Book

Springer
£64.99 12 Sep 2026
Stochastic Calculus for Quantitative Finance: Stochastic Calculus for Finance
97% match

Stochastic Calculus for Quantitative Finance: Stochastic Calculus for Finance

Elsevier
£62.50 12 Sep 2026
Princeton Mathematical Techniques in Finance - 2nd Edition
97% match

Princeton Mathematical Techniques in Finance - 2nd Edition

Princeton University Press
£55.27 28 Aug 2026
Majosta Applied Quantitative Finance for Equity Derivatives
97% match

Majosta Applied Quantitative Finance for Equity Derivatives

Majosta
£90.85 05 Sep 2026
Wiley Paul Wilmott on Quantitative Finance 2nd Edition
97% match

Wiley Paul Wilmott on Quantitative Finance 2nd Edition

Wiley

£160.98 21 Oct 2026