£45.95

It has never been this cheap. We have no record of a lower price.

£46 today · cheaper than every other day in the last 3 months

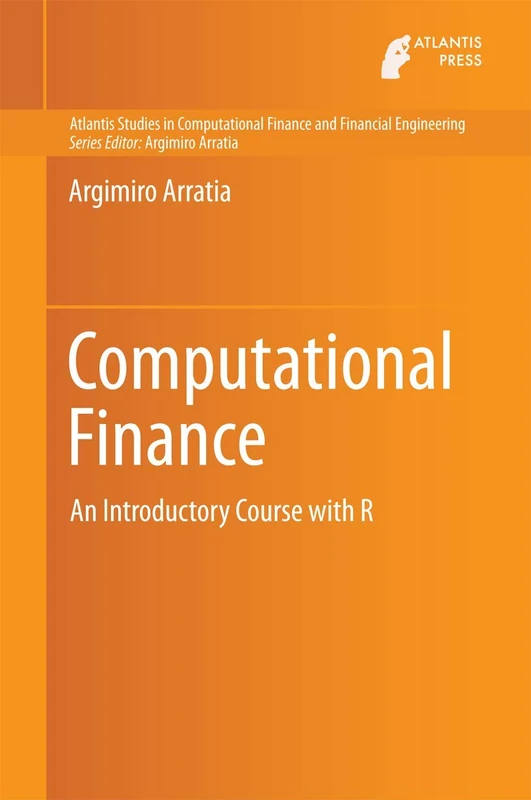
Springer Computational Finance: An Introductory Course with R: 1 (Atlantis Studies in Computational Finance and Financial Engineering, 1)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 48 days · 48 data points (no recent data)

Historical
Generating forecast…
£51.31 £45.41 £46.70 £47.99 £49.27 £50.56 £51.85 25 July 2026 05 August 2026 17 August 2026 29 August 2026 10 September 2026
View at Amazon ↗

Price data last checked 43 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 48 days • 3 price levels

Days at Price
Current Price
13 days · current 27 days 8 days 0 7 14 20 27 £46 £49 £51 Days at Price

Price Analysis

Most common price: £49 (27 days, 56.3%)

Price range: £46 - £51

Price levels: 3 different prices over 48 days

Description

The book covers a wide range of topics, yet essential, in Computational Finance (CF), understood as a mix of Finance, Computational Statistics, and Mathematics of Finance. In that regard it is unique in its kind, for it touches upon the basic principles of all three main components of CF, with hands-on examples for programming models in R. Thus, the first chapter gives an introduction to the Principles of Corporate Finance: the markets of stock and options, valuation and economic theory, framed within Computation and Information Theory (e.g. the famous Efficient Market Hypothesis is stated in terms of computational complexity, a new perspective). Chapters 2 and 3 give the necessary tools of Statistics for analyzing financial time series, it also goes in depth into the concepts of correlation, causality and clustering. Chapters 4 and 5 review the most important discrete and continuous models for financial time series. Each model is provided with an example program in R. Chapter 6 covers the essentials of Technical Analysis (TA) and Fundamental Analysis. This chapter is suitable for people outside academics and into the world of financial investments, as a primer in the methods of charting and analysis of value for stocks, as it is done in the financial industry. Moreover, a mathematical foundation to the seemly ad-hoc methods of TA is given, and this is new in a presentation of TA. Chapter 7 reviews the most important heuristics for optimization: simulated annealing, genetic programming, and ant colonies (swarm intelligence) which is material to feed the computer savvy readers. Chapter 8 gives the basic principles of portfolio management, through the mean-variance model, and optimization under different constraints which is a topic of current research in computation, due to its complexity. One important aspect of this chapter is that it teaches how to use the powerful tools for portfolio analysis from the RMetrics R-package. Chapter 9 is a naturalcontinuation of chapter 8 into the new area of research of online portfolio selection. The basic model of the universal portfolio of Cover and approximate methods to compute are also described.

Key Features

Computational Finance: An Introductory Course with R: 1 (Atlantis Studies in Computational Finance and Financial Engineering, 1)

ABIS BOOK

Jumper

Yellow

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
20 May 2014
Listed Since
21 February 2014

Barcode

No barcode data available

Similar Products You Might Like
Fuzzy Portfolio Optimization: Advances in Hybrid Multi-criteria Methodologies: 316 (Studies in Fuzziness and Soft Computing, 316)
97% match

Fuzzy Portfolio Optimization: Advances in Hybrid Multi-criteria Methodologies: 316 (Studies in Fuzziness and Soft Computing, 316)

Springer
£110.38 01 Oct 2026
CRC Press Quantitative Equity Portfolio Management Book
97% match

CRC Press Quantitative Equity Portfolio Management Book

CRC Press
£110.25 20 Oct 2026
Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)
97% match

Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)

Springer
£26.54 11 Sep 2026
Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)
97% match

Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)

Springer
£35.35 11 Sep 2026
Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™
97% match

Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™

Springer
£89.99 24 Sep 2026
Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£58.50 02 Oct 2026
Financial Mathematics: From Discrete to Continuous Time (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Financial Mathematics: From Discrete to Continuous Time (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.94 25 Sep 2026
Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)
96% match

Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£94.64 23 Sep 2026
Cambridge University Press Portfolio Optimization Guide
96% match

Cambridge University Press Portfolio Optimization Guide

Cambridge University Press
£60.73 22 Oct 2026
Investment Analysis: An Introduction to Portfolio Theory and Management
96% match

Investment Analysis: An Introduction to Portfolio Theory and Management

Routledge
£57.99 23 Sep 2026
Wiley Portfolio Performance Guide - Asset & Wealth Management
96% match

Wiley Portfolio Performance Guide - Asset & Wealth Management

Wiley
£54.81 26 Sep 2026
Quantitative Portfolio Optimisation, Asset Allocation and Risk Management: A Practical Guide to Implementing Quantitative Investment Theory (Finance and Capital Markets Series)
96% match

Quantitative Portfolio Optimisation, Asset Allocation and Risk Management: A Practical Guide to Implementing Quantitative Investment Theory (Finance and Capital Markets Series)

MACMILLAN
£212.37 30 Sep 2026
Portfolio Management with Heuristic Optimization: 8 (Advances in Computational Management Science, 8)
96% match

Portfolio Management with Heuristic Optimization: 8 (Advances in Computational Management Science, 8)

Springer
£73.85 22 Sep 2026
Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)
96% match

Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press

£74.45 25 Sep 2026