£35.35

It has never been this cheap. We have no record of a lower price.

£35 today · cheaper than every other day in the last 3 months

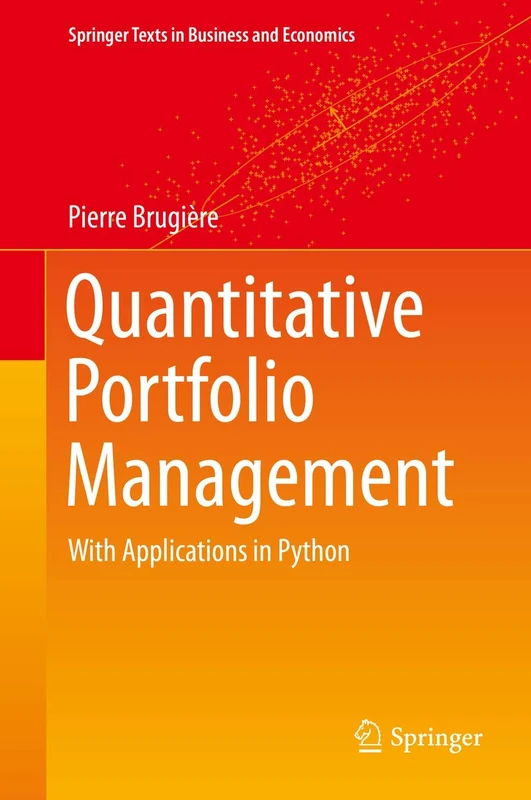
Springer Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 48 days · 48 data points (no recent data)

Historical
Generating forecast…
£35.39 £35.35 £35.36 £35.37 £35.37 £35.38 £35.39 26 July 2026 06 August 2026 18 August 2026 30 August 2026 11 September 2026
View at Amazon ↗

Price data last checked 43 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 48 days • 1 price levels

Days at Price
48 days 0 12 24 36 48 £35 Days at Price

Price Analysis

Most common price: £35 (48 days, 100.0%)

Price range: £35 - £35

Price levels: 1 different prices over 48 days

Description

This self-contained book presents the main techniques of quantitative portfolio management and associated statistical methods in a very didactic and structured way, in a minimum number of pages. The concepts of investment portfolios, self-financing portfolios and absence of arbitrage opportunities are extensively used and enable the translation of all the mathematical concepts in an easily interpretable way. All the results, tested with Python programs, are demonstrated rigorously, often using geometric approaches for optimization problems and intrinsic approaches for statistical methods, leading to unusually short and elegant proofs. The statistical methods concern both parametric and non-parametric estimators and, to estimate the factors of a model, principal component analysis is explained. The presented Python code and web scraping techniques also make it possible to test the presented concepts on market data. This book will be useful for teaching Masters students and for professionals in asset management, and will be of interest to academics who want to explore a field in which they are not specialists. The ideal pre-requisites consist of undergraduate probability and statistics and a familiarity with linear algebra and matrix manipulation. Those who want to run the code will have to install Python on their pc, or alternatively can use Google Colab on the cloud. Professionals will need to have a quantitative background, being either portfolio managers or risk managers, or potentially quants wanting to double check their understanding of the subject.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
29 March 2020
Listed Since
16 November 2019

Barcode

No barcode data available

Similar Products You Might Like
Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)
100% match

Quantitative Portfolio Management: with Applications in Python (Springer Texts in Business and Economics)

Springer
£26.54 11 Sep 2026
Lectures On The Theory And Application Of Modern Finance With R And Chatgpt: 10 (World Scientific Lecture Notes in Finance)
98% match

Lectures On The Theory And Application Of Modern Finance With R And Chatgpt: 10 (World Scientific Lecture Notes in Finance)

World Scientific Publishing Company
£63.67 29 Aug 2026
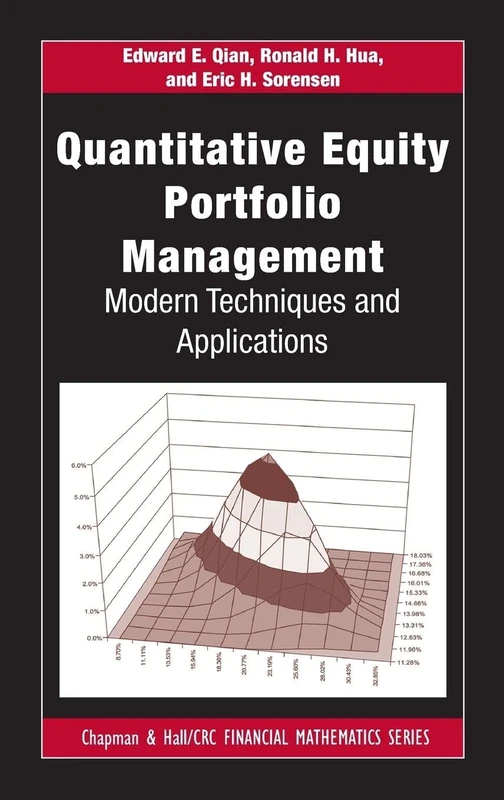
CRC Press Quantitative Equity Portfolio Management Book
98% match

CRC Press Quantitative Equity Portfolio Management Book

CRC Press
£110.25 20 Oct 2026
Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing
97% match

Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing

McGraw-Hill Education
£41.88 04 Sep 2026
Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£58.50 02 Oct 2026
Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Portfolio Optimization (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£94.64 23 Sep 2026
Quantitative Portfolio Optimisation, Asset Allocation and Risk Management: A Practical Guide to Implementing Quantitative Investment Theory (Finance and Capital Markets Series)
97% match

Quantitative Portfolio Optimisation, Asset Allocation and Risk Management: A Practical Guide to Implementing Quantitative Investment Theory (Finance and Capital Markets Series)

MACMILLAN
£212.37 30 Sep 2026
Investment Analysis: An Introduction to Portfolio Theory and Management
97% match

Investment Analysis: An Introduction to Portfolio Theory and Management

Routledge
£57.99 23 Sep 2026
Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™
97% match

Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™

Springer
£89.99 24 Sep 2026
Investment Theory and Risk Management: 711 (Wiley Finance)
97% match

Investment Theory and Risk Management: 711 (Wiley Finance)

Wiley
£67.25 23 Sep 2026
Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£74.45 25 Sep 2026
Computational Finance: An Introductory Course with R: 1 (Atlantis Studies in Computational Finance and Financial Engineering, 1)
97% match

Computational Finance: An Introductory Course with R: 1 (Atlantis Studies in Computational Finance and Financial Engineering, 1)

Springer
£45.95 10 Sep 2026
Fuzzy Portfolio Optimization: Advances in Hybrid Multi-criteria Methodologies: 316 (Studies in Fuzziness and Soft Computing, 316)
97% match

Fuzzy Portfolio Optimization: Advances in Hybrid Multi-criteria Methodologies: 316 (Studies in Fuzziness and Soft Computing, 316)

Springer
£110.38 01 Oct 2026
Quantitative Fund Management (Chapman & Hall/CRC Financial Mathematics)
97% match

Quantitative Fund Management (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.97 25 Sep 2026
Risk and Asset Allocation - Springer Finance Guide
97% match

Risk and Asset Allocation - Springer Finance Guide

Springer
£62.45 24 Oct 2026
Wiley Portfolio Performance Guide - Asset & Wealth Management
97% match

Wiley Portfolio Performance Guide - Asset & Wealth Management

Wiley
£54.81 26 Sep 2026
Risk and Asset Allocation (Springer Finance)
97% match

Risk and Asset Allocation (Springer Finance)

Springer
£89.95 04 Sep 2026
Cambridge University Press Portfolio Optimization Guide
97% match

Cambridge University Press Portfolio Optimization Guide

Cambridge University Press
£60.54 24 Oct 2026
Modern Portfolio Theory, + Website: Foundations, Analysis, and New Developments: 795 (Wiley Finance)
97% match

Modern Portfolio Theory, + Website: Foundations, Analysis, and New Developments: 795 (Wiley Finance)

Wiley

£51.93 19 Sep 2026