We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
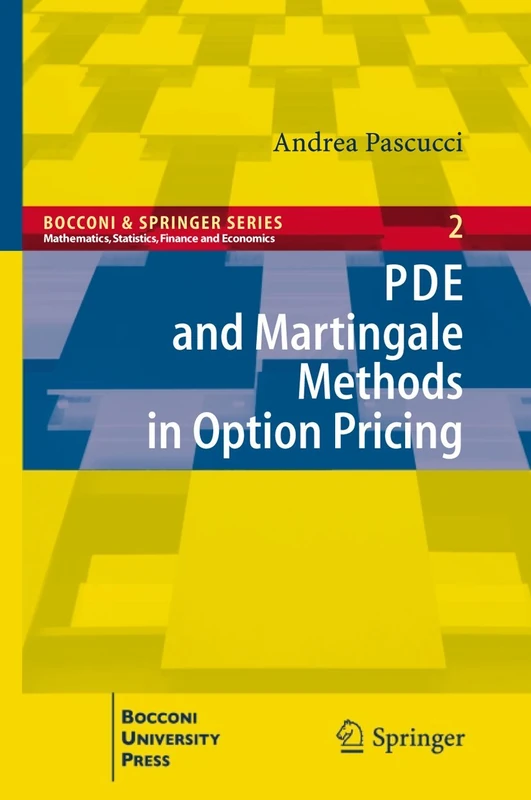
£85.75
Springer PDE and Martingale Methods in Option Pricing: 02 (Bocconi & Springer Series)
Price data last checked 11 day(s) ago - will refresh soon
We'll watch every seller, every day. One email when your price arrives.
About as cheap as it gets. The only time it was cheaper was 3 months ago.
£86 today · all-time low £83 (Jun 2026) · usually £96
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 80 days · 80 data points (no recent data)
Price Distribution
Price distribution over 80 days • 3 price levels
Price Analysis
Most common price: £96 (67 days, 83.8%)
Price range: £83 - £96
Price levels: 3 different prices over 80 days
Description
Product Specifications
- Brand
- Springer
- Format
- hardcover
- ASIN
- 8847017807
- Domain
- Amazon UK
- Release Date
- 28 December 2010
- Listed Since
- 12 June 2010
Barcode
No barcode data available
Similar Products You Might Like
Topics in Numerical Methods for Finance: 19 (Springer Proceedings in Mathematics & Statistics, 19)
Springer
Derivative Securities and Difference Methods (Springer Finance)
Springer
Price unavailable
Mathematics Of Computational Finance
World Scientific Publishing Company
Derivative Securities and Difference Methods (Springer Finance)
Springer
Numerical Methods in Finance: Bordeaux, June 2010: 12 (Springer Proceedings in Mathematics, 12)
Springer
Diffusions and Elliptic Operators (Probability and Its Applications)
Springer
Option Pricing and Estimation of Financial Models with R
Wiley
Tools for Computational Finance (Universitext)
Springer
Introduction to the Mathematics of Finance: Arbitrage and Option Pricing (Undergraduate Texts in Mathematics)
Springer
The Art of Quantitative Finance Vol.2: Volatilities, Stochastic Analysis and Valuation Tools (Springer Texts in Business and Economics)
Springer
Contract Theory in Continuous-Time Models (Springer Finance)
Springer
American-Type Options: Stochastic Approximation Methods, Volume 1 (De Gruyter Studies in Mathematics): 56
De Gruyter
Applications of Fourier Transform to Smile Modeling: Theory and Implementation (Springer Finance)
Springer
Financial Market Analytics
Bloomsbury
Optimization and Games for Controllable Markov Chains: Numerical Methods with Application to Finance and Engineering: 504 (Studies in Systems, Decision and Control, 504)
Springer
A Game Theory Analysis of Options: Corporate Finance and Financial Intermediation in Continuous Time (Springer Finance)
Springer
Brownian Motion, Martingales, and Stochastic Calculus: 274 (Graduate Texts in Mathematics, 274)
Springer
Numerical Simulation of Distributed Parameter Processes
Springer

Springer Brownian Motion, Martingales, and Stochastic Calculus
Springer

Probability and Partial Differential Equations in Modern Applied Mathematics: 140 (The IMA Volumes in Mathematics and its Applications, 140)
Springer
Novel Methods in Computational Finance: 25 (Mathematics in Industry, 25)
Springer

McGraw-Hill Option Pricing Formulas - Professional Finance Guide
McGraw-Hill Education
Financial Mathematics: A Comprehensive Treatment in Continuous Time Volume II (Textbooks in Mathematics)
CRC Press
Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)
Springer