£104.99

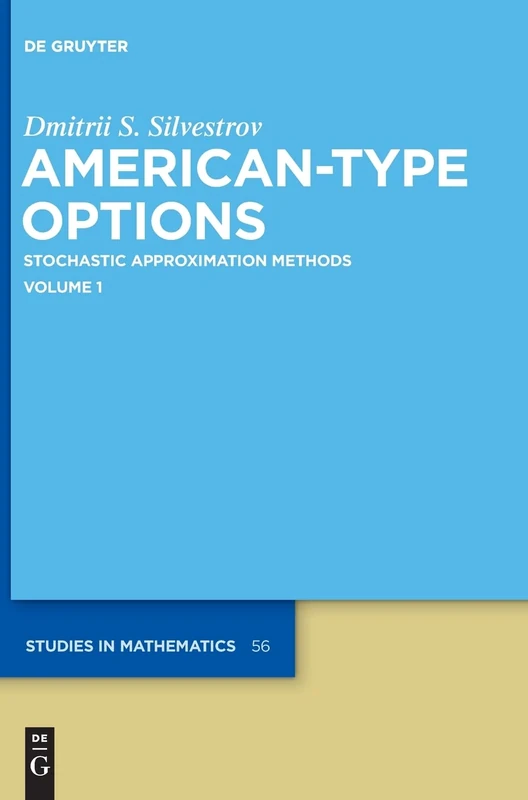
De Gruyter American-Type Options: Stochastic Approximation Methods, Volume 1 (De Gruyter Studies in Mathematics): 56

Price data last checked 11 day(s) ago - will refresh soon

View at Amazon

We'll watch every seller, every day. One email when your price arrives.

It has never been this cheap. We have no record of a lower price.

£105 today · cheaper than every other day in the last 3 months

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↓ Price chart
when this has been cheap or pricey
↓ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 80 days · 80 data points (no recent data)

Historical
Generating forecast…
£156.16 £99.87 £112.15 £124.43 £136.72 £149.00 £161.28 27 June 2026 16 July 2026 05 August 2026 25 August 2026 14 September 2026

Price Distribution

Price distribution over 80 days • 2 price levels

Days at Price
Current Price
34 days · current 46 days 0 12 23 35 46 £105 £156 Days at Price

Price Analysis

Most common price: £156 (46 days, 57.5%)

Price range: £105 - £156

Price levels: 2 different prices over 80 days

Description

The book gives a systematical presentation of stochastic approximation methods for models of American-type options with general pay-off functions for discrete time Markov price processes. Advanced methods combining backward recurrence algorithms for computing of option rewards and general results on convergence of stochastic space skeleton and tree approximations for option rewards are applied to a variety of models of multivariate modulated Markov price processes. The principal novelty of presented results is based on consideration of multivariate modulated Markov price processes and general pay-off functions, which can depend not only on price but also an additional stochastic modulating index component, and use of minimal conditions of smoothness for transition probabilities and pay-off functions, compactness conditions for log-price processes and rate of growth conditions for pay-off functions. The book also contains an extended bibliography of works in the area. This book is the first volume of the comprehensive two volumes monograph. The second volume will present results on structural studies of optimal stopping domains, Monte Carlo based approximation reward algorithms, and convergence of American-type options for autoregressive and continuous time models, as well as results of the corresponding experimental studies.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
30 November 2013
Listed Since
07 July 2013

Barcode

No barcode data available

Similar Products You Might Like
Stochastic Approximation: A Dynamical Systems Viewpoint: 48 (Texts and Readings in Mathematics, 48)
82% match

Stochastic Approximation: A Dynamical Systems Viewpoint: 48 (Texts and Readings in Mathematics, 48)

Springer
£87.00 19 Aug 2026
Topics in Numerical Methods for Finance: 19 (Springer Proceedings in Mathematics & Statistics, 19)
82% match

Topics in Numerical Methods for Finance: 19 (Springer Proceedings in Mathematics & Statistics, 19)

Springer
£74.76 06 Aug 2026
Option Pricing and Estimation of Financial Models with R
81% match

Option Pricing and Estimation of Financial Models with R

Wiley
£77.39 17 Aug 2026
Relative Optimization of Continuous-Time and Continuous-State Stochastic Systems (Communications and Control Engineering)
81% match

Relative Optimization of Continuous-Time and Continuous-State Stochastic Systems (Communications and Control Engineering)

Springer
£108.01 05 Aug 2026
Optimization and Games for Controllable Markov Chains: Numerical Methods with Application to Finance and Engineering: 504 (Studies in Systems, Decision and Control, 504)
80% match

Optimization and Games for Controllable Markov Chains: Numerical Methods with Application to Finance and Engineering: 504 (Studies in Systems, Decision and Control, 504)

Springer
£97.00 19 Aug 2026
Yosida Approximations of Stochastic Differential Equations in Infinite Dimensions and Applications: 79 (Probability Theory and Stochastic Modelling, 79)
80% match

Yosida Approximations of Stochastic Differential Equations in Infinite Dimensions and Applications: 79 (Probability Theory and Stochastic Modelling, 79)

Springer
£92.19 05 Aug 2026
Stochastic Models and Option Values: Applications to Resources, Environment and Investment Problems: 200 (Contributions to Economic Analysis, 200)
80% match

Stochastic Models and Option Values: Applications to Resources, Environment and Investment Problems: 200 (Contributions to Economic Analysis, 200)

Parlux
£124.41 18 Aug 2026
Stochastic Methods for Boundary Value Problems: Numerics for High-dimensional PDEs and Applications
80% match

Stochastic Methods for Boundary Value Problems: Numerics for High-dimensional PDEs and Applications

De Gruyter
£91.00 29 Aug 2026
Statistics of Random Processes: I. General Theory: 5 (Stochastic Modelling and Applied Probability, 5)
80% match

Statistics of Random Processes: I. General Theory: 5 (Stochastic Modelling and Applied Probability, 5)

Springer
£87.45 08 Aug 2026
Mouvement brownien, martingales et calcul stochastique: 71 (Mathématiques et Applications, 71)
80% match

Mouvement brownien, martingales et calcul stochastique: 71 (Mathématiques et Applications, 71)

Springer
£52.43 04 Aug 2026
Basics of Applied Stochastic Processes (Probability and Its Applications)
80% match

Basics of Applied Stochastic Processes (Probability and Its Applications)

Springer
£46.02 03 Aug 2026
Contract Theory in Continuous-Time Models (Springer Finance)
80% match

Contract Theory in Continuous-Time Models (Springer Finance)

Springer
£73.14 05 Aug 2026
Stochastic Analysis with Financial Applications: Hong Kong 2009: 65 (Progress in Probability, 65)
79% match

Stochastic Analysis with Financial Applications: Hong Kong 2009: 65 (Progress in Probability, 65)

Birkhauser
£76.42 05 Aug 2026
Derivative Securities and Difference Methods (Springer Finance)
79% match

Derivative Securities and Difference Methods (Springer Finance)

Springer

Price unavailable
Mathematical Methods in Robust Control of Discrete-Time Linear Stochastic Systems
79% match

Mathematical Methods in Robust Control of Discrete-Time Linear Stochastic Systems

Springer

£106.69 05 Aug 2026
Numerical Methods for Controlled Stochastic Delay Systems (Systems & Control: Foundations & Applications)
79% match

Numerical Methods for Controlled Stochastic Delay Systems (Systems & Control: Foundations & Applications)

Birkhauser

£42.83 08 Aug 2026
Semigroups, Boundary Value Problems and Markov Processes (Springer Monographs in Mathematics)
79% match

Semigroups, Boundary Value Problems and Markov Processes (Springer Monographs in Mathematics)

Springer

£93.29 05 Aug 2026
Stochastic Equations: Theory and Applications in Acoustics, Hydrodynamics, Magnetohydrodynamics, and Radiophysics, Volume 1: Basic Concepts, Exact ... (Understanding Complex Systems)
79% match

Stochastic Equations: Theory and Applications in Acoustics, Hydrodynamics, Magnetohydrodynamics, and Radiophysics, Volume 1: Basic Concepts, Exact ... (Understanding Complex Systems)

Springer
£76.42 08 Aug 2026
Stochastic Optimization in Continuous Time
79% match

Stochastic Optimization in Continuous Time

Cambridge University Press
£44.00 17 Sep 2026
Optimal Statistical Inference in Financial Engineering
79% match

Optimal Statistical Inference in Financial Engineering

CRC Press
£164.04 04 Aug 2026
Dynamic Portfolio Strategies: quantitative methods and empirical rules for incomplete information: Quantitative Methods and Empirical Rules for ... Operations Research & Management Science, 47)
79% match

Dynamic Portfolio Strategies: quantitative methods and empirical rules for incomplete information: Quantitative Methods and Empirical Rules for ... Operations Research & Management Science, 47)

Springer
£75.58 05 Aug 2026
Financial Market Analytics
79% match

Financial Market Analytics

Bloomsbury

£64.50 13 Aug 2026
Mathematics Of Computational Finance
79% match

Mathematics Of Computational Finance

World Scientific Publishing Company
£96.47 12 Aug 2026
Numerical Methods in Finance: Bordeaux, June 2010: 12 (Springer Proceedings in Mathematics, 12)
79% match

Numerical Methods in Finance: Bordeaux, June 2010: 12 (Springer Proceedings in Mathematics, 12)

Springer

£100.11 06 Aug 2026