We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£53.84
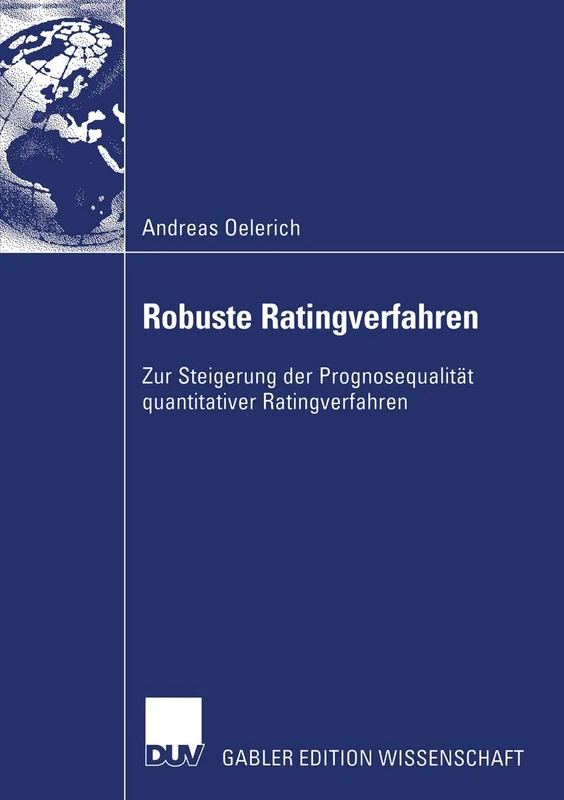
Deutscher Universitätsverlag Robuste Ratingverfahren: Zur Steigerung der Prognosequalität quantitativer Ratingverfahren
Price data last checked 23 day(s) ago - will refresh soon
We'll watch every seller, every day. One email when your price arrives.
It has never been this cheap. We have no record of a lower price.
£54 today · cheaper than every other day in the last 3 months
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 68 days · 68 data points (no recent data)
Price Distribution
Price distribution over 68 days • 1 price levels
Price Analysis
Most common price: £54 (68 days, 100.0%)
Price range: £54 - £54
Price levels: 1 different prices over 68 days
Description
Product Specifications
- Format
- paperback
- ASIN
- 3824483041
- Domain
- Amazon UK
- Release Date
- 30 May 2005
- Listed Since
- 11 February 2007
Barcode
No barcode data available
Similar Products You Might Like
Value at Risk für Kreditinstitute: Erfassung des aggregierten Marktrisikopotentials (Bank- und Finanzwirtschaft)
Deutscher Universitätsverlag

Qualität des Aktienresearch von Finanzanalysten: Eine theoretische und empirische Untersuchung der Gewinnprognosen und Aktienempfehlungen am deutschen Kapitalmarkt (Geld - Banken - Börsen)
Springer
Handbook of Ratings: Approaches to Ratings in the Economy, Sports, and Society
Springer

Fortgeschrittene Finanzmodellierung für Aktienkursprognosen: A Quantitative Methoden

Assessment of Power System Reliability: Methods and Applications
Springer

VERBESSERUNG DER METHODIK DES KREDITRISIKOMANAGEMENTS DURCH GESCHÄFTSBANKEN: Diese Monographie widmet sich einer eingehenden Analyse der theoretischen und methodologischen Grundlagen

Standardisierte Strategiebewertung als Beitrag zum Unternehmensrating: Eine empirische Analyse mit Hilfe von Strukturgleichungsmodellen
VDM Verlag
Numerical Methods and Optimization in Finance
Elsevier

Bewertung und Management finanzieller Risiken mit Six Sigma DMAIC-Methoden: Neue Forschung und Möglichkeiten für Basel III und Solvency II

Handbook of Ratings: Approaches to Ratings in the Economy, Sports, and Society
Springer

Risikotragfähigkeit in Kreditinstituten: Ermittlung, Beurteilung, Weiterentwicklungspotenzial
GRIN Verlag

Computational Finance with R (Indian Statistical Institute Series)
Springer

Der Ansatz der Realoptionen zur Investitionsbewertung im Vergleich zu ausgewählten traditionellen Verfahren
Diplomica Verlag

Die Bedeutung des Controllings bei Ratingverfahren im Rahmen von Basel II
GRIN Verlag
Die Bewertung von Kreditinstituten: Erfassung und Bewertung bankspezifischer Risiken
Igel Verlag
Basel III Credit Rating Systems: An Applied Guide to Quantitative and Qualitative Models (Finance and Capital Markets Series)
MACMILLAN
Hedge-Accounting: Jahresabschlußrisiken in Banken
Gabler Verlag
Optimal Statistical Inference in Financial Engineering
CRC Press

Die Prognosefähigkeit von Machine Learning-Verfahren und Managementschätzungen im Rahmen von finanziellen Unternehmenskennzahlen. Ein Vergleich
GRIN Verlag
Risikomanagement bei Immobilieninvestments: Entscheidungshilfen für institutionelle Anleger
Deutscher Universitätsverlag
Quantitative Methods for Electricity Trading and Risk Management: Advanced Mathematical and Statistical Methods for Energy Finance (Finance and Capital Markets Series)
MACMILLAN

Analyse et prévision des risques dans la finance et l'assurance: Évaluation et amélioration de la gestion des risques

Scoring unter Unsicherheit: Mathematische Methoden zur Auswahl von Kreditnehmern bei unvollständigen Informationen über ihre finanzielle Situation

Bayesianische VAR-Modelle zur Prognose von Aktienrenditen: Eine theoretische und empirische Analyse des deutschen Aktienmarktes
VDM Verlag