£41.00

VDM Verlag HOW GOOD IS MERTON MODEL AT ASSESSING CREDIT RISK? EVIDENCE FROM INDIA

Price data last checked 11 day(s) ago - will refresh soon

View at Amazon

We'll watch every seller, every day. One email when your price arrives.

It has never been this cheap. We have no record of a lower price.

£41 today · cheaper than every other day in the last 3 months

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↓ Price chart
when this has been cheap or pricey
↓ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 80 days · 80 data points (no recent data)

Historical
Generating forecast…
£41.00 £38.95 £39.77 £40.59 £41.41 £42.23 £43.05 27 June 2026 16 July 2026 05 August 2026 25 August 2026 14 September 2026

Price Distribution

Price distribution over 80 days • 1 price levels

Days at Price
80 days 0 20 40 60 80 £41 Days at Price

Price Analysis

Most common price: £41 (80 days, 100.0%)

Price range: £41 - £41

Price levels: 1 different prices over 80 days

Description

This book models the default probabilities and credit spreads for select Indian firms in the Black-Scholes-Merton framework.In particular,it shows that the objective (or ?real') probability estimates are higher than the risk-neutral estimates over the sample period. However, the probability measure is found to be robust to the ?default trigger point'. The model output also compares favorably with the default rate reported by CRISIL's Average 1-year rating transitions as well as the Altman Z-score measure. However it does not generate spreads as high as those observed in the corporate bond market. Perhaps not surprisingly, this is consistent with the received literature on credit spreads. This book is meant for Credit Analysts and Officers of the Credit Risk Management Department of banks and financial institutions who are concerned with designing and developing internal credit rating models, pricing models and credit portfolio models as well as students of Finanace and those teaching Risk Management.

Product Specifications

Format
paperback
Domain
Amazon UK
Release Date
12 January 2011
Listed Since
13 January 2011

Barcode

No barcode data available

Similar Products You Might Like
Credit Risk Valuation: Methods, Models, and Applications (Springer Finance)
82% match

Credit Risk Valuation: Methods, Models, and Applications (Springer Finance)

Springer
£121.52 17 Aug 2026
A Critical Study of Credit Risk Management of Investment Banks
81% match

A Critical Study of Credit Risk Management of Investment Banks

LAP Lambert Academic Publishing
£56.00 31 Aug 2026
Credit Ratings: Methodologies, Rationale and Default Risk
80% match

Credit Ratings: Methodologies, Rationale and Default Risk

Risk Books
£145.00 04 Aug 2026
Retail Credit Risk Management (Palgrave Macmillan Studies in Banking and Financial Institutions)
80% match

Retail Credit Risk Management (Palgrave Macmillan Studies in Banking and Financial Institutions)

MACMILLAN

£118.12 04 Aug 2026
Planung von künftigen Cashflows bei Kreditinstituten: Bewertung und wirtschaftliche Steuerung von Kreditinstituten
80% match

Planung von künftigen Cashflows bei Kreditinstituten: Bewertung und wirtschaftliche Steuerung von Kreditinstituten

VDM Verlag
£43.00 26 Aug 2026
The Oxford Handbook of Credit Derivatives (Oxford Handbooks in Finance)
79% match

The Oxford Handbook of Credit Derivatives (Oxford Handbooks in Finance)

Oxford University Press
£35.65 31 Aug 2026
Artificial Intelligence and Credit Risk: The Use of Alternative Data and Methods in Internal Credit Rating
79% match

Artificial Intelligence and Credit Risk: The Use of Alternative Data and Methods in Internal Credit Rating

MACMILLAN

£37.88 08 Aug 2026
Trading Risk: The Contractual Nature of Derivative Instruments and Certain Regulatory Issues
79% match

Trading Risk: The Contractual Nature of Derivative Instruments and Certain Regulatory Issues

VDM Verlag
£69.00 28 Aug 2026
Credit Risk Measurement: New Approaches to Value at Risk and Other Paradigms (Wiley Finance)
79% match

Credit Risk Measurement: New Approaches to Value at Risk and Other Paradigms (Wiley Finance)

Wiley

Price unavailable
Big Bang am Markt für Credit Default Swaps: Der Weg zu einem zentralen Kontrahenten - Ursachen, Maßnahmen und Auswirkungen
79% match

Big Bang am Markt für Credit Default Swaps: Der Weg zu einem zentralen Kontrahenten - Ursachen, Maßnahmen und Auswirkungen

VDM Verlag

£44.00 26 Aug 2026
Capital Market & Rating Agencies in Asia: Structuring a Credit Risk Rating Model (Asian Economic and Political Issues)
79% match

Capital Market & Rating Agencies in Asia: Structuring a Credit Risk Rating Model (Asian Economic and Political Issues)

£133.99 11 Sep 2026
Machine Learning for Credit Risk with Python: A Practical Guide to Default Prediction, Credit Scoring, Model Explainability, and Portfolio Risk Analysis
79% match

Machine Learning for Credit Risk with Python: A Practical Guide to Default Prediction, Credit Scoring, Model Explainability, and Portfolio Risk Analysis

£40.99 17 Sep 2026
Advances in Credit Risk Modelling and Corporate Bankruptcy Prediction (Quantitative Methods for Applied Economics and Business Research)
79% match

Advances in Credit Risk Modelling and Corporate Bankruptcy Prediction (Quantitative Methods for Applied Economics and Business Research)

Cambridge University Press
£60.80 14 Sep 2026
Credit Risk Management
79% match

Credit Risk Management

LAP Lambert Academic Publishing
£41.00 14 Sep 2026
Credit Correlation: Life After Copulas
78% match

Credit Correlation: Life After Copulas

World Scientific Publishing Company
£76.00 15 Sep 2026
Pricing Export Credit: A Concise Framework with Examples and Implementation Code in R (Management for Professionals)
78% match

Pricing Export Credit: A Concise Framework with Examples and Implementation Code in R (Management for Professionals)

Springer
£44.80 19 Aug 2026
Market Risk and Financial Markets Modeling
78% match

Market Risk and Financial Markets Modeling

Springer
£100.11 10 Aug 2026
Bank Management and Control: Strategy, Pricing, Capital and Risk Management (Management for Professionals)
78% match

Bank Management and Control: Strategy, Pricing, Capital and Risk Management (Management for Professionals)

Springer
£32.83 08 Aug 2026
The Basel II Risk Parameters: Estimation, Validation, Stress Testing - with Applications to Loan Risk Management
78% match

The Basel II Risk Parameters: Estimation, Validation, Stress Testing - with Applications to Loan Risk Management

Springer
£85.83 02 Aug 2026
Basel III Credit Rating Systems: An Applied Guide to Quantitative and Qualitative Models (Finance and Capital Markets Series)
78% match

Basel III Credit Rating Systems: An Applied Guide to Quantitative and Qualitative Models (Finance and Capital Markets Series)

MACMILLAN
£171.07 13 Aug 2026
Managing Risks in Commercial and Retail Banking (Wiley Finance)
78% match

Managing Risks in Commercial and Retail Banking (Wiley Finance)

Wiley
£98.99 18 Aug 2026
Efficient Methods for Valuing Interest Rate Derivatives (Springer Finance)
78% match

Efficient Methods for Valuing Interest Rate Derivatives (Springer Finance)

Springer
£92.22 06 Aug 2026
Fixed Income Modelling
78% match

Fixed Income Modelling

Oxford University Press
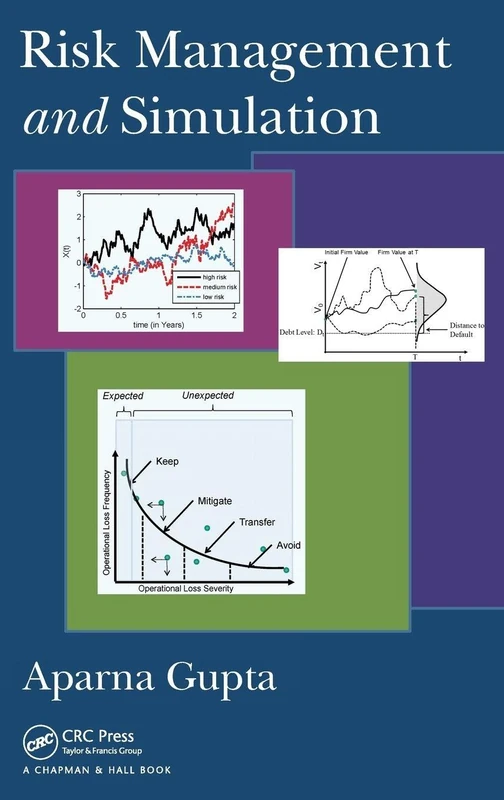
£51.51 06 Aug 2026
Risk Management and Simulation
78% match

Risk Management and Simulation

CRC Press

£182.93 08 Aug 2026