We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£85.83
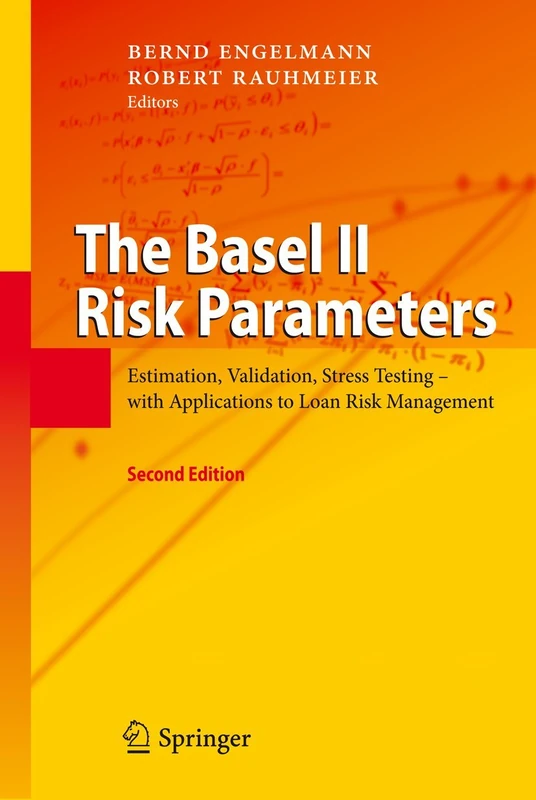
Springer The Basel II Risk Parameters: Estimation, Validation, Stress Testing - with Applications to Loan Risk Management
Price data last checked 53 day(s) ago - refreshing...
We'll watch every seller, every day. One email when your price arrives.
It has never been this cheap. We have no record of a lower price.
£86 today · cheaper than every other day in the last 3 months
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 38 days · 38 data points (no recent data)
Price Distribution
Price distribution over 38 days • 1 price levels
Price Analysis
Most common price: £86 (38 days, 100.0%)
Price range: £86 - £86
Price levels: 1 different prices over 38 days
Description
Product Specifications
- Brand
- Springer
- Format
- hardcover
- ASIN
- 3642161138
- Domain
- Amazon UK
- Release Date
- 18 April 2011
- Listed Since
- 23 September 2010
Barcode
No barcode data available
Similar Products You Might Like
Bank Management and Control: Strategy, Pricing, Capital and Risk Management (Management for Professionals)
Springer
Managing Illiquid Assets: Perspectives and Challenges
Risk Books
Basel III Credit Rating Systems: An Applied Guide to Quantitative and Qualitative Models (Finance and Capital Markets Series)
MACMILLAN
Scenario Analysis in Risk Management: Theory and Practice in Finance
Springer
Credit Ratings: Methodologies, Rationale and Default Risk
Risk Books
Advances in Operational Risk: Firm-wide Issues for Financial Institutions
Risk Books
Value-Oriented Risk Management of Insurance Companies (EAA Series)
Springer
Pricing Export Credit: A Concise Framework with Examples and Implementation Code in R (Management for Professionals)
Springer
Liquidity Risk, Efficiency and New Bank Business Models (Palgrave Macmillan Studies in Banking and Financial Institutions)
MACMILLAN
Financial Risk Management: Applications in Market, Credit, Asset and Liability Management and Firmwide Risk (Wiley Finance)
Wiley
Modern Actuarial Risk Theory: Using R
Springer
Risk Management and Regulation in Banking: Proceedings of the International Conference on Risk Management and Regulation in Banking (1997)
Springer
Wiley Risk Management in Banking - 4th Edition Guide
Wiley
Statistics and Data Analysis for Financial Engineering (Springer Texts in Statistics)
Springer
Basel III and Beyond
Risk Books
Risk Management for Engineering Projects: Procedures, Methods and Tools
Springer
Financial Risk and Derivatives: A Special Issue of the Geneva Papers on Risk and Insurance Theory
Springer
Risk Measures and Insurance Solvency Benchmarks: Fixed-Probability Levels in Renewal Risk Models (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
The Credit Risk of Complex Derivatives (Finance and Capital Markets Series)
MACMILLAN
Treatises on Solvency II: 2
Springer
Artificial Intelligence and Credit Risk: The Use of Alternative Data and Methods in Internal Credit Rating
MACMILLAN
Asset and Liability Management: A Synthesis of New Methodologies
Risk Books
Mathematical Risk Analysis: Dependence, Risk Bounds, Optimal Allocations and Portfolios (Springer Series in Operations Research and Financial Engineering)
Springer
Fixed Income Analytics: Bonds in High and Low Interest Rate Environments
Springer