£36.62

It has never been this cheap. We have no record of a lower price.

£37 today · cheaper than every other day in the last 3 months

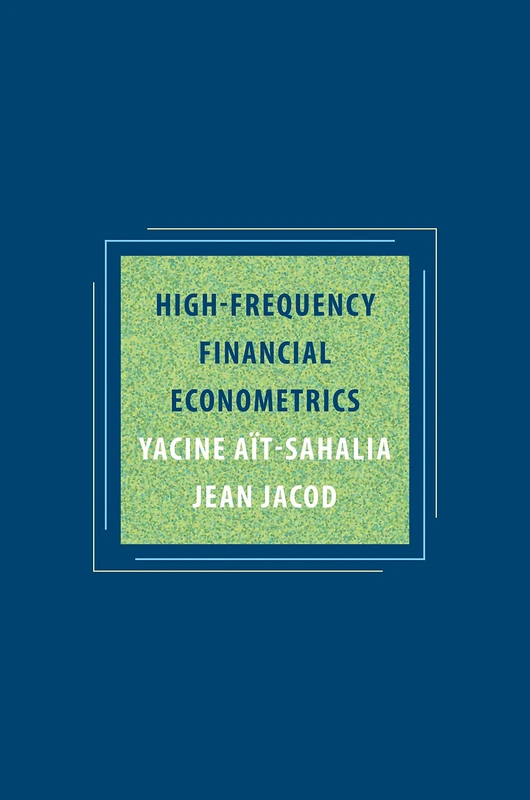
Princeton University Press High-Frequency Financial Econometrics

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 63 days · 63 data points (no recent data)

Historical
Generating forecast…
£43.18 £35.96 £37.54 £39.11 £40.69 £42.26 £43.84 26 July 2026 10 August 2026 26 August 2026 10 September 2026 26 September 2026
View at Amazon ↗

Price data last checked 28 day(s) ago - will refresh soon

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 63 days • 2 price levels

Days at Price
Current Price
58 days · current 5 days 0 15 29 44 58 £37 £43 Days at Price

Price Analysis

Most common price: £37 (58 days, 92.1%)

Price range: £37 - £43

Price levels: 2 different prices over 63 days

Description

A comprehensive introduction to the statistical and econometric methods for analyzing high-frequency financial data High-frequency trading is an algorithm-based computerized trading practice that allows firms to trade stocks in milliseconds. Over the last fifteen years, the use of statistical and econometric methods for analyzing high-frequency financial data has grown exponentially. This growth has been driven by the increasing availability of such data, the technological advancements that make high-frequency trading strategies possible, and the need of practitioners to analyze these data. This comprehensive book introduces readers to these emerging methods and tools of analysis. Yacine Aït-Sahalia and Jean Jacod cover the mathematical foundations of stochastic processes, describe the primary characteristics of high-frequency financial data, and present the asymptotic concepts that their analysis relies on. Aït-Sahalia and Jacod also deal with estimation of the volatility portion of the model, including methods that are robust to market microstructure noise, and address estimation and testing questions involving the jump part of the model. As they demonstrate, the practical importance and relevance of jumps in financial data are universally recognized, but only recently have econometric methods become available to rigorously analyze jump processes. Aït-Sahalia and Jacod approach high-frequency econometrics with a distinct focus on the financial side of matters while maintaining technical rigor, which makes this book invaluable to researchers and practitioners alike.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
21 July 2014
Listed Since
20 October 2013

Barcode

No barcode data available

Similar Products You Might Like
Econometrics of Financial High-Frequency Data
97% match

Econometrics of Financial High-Frequency Data

Springer
£128.11 03 Oct 2026
High Frequency Trading and Limit Order Book Dynamics
97% match

High Frequency Trading and Limit Order Book Dynamics

Routledge
£41.99 23 Sep 2026
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
96% match

Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)

Springer
£94.74 24 Sep 2026
MIT Press - The Economics of Continuous-Time Finance Book
96% match

MIT Press - The Economics of Continuous-Time Finance Book

MIT Press
£44.21 23 Oct 2026
High-Frequency Trading and Order Book Dynamics (The Artificial Edge: Quantitative Trading Strategies with Python)
96% match

High-Frequency Trading and Order Book Dynamics (The Artificial Edge: Quantitative Trading Strategies with Python)

£54.58 24 Jun 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
96% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£49.93 28 Aug 2026
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
96% match

Analytically Tractable Stochastic Stock Price Models (Springer Finance)

Springer
£43.32 04 Sep 2026
Pathwise Estimation and Inference for Diffusion Market Models
96% match

Pathwise Estimation and Inference for Diffusion Market Models

CRC Press
£138.44 19 Sep 2026
Statistics for Finance: Texts in Statistical Science (Chapman & Hall/CRC Texts in Statistical Science)
96% match

Statistics for Finance: Texts in Statistical Science (Chapman & Hall/CRC Texts in Statistical Science)

CRC Press
£51.99 12 Sep 2026
Arbitrage, market microstructure and the limit order book: Arbitrage opportunities in diverse markets, market microstructure aspects and a model of the limit order book
96% match

Arbitrage, market microstructure and the limit order book: Arbitrage opportunities in diverse markets, market microstructure aspects and a model of the limit order book

Südwestdeutscher Verlag für Hochschulschriften
£77.00 18 Sep 2026
Cambridge Algorithmic and High-Frequency Trading Textbook
96% match

Cambridge Algorithmic and High-Frequency Trading Textbook

Cambridge University Press
£46.79 21 Oct 2026
Time Series Models: In Econometrics, Finance And Other Fields (Chapman & Hall/Crc Monographs On Statistics & Applied Probability): 65
96% match

Time Series Models: In Econometrics, Finance And Other Fields (Chapman & Hall/Crc Monographs On Statistics & Applied Probability): 65

Chapman and Hall/CRC
£93.00 24 Sep 2026
The Science of Algorithmic Trading and Portfolio Management: Applications Using Advanced Statistics, Optimization, and Machine Learning Techniques
96% match

The Science of Algorithmic Trading and Portfolio Management: Applications Using Advanced Statistics, Optimization, and Machine Learning Techniques

Elsevier
£42.99 10 Sep 2026
Stochastic Volatility and Realized Stochastic Volatility Models (SpringerBriefs in Statistics)
96% match

Stochastic Volatility and Realized Stochastic Volatility Models (SpringerBriefs in Statistics)

Springer
£40.73 22 Sep 2026
Mathematical Finance: Core Theory, Problems and Statistical Algorithms (Routledge Advanced Texts in Economics and Finance)
96% match

Mathematical Finance: Core Theory, Problems and Statistical Algorithms (Routledge Advanced Texts in Economics and Finance)

Routledge

£62.60 25 Sep 2026