We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£128.11
This is the most expensive it has ever been. Walk away.
£128 today · previous high £128 · all-time low £120
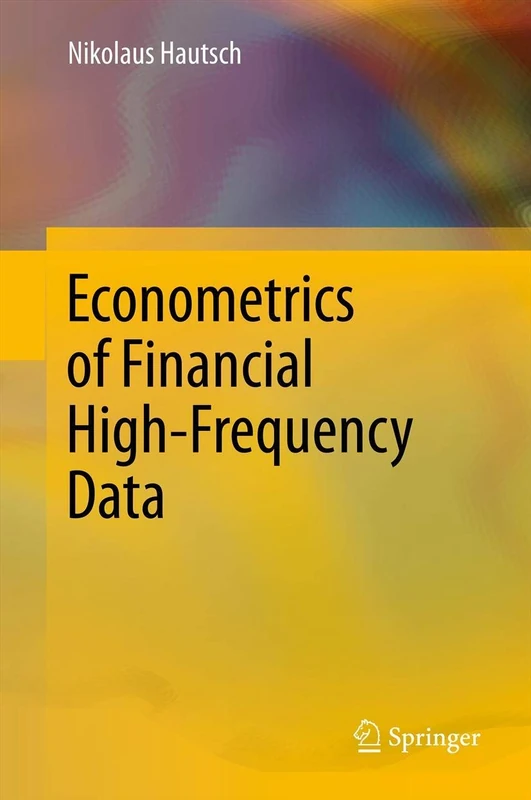
Springer Econometrics of Financial High-Frequency Data
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 68 days · 68 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 68 days • 2 price levels
Price Analysis
Most common price: £128 (66 days, 97.1%)
Price range: £120 - £128
Price levels: 2 different prices over 68 days
Description
Product Specifications
- Brand
- Springer
- Format
- paperback
- ASIN
- 3642427723
- Domain
- Amazon UK
- Publication Date
- 29 November 2013
- Listed Since
- 07 November 2013
Barcode
No barcode data available
Similar Products You Might Like
Wiley Handbook of Modeling High-Frequency Data in Finance
Wiley
The Basics of Financial Econometrics: Tools, Concepts, and Asset Management Applications: 206 (Frank J. Fabozzi Series)
Wiley
Nonlinear Economic Dynamics and Financial Modelling: Essays in Honour of Carl Chiarella
Springer
Data Science for Financial Econometrics: 898 (Studies in Computational Intelligence, 898)
Springer
Handbook of Financial Econometrics: Applications (Volume 2) (Handbooks in Finance, Volume 2)
Elsevier