£36.08

This is the most expensive it has ever been. Walk away.

£36 today · previous high £36 · all-time low £36

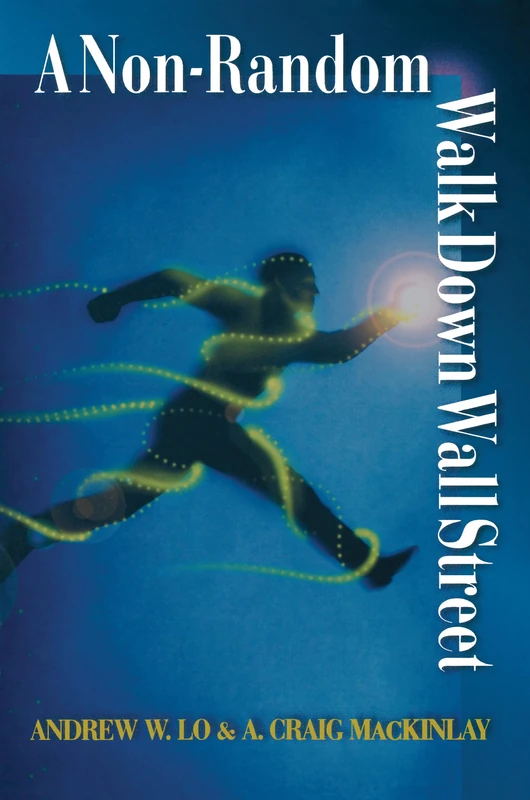
Princeton University Press A Non-Random Walk Down Wall Street

Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 62 days · 62 data points (no recent data)

Historical
Generating forecast…
£36.08 £36.06 £36.06 £36.07 £36.07 £36.08 £36.08 25 July 2026 09 August 2026 24 August 2026 08 September 2026 24 September 2026
View at Amazon ↗

Blue

Price data last checked 29 day(s) ago - will refresh soon

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 62 days • 1 price levels

Days at Price
62 days 0 16 31 47 62 £36 Days at Price

Price Analysis

Most common price: £36 (62 days, 100.0%)

Price range: £36 - £36

Price levels: 1 different prices over 62 days

Description

For over half a century, financial experts have regarded the movements of markets as a random walk--unpredictable meanderings akin to a drunkard's unsteady gait--and this hypothesis has become a cornerstone of modern financial economics and many investment strategies. Here Andrew W. Lo and A. Craig MacKinlay put the Random Walk Hypothesis to the test. In this volume, which elegantly integrates their most important articles, Lo and MacKinlay find that markets are not completely random after all, and that predictable components do exist in recent stock and bond returns. Their book provides a state-of-the-art account of the techniques for detecting predictabilities and evaluating their statistical and economic significance, and offers a tantalizing glimpse into the financial technologies of the future. The articles track the exciting course of Lo and MacKinlay's research on the predictability of stock prices from their early work on rejecting random walks in short-horizon returns to their analysis of long-term memory in stock market prices. A particular highlight is their now-famous inquiry into the pitfalls of "data-snooping biases" that have arisen from the widespread use of the same historical databases for discovering anomalies and developing seemingly profitable investment strategies. This book invites scholars to reconsider the Random Walk Hypothesis, and, by carefully documenting the presence of predictable components in the stock market, also directs investment professionals toward superior long-term investment returns through disciplined active investment management.

Product Specifications

Colour
Blue
Format
paperback
Domain
Amazon UK
Release Date
15 January 2002
Listed Since
13 February 2007

Barcode

No barcode data available

Similar Products You Might Like
Security Market Imperfections in Worldwide Equity Markets
96% match

Security Market Imperfections in Worldwide Equity Markets

Cambridge University Press
£148.77 20 Oct 2026
Princeton University Press - Asset Price Dynamics Book
96% match

Princeton University Press - Asset Price Dynamics Book

Princeton University Press
£50.86 20 Aug 2026
Statistical Analysis of Financial Data: With Examples In R (Chapman & Hall/CRC Texts in Statistical Science)
96% match

Statistical Analysis of Financial Data: With Examples In R (Chapman & Hall/CRC Texts in Statistical Science)

CRC Press
£100.00 23 Aug 2026
Deep Learning Tools for Predicting Stock Market Movements
96% match

Deep Learning Tools for Predicting Stock Market Movements

Wiley
£172.65 25 Sep 2026
Machine Learning for Factor Investing - R Version Book
96% match

Machine Learning for Factor Investing - R Version Book

CRC Press
£115.00 17 Oct 2026
Statistical Analysis of Financial Data: With Examples In R (Chapman & Hall/CRC Texts in Statistical Science)
96% match

Statistical Analysis of Financial Data: With Examples In R (Chapman & Hall/CRC Texts in Statistical Science)

CRC Press
£43.99 04 Oct 2026
A Random Walk To Nowhere: How The Professors Caused A Real ""Fraud-On-The-Market: How the Professors Caused a Real "Fraud-On-The-Market"
96% match

A Random Walk To Nowhere: How The Professors Caused A Real ""Fraud-On-The-Market: How the Professors Caused a Real "Fraud-On-The-Market"

Scientific Publishing
£55.00 02 Oct 2026
Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)
96% match

Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£74.45 25 Sep 2026
Machine Learning and AI in Finance
96% match

Machine Learning and AI in Finance

Routledge
£139.13 11 Aug 2026
Analysis Of The Korean Stock Market: Behavioral Finance Approaches
96% match

Analysis Of The Korean Stock Market: Behavioral Finance Approaches

World Scientific Publishing Company
£62.61 23 Sep 2026
The Efficiency of China's Stock Market
96% match

The Efficiency of China's Stock Market

Routledge
£151.26 05 Oct 2026
Stock Markets, Investments And Corporate Behavior: A Conceptual Framework Of Understanding
96% match

Stock Markets, Investments And Corporate Behavior: A Conceptual Framework Of Understanding

Imperial College Press
£74.68 20 Sep 2026
Pathwise Estimation and Inference for Diffusion Market Models
96% match

Pathwise Estimation and Inference for Diffusion Market Models

CRC Press
£138.44 19 Sep 2026
Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R
96% match

Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R

Wiley
£101.39 20 Oct 2026
Econophysics of Stock and other Markets: Proceedings of the Econophys-Kolkata II (New Economic Windows)
96% match

Econophysics of Stock and other Markets: Proceedings of the Econophys-Kolkata II (New Economic Windows)

Springer
£80.67 18 Sep 2026
Machine Learning for Factor Investing: Python Version (Chapman and Hall/CRC Financial Mathematics Series)
96% match

Machine Learning for Factor Investing: Python Version (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£184.65 08 Oct 2026
Ce qui marche à Wall Street: Le guide des stratégies d'investissement les plus performantes de tous les temps
96% match

Ce qui marche à Wall Street: Le guide des stratégies d'investissement les plus performantes de tous les temps

VALOR EDITIONS
£42.39 07 Oct 2026
Rapidly Changing Securities Markets: Who Are the Initiators? (Zicklin School of Business Financial Markets Series)
96% match

Rapidly Changing Securities Markets: Who Are the Initiators? (Zicklin School of Business Financial Markets Series)

Springer
£81.54 24 Sep 2026
Wiley An Introduction to Analysis of Financial Data with R
96% match

Wiley An Introduction to Analysis of Financial Data with R

Wiley
£77.10 22 Oct 2026
Online Portfolio Selection: Principles and Algorithms
95% match

Online Portfolio Selection: Principles and Algorithms

CRC Press
£52.24 06 Aug 2026
Day Trade With AI: Theoretical foundations for discretionary, algorithmic, and diversified trading with AI
95% match

Day Trade With AI: Theoretical foundations for discretionary, algorithmic, and diversified trading with AI

£44.17 10 Sep 2026
The Econometrics of Financial Markets
95% match

The Econometrics of Financial Markets

Princeton University Press
£49.30 14 Aug 2026
Risk and Return in Transportation and Other US and Global Industries
95% match

Risk and Return in Transportation and Other US and Global Industries

Springer
£39.54 08 Sep 2026
Asset Pricing under Asymmetric Information: Bubbles, Crashes, Technical Analysis, and Herding
95% match

Asset Pricing under Asymmetric Information: Bubbles, Crashes, Technical Analysis, and Herding

Oxford University Press

£109.91 11 Sep 2026