We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£127.94
This is the most expensive it has ever been. Walk away.
£128 today · previous high £128 · all-time low £125
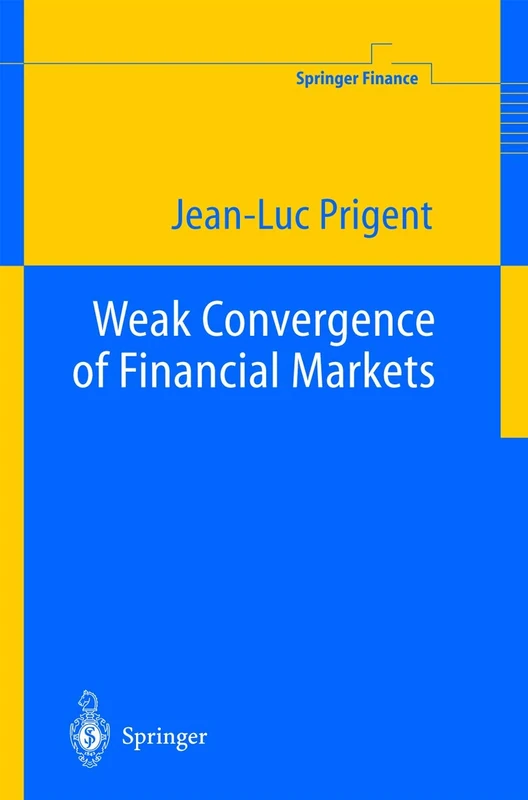
Springer Weak Convergence of Financial Markets - Springer Finance
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 59 days · 59 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 59 days • 3 price levels
Price Analysis
Most common price: £125 (33 days, 55.9%)
Price range: £125 - £128
Price levels: 3 different prices over 59 days
Description
Key Features
The book covers stochastic processes and stochastic calculus foundations with emphasis on contiguity properties and weak convergence theory.
Portfolio optimisation, option pricing and hedging strategies are examined using weak convergence analysis of financial markets.
Discrete-time approximations of continuous-time dynamics are analysed to bridge theoretical models with practical trading applications.
8 figures and 1 table support the mathematical concepts and financial theory throughout the Weak Convergence of Financial Markets text.
Product Specifications
- Brand
- Springer
- Format
- hardcover
- ASIN
- 3540423338
- Domain
- Amazon UK
- Release Date
- 19 May 2003
- Listed Since
- 12 January 2007
Barcode
No barcode data available
Similar Products You Might Like
Weak Convergence of Financial Markets - Springer Finance
Springer
Springer Stochastic Calculus for Finance II - Math Textbook
Springer
Springer Mathematical Methods for Financial Markets Book
Springer
Stochastic Calculus for Quantitative Finance: Stochastic Calculus for Finance
Elsevier
Springer Derivative Security Pricing - Stochastic Finance Book
Springer
Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)
Springer
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Continuous Stochastic Calculus with Applications to Finance: 17 (Applied Mathematics)
Chapman and Hall/CRC
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Arbitrage Theory In Discrete And Continuous Time
World Scientific Publishing Company
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
Continuous Stochastic Calculus with Applications to Finance
CRC Press
Mathematical Methods and Quantum Mathematics for Economics and Finance
Springer
DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE
World Scientific Publishing Company
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
Springer
Mathematical Methods and Quantum Mathematics for Economics and Finance
Springer
Mathematical Finance (Springer Finance)
Springer
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
Contract Theory in Continuous-Time Models: 0 (Springer Finance)
Springer
Stochastic Calculus for Finance I: The Binomial Asset Pricing Model (Springer Finance)
Springer
Control Engineering and Finance: 467 (Lecture Notes in Control and Information Sciences, 467)
Springer
Springer Stochastic Calculus for Finance I - Binomial Model
Springer
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Continuous-time Stochastic Control and Optimization with Financial Applications: 61 (Stochastic Modelling and Applied Probability, 61)
Springer