We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£92.63
It has never been this cheap. We have no record of a lower price.
£93 today · cheaper than every other day in the last 3 months
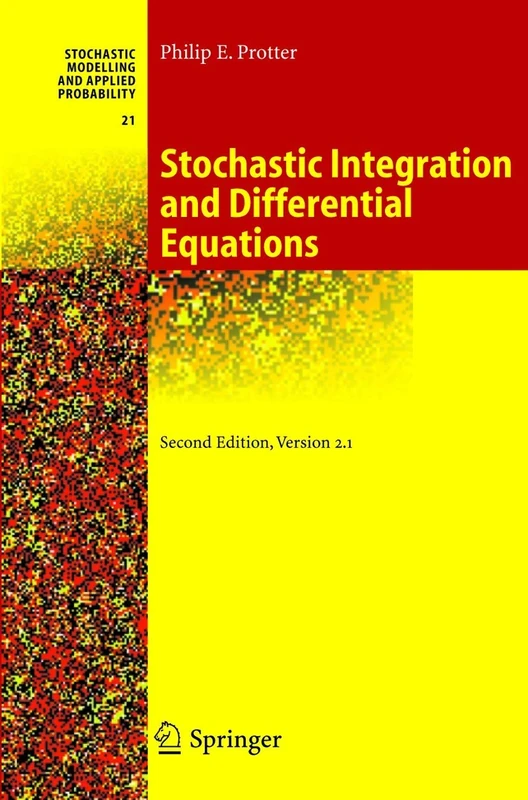
Springer Stochastic Integration and Differential Equations 2nd Ed
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 29 days · 29 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 29 days • 1 price levels
Price Analysis
Most common price: £93 (29 days, 100.0%)
Price range: £93 - £93
Price levels: 1 different prices over 29 days
Description
Key Features
This Springer publication is a second edition of the Stochastic Integration and Differential Equations text.
The book uses a functional analytic method for presenting semimartingales and stochastic integration.
Each copy is provided in new, mint condition to ensure the highest quality for your studies.
Orders received before 12 noon are dispatched the same day for fast delivery.
We provide guaranteed packaging to protect your book during transit.
Enjoy peace of mind with our no quibbles returns policy.
Product Specifications
- Brand
- Springer
- Format
- hardcover
- ASIN
- 3540003134
- Domain
- Amazon UK
- Release Date
- 07 October 2003
- Listed Since
- 22 January 2007
Barcode
No barcode data available
Similar Products You Might Like
Stochastic Integration and Differential Equations: Version 2.1 (Stochastic Modelling and Applied Probability, 21)
Springer
Martingales and Financial Mathematics in Discrete Time - Wiley
Wiley
Limit Theorems for Stochastic Processes - Springer Mathematics
Springer
Statistics of Random Processes: I. General Theory: 5 (Stochastic Modelling and Applied Probability, 5)
Springer
Statistics of Random Processes II: Applications: 6 (Stochastic Modelling and Applied Probability, 6)
Springer
Statistics of Random Processes II: Applications: 6 (Stochastic Modelling and Applied Probability, 6)
Springer
Stochastic Analysis: 3 (Monographs in Mathematical Economics, 3)
Springer
Set-Indexed Martingales: Chapman & Hall Monograph 85
Routledge
Limit Theorems for Stochastic Processes: 288 (Grundlehren der mathematischen Wissenschaften, 288)
Springer
Martingale Methods in Statistics: 1 (Chapman & Hall/CRC Monographs on Statistics and Applied Probability)
CRC Press
Mathematics of Financial Markets (Springer Finance)
Springer
The Splendors and Miseries of Martingales: Their History from the Casino to Mathematics (Trends in the History of Science)
Birkhauser
Fractional Brownian Motion: Approximations and Projections (Mathematics and Statistics)
Wiley
Martingale Methods in Statistics: 1 (Chapman & Hall/CRC Monographs on Statistics and Applied Probability)
Chapman and Hall/CRC
Stochastic Analysis and Diffusion Processes (Oxford Graduate Texts in Mathematics): 24
Oxford University Press
Optimal Stopping and Free-Boundary Problems (Lectures in Mathematics. ETH Zürich)
Birkhauser
Probability and Random Processes with One Thousand Exercises in Probability
Oxford University Press
Options Pricing and Portfolio Optimization: Modern Methods of Financial Mathematics (Graduate Studies in Mathematics)
Brand: Amer Mathematical Society
Stochastic Calculus in Infinite Dimensions and SPDEs (SpringerBriefs in Mathematics)
Springer
Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)
Springer
Continuous Stochastic Calculus with Applications to Finance
CRC Press
Stochastic Calculus for Fractional Brownian Motion and Applications (Probability and Its Applications)
Springer
Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach
Wiley
Continuous Stochastic Calculus with Applications to Finance: 17 (Applied Mathematics)
Chapman and Hall/CRC