We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£47.41
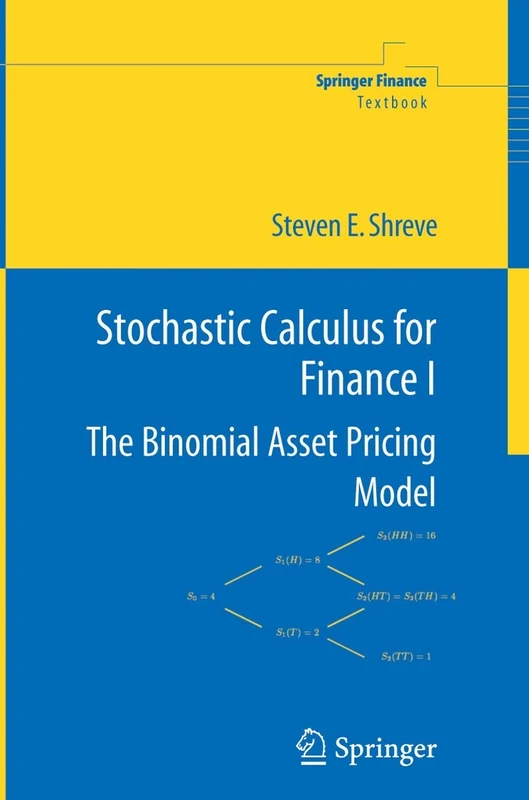
Springer Stochastic Calculus for Finance I - Binomial Model
Price data last checked 47 day(s) ago - refreshing...
We'll watch every seller, every day. One email when your price arrives.
About as cheap as it gets. The only time it was cheaper was 3 months ago.
£47 today · all-time low £47 (Jul 2026) · usually the usual
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 44 days · 44 data points (no recent data)
Price Distribution
Price distribution over 44 days • 5 price levels
Price Analysis
Most common price: £47 (33 days, 75.0%)
Price range: £47 - £54
Price levels: 5 different prices over 44 days
Description
Key Features
Developed from the Carnegie Mellon Professional Master's program in Computational Finance to ensure academic rigor.
Designed for students with a mathematics background in calculus and calculus-based probability.
Provides intuitive explanations refined through extensive classroom experience with this material.
Includes a self-contained treatment of the probability theory required for the subject matter.
Offers precise statements of results along with plausibility arguments and proofs for deep understanding.
Published by Springer as part of the professional finance series for serious students and practitioners.
Product Specifications
- Brand
- Springer
- Format
- paperback
- ASIN
- 0387249680
- Domain
- Amazon UK
- Publication Date
- 28 June 2005
- Listed Since
- 12 February 2007
Barcode
No barcode data available
Similar Products You Might Like
Stochastic Calculus for Finance I: The Binomial Asset Pricing Model (Springer Finance)
Springer
Springer Stochastic Calculus for Finance II - Math Textbook
Springer
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Options Pricing and Portfolio Optimization: Modern Methods of Financial Mathematics (Graduate Studies in Mathematics)
Brand: Amer Mathematical Society
Arbitrage Theory In Discrete And Continuous Time
World Scientific Publishing Company
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)
Springer
Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)
Springer
Stochastic Calculus for Quantitative Finance: Stochastic Calculus for Finance
Elsevier
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
Mathematical Finance: Core Theory, Problems and Statistical Algorithms (Routledge Advanced Texts in Economics and Finance)
Routledge
Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach
Wiley
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
Springer
DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE
World Scientific Publishing Company
Mathematical Finance: Core Theory, Problems and Statistical Algorithms (Routledge Advanced Texts in Economics and Finance)
Routledge
Continuous Stochastic Calculus with Applications to Finance: 17 (Applied Mathematics)
Chapman and Hall/CRC
Stochastic Finance: A Numeraire Approach (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Problems and Solutions in Mathematical Finance, Volume 1: Stochastic Calculus (The Wiley Finance Series)
Wiley
Stochastic Finance with Python: Design Financial Models from Probabilistic Perspective
Apress
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
Springer
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)
Springer
A Course in Financial Calculus
Cambridge University Press

Stochastic Finance: An Introduction with Examples
Cambridge University Press