We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£145.00
It has never been this cheap. We have no record of a lower price.
£145 today · cheaper than every other day in the last 3 months
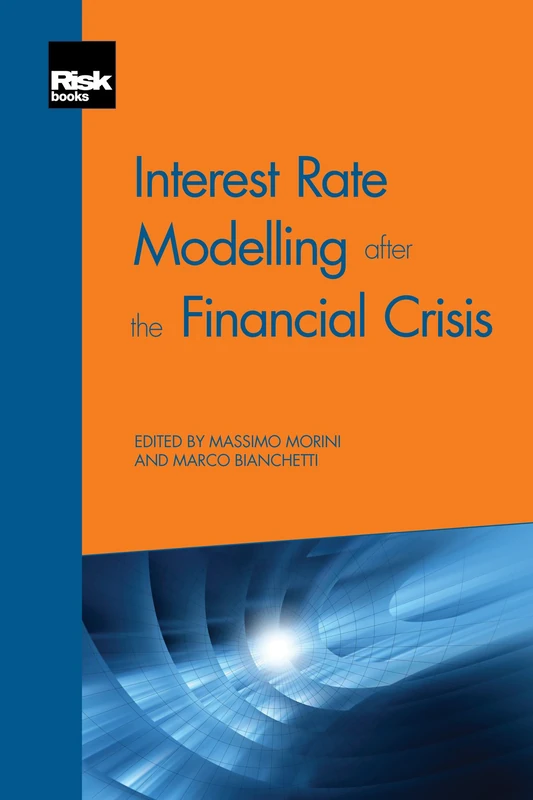
Risk Books - Interest Rate Modelling after the Financial Crisis
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 84 days · 84 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 84 days • 1 price levels
Price Analysis
Most common price: £145 (84 days, 100.0%)
Price range: £145 - £145
Price levels: 1 different prices over 84 days
Description
Key Features
This book by Risk Books addresses the shift away from risk-free interest rate market assumptions.
Explore how the financial crisis alerted market participants to previously neglected risk factors.
Learn about the important changes in market data patterns resulting from recent economic shifts.
Gain knowledge on new approaches in interest rate modelling required for the modern landscape.
Stay up-to-date with the latest practical and theoretical developments in interest rate markets.
Product Specifications
- Brand
- Risk Books
- Format
- paperback
- ASIN
- 1906348936
- Category
- Books > Subjects > Business, Finance & Law > Biographies & Histories > Business & Economic History
- Domain
- Amazon UK
- Release Date
- 06 November 2013
- Listed Since
- 19 June 2013
Barcode
No barcode data available
Similar Products You Might Like
Interest Rate Modelling in the Multi-Curve Framework: Foundations, Evolution, Transition, and Implementation (Applied Quantitative Finance)
MACMILLAN
Chapman and Hall/CRC Interest Rate Modeling - 3rd Edition
Chapman and Hall/CRC
Springer Interest Rate Models: Theory and Practice Book
Springer
Interest Rate Models - Theory and Practice: With Smile, Inflation and Credit (Springer Finance)
Springer
Fixed-Income Securities: Dynamic Methods for Interest Rate Risk Pricing and Hedging (Frontiers in Finance Series)
Wiley
Interest Rate Models: An Introduction
Princeton University Press
Atlantic Financial Press Interest Rate Modeling Vol 3
Atlantic Financial Press
Term-Structure Models: A Graduate Course (Springer Finance)
Springer
Pricing and Hedging Interest and Credit Risk Sensitive Instruments
Elsevier
Robust Libor Modelling and Pricing of Derivative Products (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Understanding Credit Derivatives and Related Instruments
Elsevier
Engineering BGM (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
MACMILLAN
Wiley Swaps and Other Derivatives - 2nd Edition Book
Wiley
Interest-Rate Management (Springer Finance)
Springer
Aitch & Dee Pricing and Trading Interest Rate Derivatives Book
Aitch & Dee Limited
Atlantic Financial Press - Interest Rate Modeling Vol 1
Atlantic Financial Press
Modelling Interest Rates: Advances in Derivatives Pricing
Risk Books
Princeton University Press - Interest-Rate Derivatives Book
Princeton University Press
Stochastic Interest Rate Modeling 3rd Edition - WSPC Book
World Scientific Publishing Company
Coding Interest Rates: FX, Swaps and Bonds - rateslib v2.0
World Scientific Derivative Securities and Risk Management Book
World Scientific Publishing Company
SABR and SABR LIBOR Market Models in Practice: With Examples Implemented in Python (Applied Quantitative Finance)
MACMILLAN
Term-Structure Models: A Graduate Course (Springer Finance)
Springer