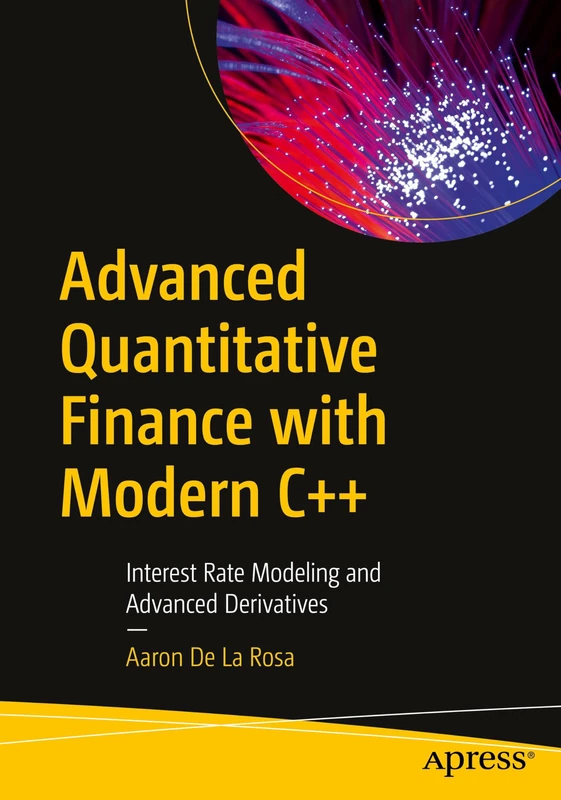
£46.85

Apress Advanced Quantitative Finance with Modern C++: Interest Rate Modeling and Advanced Derivatives

Price data last checked 37 day(s) ago - refreshing...

View at Amazon

We'll watch every seller, every day. One email when your price arrives.

It has never been this cheap. We have no record of a lower price.

£47 today · cheaper than every other day in the last 2 months

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↓ Price chart
when this has been cheap or pricey
↓ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 17 days · 17 data points (no recent data)

Historical
Generating forecast…
£46.85 £44.51 £45.44 £46.38 £47.32 £48.26 £49.19 02 August 2026 06 August 2026 10 August 2026 14 August 2026 18 August 2026

Price Distribution

Price distribution over 17 days • 1 price levels

Days at Price
17 days 0 4 9 13 17 £47 Days at Price

Price Analysis

Most common price: £47 (17 days, 100.0%)

Price range: £47 - £47

Price levels: 1 different prices over 17 days

Description

From the elegance of the Black–Scholes equation to the complexity of multi-factor interest rate models and hybrid derivatives, this book is your comprehensive guide to quantitative finance, complete with 15+ advanced C++ projects using QuantLib and Boost. You’ll move seamlessly from mathematical foundations to real-world implementation, building a professional-grade toolkit for pricing, risk analysis, and calibration. Inside, you will learn core option pricing methods, master single-and multi-factor interest rate models, and construct and calibrate trees and lattices for advanced derivatives. You will also explore cutting edge products: exotic multi-asset options, hybrid derivatives, credit instruments, and cross-currency swaps. Packed with practical source code, step-by-step calibrations, and performance-tuned Boost integration, this book bridges the gap between academic finance and production-grade quant development. Whether you’re a quant developer, financial engineer, or an advanced student, you’ll gain the skills to design, implement, and deploy derivatives pricing models ready for the trading floor. What You Will Learn Understand the mathematics behind Black–Scholes, Vasicek, Hull–White, CIR, BDT, Black–Karasinski, and other core models. Apply finite difference schemes, trinomial trees, and Monte Carlo simulations for derivative pricing. Build and value swaps, swaptions, FRAs, bonds, callable/convertible debt, and multi-curve term structures. Implement barrier, multi-asset, hybrid, and structured products in C++. Model credit default swaps, cross-currency swaps, and total return structures. Use QuantLib and Boost to create production-grade pricing engines and calibration tools. Employ Gaussian models, market models, and global optimizers for fitting market data. Integrate code into professional workflows, ensuring speed, accuracy, and maintainability. Who This Book is for: Quantitative developers, financial engineers, traders, analysts, and graduates students using C++, QuantLib, Boost, and robust tools to price, hedge, and manage risk for complex financial instruments—and for software engineers aiming to bridge theory and industry practice in quantitative finance. Optional prerequisite: Mastering Quantitative Finance with Modern C++: Foundations, Derivatives, and Computational Methods, for readers who want to build a solid foundation before tackling the advanced models and projects in this book.

Product Specifications

Brand
Apress
Format
paperback
Domain
Amazon UK
Release Date
03 January 2026
Listed Since
23 August 2025

Barcode

No barcode data available

Similar Products You Might Like

Mastering Quantitative Finance with Modern C++: Foundations, Derivatives, and Computational Methods
86% match

Mastering Quantitative Finance with Modern C++: Foundations, Derivatives, and Computational Methods

Apress

£46.74 05 Aug 2026
Derivatives: Mathematical Foundations for Finance Students
82% match

Derivatives: Mathematical Foundations for Finance Students

Routledge

£59.99 29 Jul 2026
Risk Engineering for Quant Finance: Stress Testing, Black Swan Modeling, and Tail-Risk Hedging: Build Resilient Trading Systems with Monte Carlo Stress Tests, Fat-Tail Risk Models, and Crisis-Ready
81% match

Risk Engineering for Quant Finance: Stress Testing, Black Swan Modeling, and Tail-Risk Hedging: Build Resilient Trading Systems with Monte Carlo Stress Tests, Fat-Tail Risk Models, and Crisis-Ready

£45.20 10 Aug 2026
Financial Products: An Introduction Using Mathematics and Excel
81% match

Financial Products: An Introduction Using Mathematics and Excel

Cambridge University Press
£39.04 30 Jul 2026
Tools for Computational Finance (Universitext)
81% match

Tools for Computational Finance (Universitext)

Springer

£54.36 05 Aug 2026
Mathematics Of Computational Finance
80% match

Mathematics Of Computational Finance

World Scientific Publishing Company
£96.47 12 Aug 2026
Topics in Numerical Methods for Finance: 19 (Springer Proceedings in Mathematics & Statistics, 19)
80% match

Topics in Numerical Methods for Finance: 19 (Springer Proceedings in Mathematics & Statistics, 19)

Springer

£74.76 06 Aug 2026
McGraw-Hill Option Pricing Formulas - Professional Finance Guide
80% match

McGraw-Hill Option Pricing Formulas - Professional Finance Guide

McGraw-Hill Education

£37.04 20 Sep 2026
Computational Finance with R (Indian Statistical Institute Series)
80% match

Computational Finance with R (Indian Statistical Institute Series)

Springer
£90.19 30 Jul 2026
Fixed Income Modelling
80% match

Fixed Income Modelling

Oxford University Press
£51.51 06 Aug 2026
Computational Intelligence Applications to Option Pricing, Volatility Forecasting and Value at Risk: 697 (Studies in Computational Intelligence, 697)
80% match

Computational Intelligence Applications to Option Pricing, Volatility Forecasting and Value at Risk: 697 (Studies in Computational Intelligence, 697)

Springer
£92.22 05 Aug 2026
Derivative Securities and Difference Methods (Springer Finance)
80% match

Derivative Securities and Difference Methods (Springer Finance)

Springer
£99.50 06 Aug 2026
Decision Making with Quantitative Financial Market Data: Applications, Precautions and Pitfalls (SpringerBriefs in Operations Research)
79% match

Decision Making with Quantitative Financial Market Data: Applications, Precautions and Pitfalls (SpringerBriefs in Operations Research)

Springer
£43.30 04 Aug 2026
Financial Market Analytics
79% match

Financial Market Analytics

Bloomsbury
£64.50 13 Aug 2026
Derivative Securities and Difference Methods (Springer Finance)
79% match

Derivative Securities and Difference Methods (Springer Finance)

Springer

Price unavailable
The Art of Quantitative Finance Vol.2: Volatilities, Stochastic Analysis and Valuation Tools (Springer Texts in Business and Economics)
79% match

The Art of Quantitative Finance Vol.2: Volatilities, Stochastic Analysis and Valuation Tools (Springer Texts in Business and Economics)

Springer
£119.99 07 Aug 2026
Risk Management and Simulation
79% match

Risk Management and Simulation

CRC Press

£182.93 08 Aug 2026
Developing High-Frequency Trading Systems: Learn how to implement high-frequency trading from scratch with C++ or Java basics
79% match

Developing High-Frequency Trading Systems: Learn how to implement high-frequency trading from scratch with C++ or Java basics

Packt Publishing

£40.08 08 Aug 2026
Stochastic Volatility Models: Heston, SABR, and Applications in Options Pricing: A Practical Guide to Advanced Volatility Modeling, Calibration, and Market Applications for Traders and Analysts
79% match

Stochastic Volatility Models: Heston, SABR, and Applications in Options Pricing: A Practical Guide to Advanced Volatility Modeling, Calibration, and Market Applications for Traders and Analysts

£44.41 30 Jul 2026
Derivatives
79% match

Derivatives

Cambridge University Press
£15.20 10 Aug 2026
Financial Mathematics: A Comprehensive Treatment in Continuous Time Volume II (Textbooks in Mathematics)
79% match

Financial Mathematics: A Comprehensive Treatment in Continuous Time Volume II (Textbooks in Mathematics)

CRC Press
£84.99 30 Jul 2026
Derivatives and Internal Models (Finance and Capital Markets Series)
79% match

Derivatives and Internal Models (Finance and Capital Markets Series)

MACMILLAN
£78.84 14 Aug 2026
Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)
79% match

Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)

Springer
£58.93 07 Aug 2026
An Intuitive Introduction to Finance and Derivatives: Concepts, Terminology and Models (Springer Texts in Business and Economics)
78% match

An Intuitive Introduction to Finance and Derivatives: Concepts, Terminology and Models (Springer Texts in Business and Economics)

Springer

£52.80 03 Aug 2026