We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
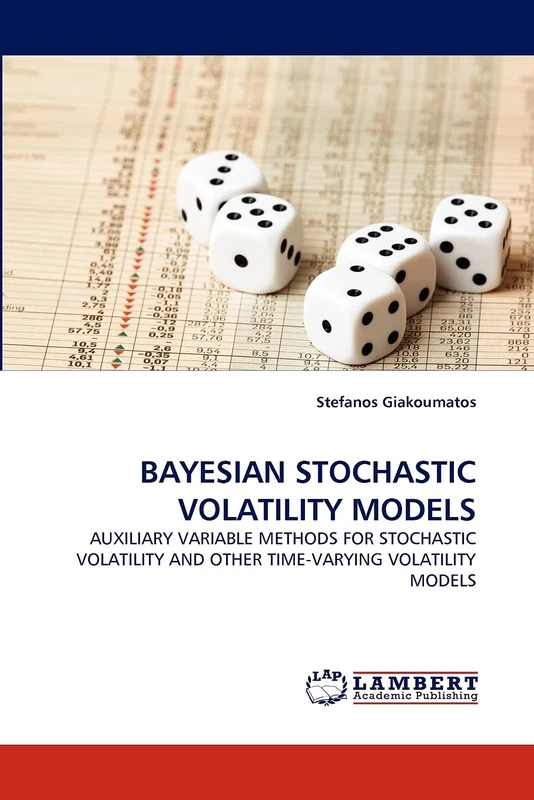
£64.99
It has never been this cheap. We have no record of a lower price.
£65 today · cheaper than every other day in the last 3 months
LAP Lambert Academic Publishing BAYESIAN STOCHASTIC VOLATILITY MODELS: AUXILIARY VARIABLE METHODS FOR STOCHASTIC VOLATILITY AND OTHER TIME-VARYING VOLATILITY MODELS
Price data last checked 41 day(s) ago - refreshing...
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 50 days · 50 data points (no recent data)
Price data last checked 41 day(s) ago - refreshing...
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 50 days • 1 price levels
Price Analysis
Most common price: £65 (50 days, 100.0%)
Price range: £65 - £65
Price levels: 1 different prices over 50 days
Description
Product Specifications
- Format
- paperback
- ASIN
- 3838386337
- Domain
- Amazon UK
- Release Date
- 26 August 2010
- Listed Since
- 31 August 2010
Barcode
No barcode data available
Similar Products You Might Like
Wiley Handbook of Volatility Models and Their Applications
Wiley
Wiley Analysis of Financial Time Series - Probability & Statistics
Wiley
Stochastic Volatility and Realized Stochastic Volatility Models (SpringerBriefs in Statistics)
Springer
Springer - Parameter Estimation in Stochastic Volatility Models
Springer
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
Springer
Statistics and Data Analysis for Financial Engineering: with R examples (Springer Texts in Statistics)
Springer
Stochastic Volatility in Financial Markets: Crossing the Bridge to Continuous Time: 3 (Dynamic Modeling and Econometrics in Economics and Finance, 3)
Springer
Forerunners of Modern Financial Economics: A Random Walk in the History of Economic Thought, 1900–1950
Edward Elgar Publishing
Springer Statistics and Data Analysis for Financial Engineering
Springer
Forecasting Volatility in the Financial Markets
Butterworth-Heinemann
Parameter Estimation in Stochastic Volatility Models
Springer
Pathwise Estimation and Inference for Diffusion Market Models
CRC Press
Forecasting Volatility in the Financial Markets (Quantitative Finance)
Elsevier
Multifractal Volatility: Theory, Forecasting, and Pricing (Academic Press Advanced Finance Series)
Elsevier
Financial Models with Levy Processes and Volatility Clustering: 187 (Frank J. Fabozzi Series)
Wiley
Time Series Models: In Econometrics, Finance And Other Fields (Chapman & Hall/Crc Monographs On Statistics & Applied Probability): 65
Chapman and Hall/CRC
Statistische Verfahren für Diffusionsprozesse mit Anwendung auf stochastische Zinsmodelle der Finanzmathematik
GRIN Verlag
Stochastic Volatility Modeling (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press
The Econometrics of Financial Markets
Princeton University Press
Dynamic Time Series Models using R-INLA: An Applied Perspective
CRC Press
Econometric Analysis of Financial and Economic Time Series: 20, Part B (Advances in Econometrics, 20, Part B)
Jai Press Inc.
Financial Risk Management with Bayesian Estimation of GARCH Models: Theory and Applications: 612 (Lecture Notes in Economics and Mathematical Systems, 612)
Springer
Risk and Asset Allocation (Springer Finance)
Springer
Princeton University Press - Asset Price Dynamics Book
Princeton University Press