We can't find the internet
Attempting to reconnect
Something went wrong
Hang in there while we get back on track
£46.57
This is the most expensive it has ever been. Walk away.
£47 today · previous high £47 · all-time low £46
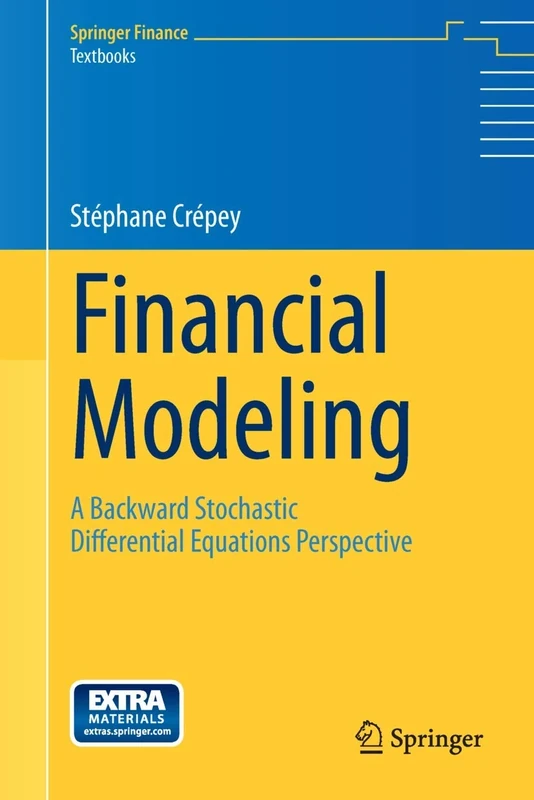
Springer Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)
We'll watch every seller, every day. One email when your price arrives.
Price History & Forecast
Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.
Last 86 days · 86 data points (no recent data)
NEW HERE?
Amazon shows you one price. We show you all of them.
Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.
WHAT'S ON THIS PAGE
when this has been cheap or pricey
where the price is heading next
all-time high & low, recent range
name your number, we'll email you
Price Distribution
Price distribution over 86 days • 1 price levels
Price Analysis
Most common price: £46 (86 days, 100.0%)
Price range: £46 - £46
Price levels: 1 different prices over 86 days
Description
Product Specifications
- Brand
- Springer
- Format
- paperback
- ASIN
- 3642442528
- Domain
- Amazon UK
- Release Date
- 10 July 2015
- Listed Since
- 09 July 2015
Barcode
No barcode data available
Similar Products You Might Like
Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)
Wiley
Oxford Arbitrage Theory in Continuous Time - 4th Edition
Oxford University Press
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
MACMILLAN
Derivative Securities and Difference Methods (Springer Finance)
Springer
A Factor Model Approach to Derivative Pricing
CRC Press
Wiley Pricing Financial Instruments: The Finite Difference Method
Wiley
Mathematical Finance: Theory, Modeling, Implementation
Wiley
Quantitative Finance: An Introduction to Investments, Asset Pricing, and Derivatives
Princeton University Press
Springer Stochastic Models for Energy and Commodity Markets
Springer
World Scientific Quantitative Analysis and Derivatives Modeling
World Scientific Publishing Company
Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-Income Market
World Scientific Publishing Company
Arbitrage Theory In Discrete And Continuous Time
World Scientific Publishing Company
Computational Methods for Quantitative Finance: Finite Element Methods for Derivative Pricing (Springer Finance)
Springer
An Arbitrage Guide to Financial Markets: 303 (The Wiley Finance Series)
Wiley
Advanced Modelling in Mathematical Finance: In Honour of Ernst Eberlein: 189 (Springer Proceedings in Mathematics & Statistics, 189)
Springer
Stochastic Processes and Financial Mathematics: 1 (Mathematics Study Resources, 1)
Springer
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
MACMILLAN
Advanced Modelling in Mathematical Finance - Springer Proceedings Vol. 189
Springer
Wiley Problems and Solutions in Mathematical Finance Vol 2
Wiley
Wiley Modern Computational Finance - AAD and Parallel Simulations
Wiley
Wiley Financial Instrument Pricing Using C++ Guide
Wiley
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
MACMILLAN
Financial Mathematics, Derivatives and Structured Products - Springer Finance
Springer
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
CRC Press