£64.00

It has never been this cheap. We have no record of a lower price.

£64 today · cheaper than every other day in the last 3 months

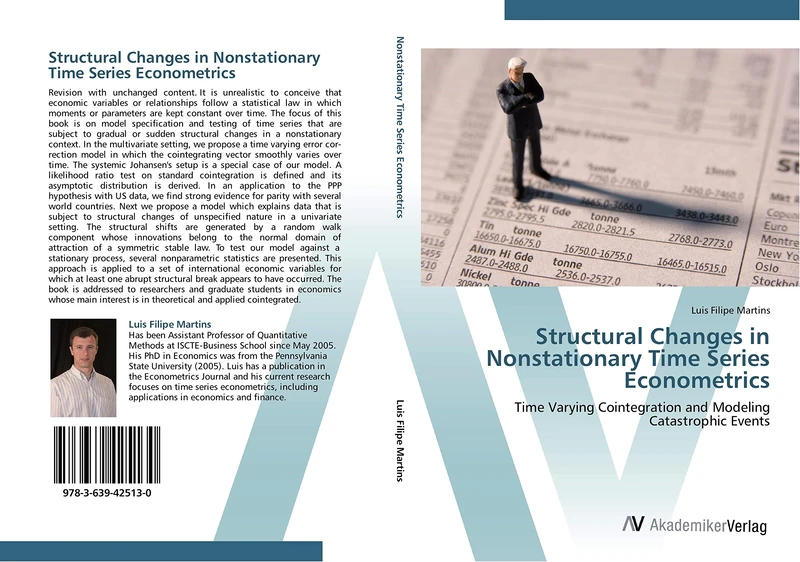
VDM Verlag Structural Changes in Nonstationary Time Series Econometrics: Time Varying Cointegration and Modeling Catastrophic Events

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 56 days · 56 data points (no recent data)

Historical
Generating forecast…
£64.00 £60.80 £62.08 £63.36 £64.64 £65.92 £67.20 25 July 2026 07 August 2026 21 August 2026 04 September 2026 18 September 2026
View at Amazon ↗

Price data last checked 35 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 56 days • 1 price levels

Days at Price
56 days 0 14 28 42 56 £64 Days at Price

Price Analysis

Most common price: £64 (56 days, 100.0%)

Price range: £64 - £64

Price levels: 1 different prices over 56 days

Description

Revision with unchanged content. It is unrealistic to conceive that economic variables or relationships follow a statistical law in which moments or parameters are kept constant over time. The focus of this book is on model specification and testing of time series that are subject to gradual or sudden structural changes in a nonstationary context. In the multivariate setting, we propose a time varying error cor-rection model in which the cointegrating vector smoothly varies over time. The systemic Johansen's setup is a special case of our model. A likelihood ratio test on standard cointegration is defined and its asymptotic distribution is derived. In an application to the PPP hypothesis with US data, we find strong evidence for parity with several world countries. Next we propose a model which explains data that is subject to structural changes of unspecified nature in a univariate setting. The structural shifts are generated by a random walk component whose innovations belong to the normal domain of attraction of a symmetric stable law. To test our model against a stationary process, several nonparametric statistics are presented. This approach is applied to a set of international economic variables for which at least one abrupt structural break appears to have occurred. The book is addressed to researchers and graduate students in economics whose main interest is in theoretical and applied cointegrated.

Product Specifications

Format
paperback
Domain
Amazon UK
Release Date
12 June 2012
Listed Since
13 June 2012

Barcode

No barcode data available

Similar Products You Might Like
Likelihood-Based Inference In Cointegrated Vector Autoregressive Models (Advanced Texts In Econometrics)
98% match

Likelihood-Based Inference In Cointegrated Vector Autoregressive Models (Advanced Texts In Econometrics)

Oxford University Press
£73.00 26 Sep 2026
COINTEGRATED VAR MODEL:METHODOL APPLICAT ATE:P PAPER: Methodology and Applications (Advanced Texts in Econometrics)
97% match

COINTEGRATED VAR MODEL:METHODOL APPLICAT ATE:P PAPER: Methodology and Applications (Advanced Texts in Econometrics)

Oxford University Press
£72.00 26 Sep 2026
Multivariate Modelling of Non-Stationary Economic Time Series (Palgrave Texts in Econometrics)
97% match

Multivariate Modelling of Non-Stationary Economic Time Series (Palgrave Texts in Econometrics)

MACMILLAN
£49.99 02 Oct 2026
Testing Exogeneity (Advanced Texts in Econometrics)
96% match

Testing Exogeneity (Advanced Texts in Econometrics)

Oxford University Press
£58.07 22 Sep 2026
Time Series, Unit Roots, and Cointegration
96% match

Time Series, Unit Roots, and Cointegration

Academic Press
£65.52 25 Sep 2026
Financial Econometrics (Routledge Advanced Texts in Economics and Finance)
96% match

Financial Econometrics (Routledge Advanced Texts in Economics and Finance)

Routledge
£167.98 24 Sep 2026
Long-Run Growth Forecasting
96% match

Long-Run Growth Forecasting

Springer

£74.48 23 Sep 2026
Money, Stock Prices and Central Banks: A Cointegrated VAR Analysis (Contributions to Economics)
96% match

Money, Stock Prices and Central Banks: A Cointegrated VAR Analysis (Contributions to Economics)

Physica
£113.58 30 Sep 2026
Cointegration for the Applied Economist
96% match

Cointegration for the Applied Economist

MACMILLAN
£84.99 23 Sep 2026
Nonstationary Panels, Panel Cointegration, and Dynamic Panels: 15 (Advances in Econometrics, 15)
96% match

Nonstationary Panels, Panel Cointegration, and Dynamic Panels: 15 (Advances in Econometrics, 15)

Jai Press Inc.
£47.22 19 Sep 2026
Time Series Models: In Econometrics, Finance And Other Fields (Chapman & Hall/Crc Monographs On Statistics & Applied Probability): 65
96% match

Time Series Models: In Econometrics, Finance And Other Fields (Chapman & Hall/Crc Monographs On Statistics & Applied Probability): 65

Chapman and Hall/CRC
£93.00 24 Sep 2026
Modelling Non-Stationary Economic Time Series: A Multivariate Approach (Palgrave Texts in Econometrics)
96% match

Modelling Non-Stationary Economic Time Series: A Multivariate Approach (Palgrave Texts in Econometrics)

MACMILLAN
£77.05 24 Sep 2026
Time Series and Dynamic Models (Themes in Modern Econometrics)
96% match

Time Series and Dynamic Models (Themes in Modern Econometrics)

Cambridge University Press
£45.60 02 Oct 2026
Handbook of Applied Econometrics, Volume 2: Microeconomics: v. 2 (Blackwell Handbooks in Economics)
96% match

Handbook of Applied Econometrics, Volume 2: Microeconomics: v. 2 (Blackwell Handbooks in Economics)

Wiley

Price unavailable