£119.83

It has never been this cheap. We have no record of a lower price.

£120 today · cheaper than every other day in the last 3 months

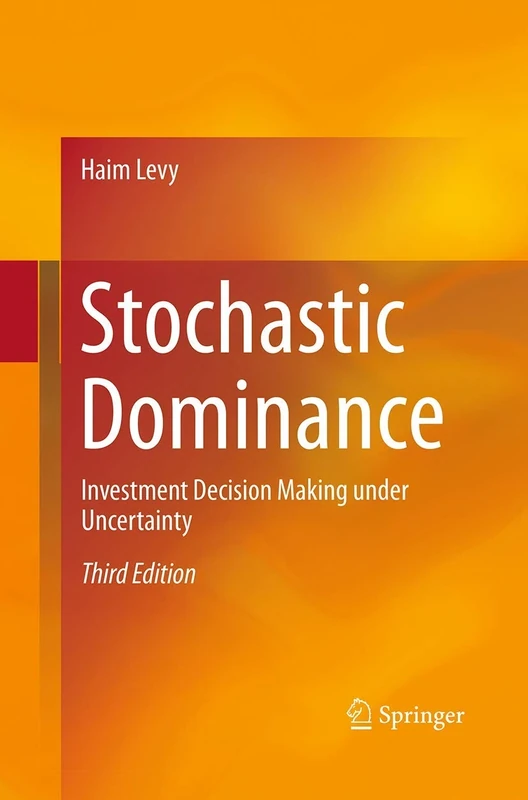
Springer Stochastic Dominance: Investment Decision Making under Uncertainty

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 16 days · 16 data points (no recent data)

Historical
Generating forecast…
£119.91 £119.82 £119.84 £119.86 £119.88 £119.90 £119.92 28 July 2026 31 July 2026 04 August 2026 08 August 2026 12 August 2026
View at Amazon ↗

Price data last checked 75 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 16 days • 1 price levels

Days at Price
16 days 0 4 8 12 16 £120 Days at Price

Price Analysis

Most common price: £120 (16 days, 100.0%)

Price range: £120 - £120

Price levels: 1 different prices over 16 days

Description

This fully updated third edition is devoted to the analysis of various Stochastic Dominance (SD) decision rules. It discusses the pros and cons of each of the alternate SD rules, the application of these rules to various research areas like statistics, agriculture, medicine, measuring income inequality and the poverty level in various countries, and of course, to investment decision-making under uncertainty. The book features changes and additions to the various chapters, and also includes two completely new chapters. One deals with asymptotic SD and the relation between FSD and the maximum geometric mean (MGM) rule (or the maximum growth portfolio). The other new chapter discusses bivariate SD rules where the individual’s utility is determined not only by his own wealth, but also by his standing relative to his peer group. Stochastic Dominance: Investment Decision Making under Uncertainty, 3rd Ed. covers the following basic issues: the SD approach, asymptotic SD rules, the mean-variance (MV) approach, as well as the non-expected utility approach. The non-expected utility approach focuses on Regret Theory (RT) and mainly on prospect theory (PT) and its modified version, cumulative prospect theory (CPT) which assumes S-shape preferences. In addition to these issues the book suggests a new stochastic dominance rule called the Markowitz stochastic dominance (MSD) rule corresponding to all reverse-S-shape preferences. It also discusses the concept of the multivariate expected utility and analyzed in more detail the bivariate expected utility case. From the reviews of the second edition: "This book is an economics book about stochastic dominance. … is certainly a valuable reference for graduate students interested in decision making under uncertainty. It investigates and compares different approaches and presents many examples. Moreover, empirical studies and experimental results play an important role in this book, which makes it interesting to read." (Nicole Bäuerle, Mathematical Reviews, Issue 2007 d) From the Back Cover This updated 3rd edition is devoted to the analysis of various Stochastic Dominance (SD) decision rules. It discusses the pros and cons of each of the alternate SD rules, the application of these rules to various research areas like statistics, agriculture, medicine, measuring income inequality and the poverty level in various countries, and of course, to investment decision-making under uncertainty. The book features changes and additions to the chapters, and also includes two completely new chapters. One deals with asymptotic SD and the relation between FSD and the maximum geometric mean (MGM) rule (or the maximum growth portfolio). The other new chapter discusses bivariate SD rules where the individual’s utility is determined not only by his own wealth, but also by his standing relative to his peer group. The book covers the following basic issues: the SD approach, asymptotic SD rules, the mean-variance (MV) approach, as well as the non-expected utility approach. The non-expected utility approach focuses on Regret Theory (RT) and mainly on prospect theory (PT) and its modified version, cumulative prospect theory (CPT) which assumes S-shape preferences. In addition to these issues the book suggests a new stochastic dominance rule called the Markowitz stochastic dominance (MSD) rule corresponding to all reverse-S-shape preferences. It also discusses the concept of the multivariate expected utility and analyzed in more detail the bivariate expected utility case. “In this book, Prof. Levy presents his in-depth insights on a wide range of SD-related topics such as the MV approach, almost MV rule, CAPM statistics, the bivariate and multivariate expected utility, and diversification. He also formulates the SD rules in terms of distribution quantiles so that he can extend the SD theories to analyze riskless assets, discuss some open problems in SD, and illustrate the applicatio

Product Specifications

Format
paperback
Domain
Amazon UK
Release Date
23 August 2016
Listed Since
17 August 2017

Barcode

No barcode data available

Similar Products You Might Like
Stochastic Dominance: Investment Decision Making under Uncertainty: 12 (Studies in Risk and Uncertainty)
97% match

Stochastic Dominance: Investment Decision Making under Uncertainty: 12 (Studies in Risk and Uncertainty)

Springer
£149.86 24 Sep 2026
Springer Stochastic Dominance - Investment Decision Making
97% match

Springer Stochastic Dominance - Investment Decision Making

Springer
£120.85 24 Aug 2026
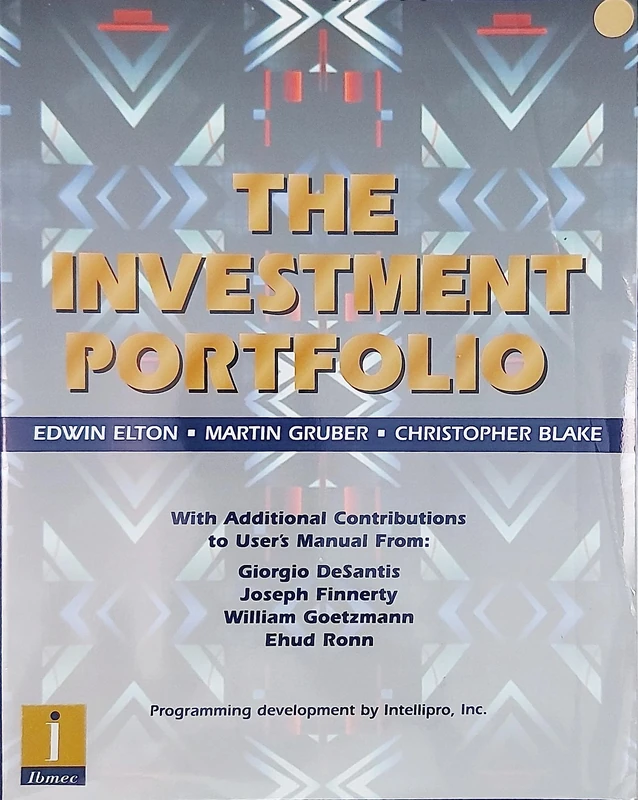
The Investment Portfolio User′s Manual
96% match

The Investment Portfolio User′s Manual

Wiley
£99.99 07 Sep 2026
An Outline of Financial Economics (Anthem Finance)
95% match

An Outline of Financial Economics (Anthem Finance)

Anthem Press
£79.97 22 Sep 2026
Robust Equity Portfolio Management: Formulations, Implementations, and Properties using MATLAB (Frank J. Fabozzi Series)
95% match

Robust Equity Portfolio Management: Formulations, Implementations, and Properties using MATLAB (Frank J. Fabozzi Series)

Wiley
£60.04 02 Oct 2026
Lectures On The Theory And Application Of Modern Finance With R And Chatgpt: 10 (World Scientific Lecture Notes in Finance)
95% match

Lectures On The Theory And Application Of Modern Finance With R And Chatgpt: 10 (World Scientific Lecture Notes in Finance)

World Scientific Publishing Company
£63.67 29 Aug 2026
Risk-Sensitive Investment Management (Advanced Series on Statistical Science & Applied Probability): 19
95% match

Risk-Sensitive Investment Management (Advanced Series on Statistical Science & Applied Probability): 19

World Scientific Publishing Company
£84.00 17 Sep 2026
McGraw-Hill Risk-Return Analysis Vol 3 - Harry Markowitz Book
95% match

McGraw-Hill Risk-Return Analysis Vol 3 - Harry Markowitz Book

McGraw-Hill Education
£64.05 29 Aug 2026
Quantitative Fund Management (Chapman & Hall/CRC Financial Mathematics)
95% match

Quantitative Fund Management (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.97 25 Sep 2026
Advanced Mathematical Methods for Finance
95% match

Advanced Mathematical Methods for Finance

Springer
£75.48 02 Oct 2026
The Capital Asset Pricing Model in the 21st Century: Analytical, Empirical, and Behavioral Perspectives
95% match

The Capital Asset Pricing Model in the 21st Century: Analytical, Empirical, and Behavioral Perspectives

Cambridge University Press
£124.99 03 Oct 2026
Multi-Asset Investing: A Practitioner's Framework
95% match

Multi-Asset Investing: A Practitioner's Framework

Wiley
£63.98 26 Sep 2026
The Methods of Distances in the Theory of Probability and Statistics
95% match

The Methods of Distances in the Theory of Probability and Statistics

Springer
£129.26 04 Sep 2026
Financial Models with Levy Processes and Volatility Clustering: 187 (Frank J. Fabozzi Series)
95% match

Financial Models with Levy Processes and Volatility Clustering: 187 (Frank J. Fabozzi Series)

Wiley
£55.40 02 Oct 2026
Investment Theory and Risk Management: 711 (Wiley Finance)
95% match

Investment Theory and Risk Management: 711 (Wiley Finance)

Wiley
£67.25 23 Sep 2026
J. Ross Publishing Investment Management & Financial Markets Book
95% match

J. Ross Publishing Investment Management & Financial Markets Book

J. Ross Publishing
£45.19 14 Aug 2026
Handbook of the Fundamentals of Financial Decision Making: In 2 Parts (World Scientific Handbook in Financial Economics) (World Scientific Handbook in Financial Economics Series): 4
95% match

Handbook of the Fundamentals of Financial Decision Making: In 2 Parts (World Scientific Handbook in Financial Economics) (World Scientific Handbook in Financial Economics Series): 4

World Scientific Publishing Company
£54.37 06 Oct 2026
The Art of Asset Allocation: Principles and Investment Strategies for Any Market, Second Edition: Principles and Investment Strategies for Any Market, ... Edition (PROFESSIONAL FINANCE & INVESTM)
95% match

The Art of Asset Allocation: Principles and Investment Strategies for Any Market, Second Edition: Principles and Investment Strategies for Any Market, ... Edition (PROFESSIONAL FINANCE & INVESTM)

McGraw-Hill Education
£44.86 10 Sep 2026
CRC Press - Introduction to Risk Parity and Budgeting Book
95% match

CRC Press - Introduction to Risk Parity and Budgeting Book

CRC Press
£71.99 11 Aug 2026
Asset Management and Institutional Investors - Portfolio Methods
95% match

Asset Management and Institutional Investors - Portfolio Methods

Springer
£139.77 07 Oct 2026
Investment Analysis: An Introduction to Portfolio Theory and Management
95% match

Investment Analysis: An Introduction to Portfolio Theory and Management

Routledge
£57.99 23 Sep 2026
Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™
95% match

Modern Portfolio Optimization with NuOPT™, S-PLUS®, and S+Bayes™

Springer
£89.99 24 Sep 2026
Princeton University Press - Financial Decisions and Markets Book
95% match

Princeton University Press - Financial Decisions and Markets Book

Princeton University Press
£60.34 12 Sep 2026
Wiley Quantitative Portfolio Optimization - Advanced Finance Book
95% match

Wiley Quantitative Portfolio Optimization - Advanced Finance Book

Wiley

£50.36 20 Aug 2026