£73.85

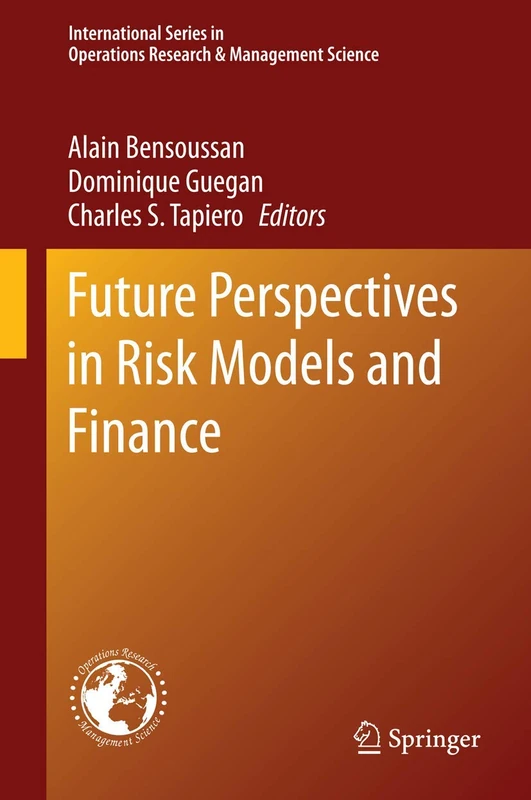
Springer Future Perspectives in Risk Models and Finance: 211 (International Series in Operations Research & Management Science, 211)

Price data last checked 10 day(s) ago - will refresh soon

View at Amazon

We'll watch every seller, every day. One email when your price arrives.

It has never been this cheap. We have no record of a lower price.

£74 today · cheaper than every other day in the last 3 months

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↓ Price chart
when this has been cheap or pricey
↓ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 81 days · 81 data points (no recent data)

Historical
Generating forecast…
£73.85 £70.16 £71.63 £73.11 £74.59 £76.07 £77.54 26 June 2026 16 July 2026 05 August 2026 25 August 2026 14 September 2026

Price Distribution

Price distribution over 81 days • 1 price levels

Days at Price
81 days 0 20 41 61 81 £74 Days at Price

Price Analysis

Most common price: £74 (81 days, 100.0%)

Price range: £74 - £74

Price levels: 1 different prices over 81 days

Description

This book provides a perspective on a number of approaches to financial modelling and risk management. It examines both theoretical and practical issues. Theoretically, financial risks models are models of a real and a financial “uncertainty”, based on both common and private information and economic theories defining the rules that financial markets comply to. Financial models are thus challenged by their definitions and by a changing financial system fueled by globalization, technology growth, complexity, regulation and the many factors that contribute to rendering financial processes to be continuously questioned and re-assessed. The underlying mathematical foundations of financial risks models provide future guidelines for risk modeling. The book’s chapters provide selective insights and developments that can contribute to better understand the complexity of financial modelling and its ability to bridge financial theories and their practice. Future Perspectives in Risk Models and Finance begins with an extensive outline by Alain Bensoussan et al. of GLM estimation techniques combined with proofs of fundamental results. Applications to static and dynamic models provide a unified approach to the estimation of nonlinear risk models. A second section is concerned with the definition of risks and their management. In particular, Guegan and Hassani review a number of risk models definition emphasizing the importance of bi-modal distributions for financial regulation. An additional chapter provides a review of stress testing and their implications. Nassim Taleb and Sandis provide an anti-fragility approach based on “skin in the game”. To conclude, Raphael Douady discusses the noncyclical CAR (Capital Adequacy Rule) and their effects of aversion of systemic risks. A third section emphasizes analytic financial modelling approaches and techniques. Tapiero and Vallois provide an overview of mathematical systems and their use infinancial modeling. These systems span the fundamental Arrow-Debreu framework underlying financial models of complete markets and subsequently, mathematical systems departing from this framework but yet generalizing their approach to dynamic financial models. Explicitly, models based on fractional calculus, on persistence (short memory) and on entropy-based non-extensiveness. Applications of these models are used to define a modeling approach to incomplete financial models and their potential use as a “measure of incompleteness”. Subsequently Bianchi and Pianese provide an extensive overview of multi-fractional models and their important applications to Asset price modeling. Finally, Tapiero and Jinquyi consider the binomial pricing model by discussing the effects of memory on the pricing of asset prices.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
03 December 2014
Listed Since
02 May 2014

Barcode

No barcode data available

Similar Products You Might Like
Market Risk and Financial Markets Modeling
84% match

Market Risk and Financial Markets Modeling

Springer
£100.11 10 Aug 2026
Scenario Analysis in Risk Management: Theory and Practice in Finance
83% match

Scenario Analysis in Risk Management: Theory and Practice in Finance

Springer
£74.38 08 Aug 2026
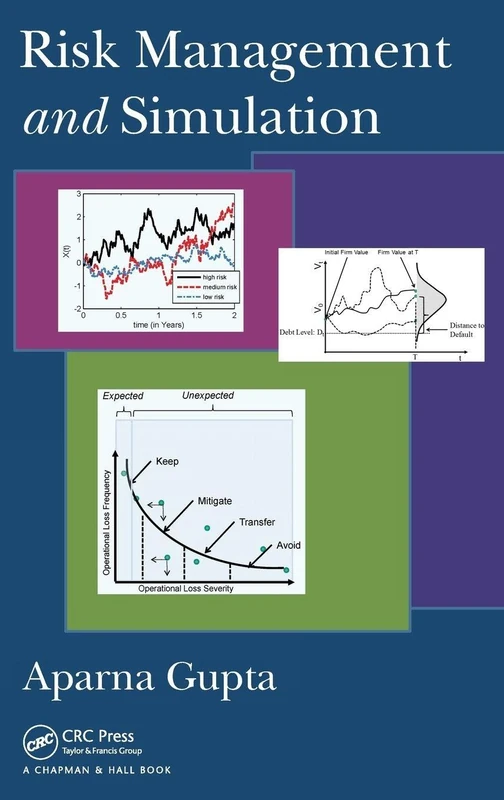
Risk Management and Simulation
82% match

Risk Management and Simulation

CRC Press
£182.93 08 Aug 2026
Financial Risk Management: Applications in Market, Credit, Asset and Liability Management and Firmwide Risk (Wiley Finance)
81% match

Financial Risk Management: Applications in Market, Credit, Asset and Liability Management and Firmwide Risk (Wiley Finance)

Wiley
£71.49 06 Aug 2026
Mathematical Risk Analysis: Dependence, Risk Bounds, Optimal Allocations and Portfolios (Springer Series in Operations Research and Financial Engineering)
81% match

Mathematical Risk Analysis: Dependence, Risk Bounds, Optimal Allocations and Portfolios (Springer Series in Operations Research and Financial Engineering)

Springer
£61.84 08 Aug 2026
Stochastic Modeling in Economics and Finance: 75 (Applied Optimization, 75)
81% match

Stochastic Modeling in Economics and Finance: 75 (Applied Optimization, 75)

Springer
£76.42 13 Aug 2026
Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)
81% match

Financial Modeling: A Backward Stochastic Differential Equations Perspective (Springer Finance)

Springer
£58.93 07 Aug 2026
Financial Risk and Derivatives: A Special Issue of the Geneva Papers on Risk and Insurance Theory
80% match

Financial Risk and Derivatives: A Special Issue of the Geneva Papers on Risk and Insurance Theory

Springer
£73.78 05 Aug 2026
Managing Illiquid Assets: Perspectives and Challenges
80% match

Managing Illiquid Assets: Perspectives and Challenges

Risk Books
£145.00 18 Aug 2026
Dynamic Portfolio Strategies: quantitative methods and empirical rules for incomplete information: Quantitative Methods and Empirical Rules for ... Operations Research & Management Science, 47)
80% match

Dynamic Portfolio Strategies: quantitative methods and empirical rules for incomplete information: Quantitative Methods and Empirical Rules for ... Operations Research & Management Science, 47)

Springer
£75.58 05 Aug 2026
Fixed Income Modelling
80% match

Fixed Income Modelling

Oxford University Press

£51.51 06 Aug 2026
New Frontiers in Enterprise Risk Management
80% match

New Frontiers in Enterprise Risk Management

Springer
£73.85 18 Aug 2026
Risk Management: The State of the Art: 8 (The New York University Salomon Center Series on Financial Markets and Institutions, 8)
80% match

Risk Management: The State of the Art: 8 (The New York University Salomon Center Series on Financial Markets and Institutions, 8)

Springer
£109.00 07 Aug 2026
Optimal Statistical Inference in Financial Engineering
80% match

Optimal Statistical Inference in Financial Engineering

CRC Press
£164.04 04 Aug 2026
Option Pricing and Estimation of Financial Models with R
80% match

Option Pricing and Estimation of Financial Models with R

Wiley

£77.39 17 Aug 2026
Financial Decision Making Using Computational Intelligence: 70 (Springer Optimization and Its Applications, 70)
80% match

Financial Decision Making Using Computational Intelligence: 70 (Springer Optimization and Its Applications, 70)

Springer
£76.03 06 Aug 2026
Risk Management, Speculation, and Derivative Securities
80% match

Risk Management, Speculation, and Derivative Securities

Academic Press
£105.00 05 Aug 2026
An Intuitive Introduction to Finance and Derivatives: Concepts, Terminology and Models (Springer Texts in Business and Economics)
79% match

An Intuitive Introduction to Finance and Derivatives: Concepts, Terminology and Models (Springer Texts in Business and Economics)

Springer
£52.80 03 Aug 2026
Stochastic Optimization Methods in Finance and Energy: New Financial Products and Energy Market Strategies: 163 (International Series in Operations Research & Management Science, 163)
79% match

Stochastic Optimization Methods in Finance and Energy: New Financial Products and Energy Market Strategies: 163 (International Series in Operations Research & Management Science, 163)

Springer

£109.08 06 Aug 2026
Risk Management In Digital Finance
79% match

Risk Management In Digital Finance

World Scientific Publishing Company
£85.54 30 Jul 2026
Financial Modeling, Actuarial Valuation and Solvency in Insurance (Springer Finance)
79% match

Financial Modeling, Actuarial Valuation and Solvency in Insurance (Springer Finance)

Springer
£63.36 06 Aug 2026
State-Space Approaches for Modelling and Control in Financial Engineering: Systems theory and machine learning methods: 125 (Intelligent Systems Reference Library, 125)
79% match

State-Space Approaches for Modelling and Control in Financial Engineering: Systems theory and machine learning methods: 125 (Intelligent Systems Reference Library, 125)

Springer
£76.05 05 Aug 2026
Advances in Risk Management (Finance and Capital Markets Series)
79% match

Advances in Risk Management (Finance and Capital Markets Series)

MACMILLAN
£105.60 06 Aug 2026
Essential Mathematics for Market Risk Management (The Wiley Finance Series)
79% match

Essential Mathematics for Market Risk Management (The Wiley Finance Series)

Wiley

£40.89 14 Jul 2026