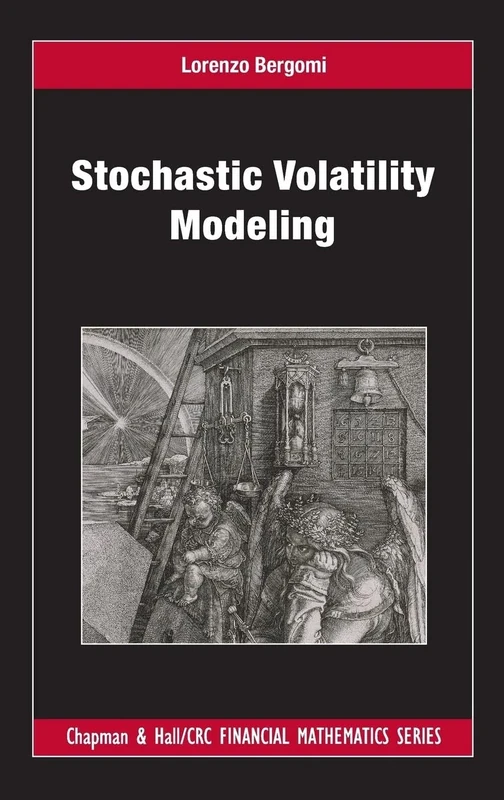
£77.99

It has never been this cheap. We have no record of a lower price.

£78 today · cheaper than every other day in the last 3 months

CRC Press Stochastic Volatility Modeling (Chapman and Hall/CRC Financial Mathematics Series)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 87 days · 87 data points (no recent data)

Historical
Generating forecast…
£92.99 £76.49 £80.09 £83.69 £87.29 £90.89 £94.49 25 July 2026 15 August 2026 06 September 2026 27 September 2026 19 October 2026
View at Amazon ↗

Price data checked 4 days ago

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 87 days • 2 price levels

Days at Price
Current Price
22 days · current 65 days 0 16 33 49 65 £78 £93 Days at Price

Price Analysis

Most common price: £93 (65 days, 74.7%)

Price range: £78 - £93

Price levels: 2 different prices over 87 days

Description

Packed with insights, Lorenzo Bergomi’s Stochastic Volatility Modeling explains how stochastic volatility is used to address issues arising in the modeling of derivatives, including: Which trading issues do we tackle with stochastic volatility? How do we design models and assess their relevance? How do we tell which models are usable and when does calibration make sense? This manual covers the practicalities of modeling local volatility, stochastic volatility, local-stochastic volatility, and multi-asset stochastic volatility. In the course of this exploration, the author, Risk’s 2009 Quant of the Year and a leading contributor to volatility modeling, draws on his experience as head quant in Société Générale’s equity derivatives division. Clear and straightforward, the book takes readers through various modeling challenges, all originating in actual trading/hedging issues, with a focus on the practical consequences of modeling choices.

Key Features

New Store Stock

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
05 January 2016
Listed Since
15 April 2015

Barcode

No barcode data available

Similar Products You Might Like
Stochastic Volatility in Financial Markets: Crossing the Bridge to Continuous Time: 3 (Dynamic Modeling and Econometrics in Economics and Finance, 3)
98% match

Stochastic Volatility in Financial Markets: Crossing the Bridge to Continuous Time: 3 (Dynamic Modeling and Econometrics in Economics and Finance, 3)

Springer
£82.17 03 Oct 2026
Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives
98% match

Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives

Cambridge University Press
£49.79 07 Oct 2026
Parameter Estimation in Stochastic Volatility Models
98% match

Parameter Estimation in Stochastic Volatility Models

Springer
£97.00 05 Oct 2026
Rough Volatility: 2 - Financial Mathematics Textbook
98% match

Rough Volatility: 2 - Financial Mathematics Textbook

£61.84 11 Aug 2026
Handbook of Volatility Models and Their Applications: 03 (Wiley Handbooks in Financial Engineering and Econometrics)
97% match

Handbook of Volatility Models and Their Applications: 03 (Wiley Handbooks in Financial Engineering and Econometrics)

Wiley
£123.96 15 Aug 2026
Parameter Estimation in Stochastic Volatility Models
97% match

Parameter Estimation in Stochastic Volatility Models

Springer
£109.08 19 Aug 2026
Stock Market Volatility (Chapman & Hall/CRC Finance Series)
97% match

Stock Market Volatility (Chapman & Hall/CRC Finance Series)

CRC Press
£235.00 23 Sep 2026
Stock Market Volatility (Chapman & Hall/CRC Finance Series)
97% match

Stock Market Volatility (Chapman & Hall/CRC Finance Series)

CRC Press
£77.00 11 Sep 2026
Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)
97% match

Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)

Springer
£123.92 19 Aug 2026
Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)
97% match

Derivative Security Pricing: Techniques, Methods and Applications: 21 (Dynamic Modeling and Econometrics in Economics and Finance, 21)

Springer
£124.31 19 Aug 2026
Stochastic Volatility: Selected Readings (Advanced Texts in Econometrics)
97% match

Stochastic Volatility: Selected Readings (Advanced Texts in Econometrics)

Oxford University Press
£62.00 06 Oct 2026
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
97% match

Analytically Tractable Stochastic Stock Price Models (Springer Finance)

Springer
£58.50 21 Oct 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Aug 2026
Analytically Tractable Stochastic Stock Price Models (Springer Finance)
97% match

Analytically Tractable Stochastic Stock Price Models (Springer Finance)

Springer
£43.32 04 Sep 2026
Semiparametric Modeling of Implied Volatility (Springer Finance)
97% match

Semiparametric Modeling of Implied Volatility (Springer Finance)

Springer
£59.93 17 Oct 2026
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Sep 2026
Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)
97% match

Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)

Wiley
£60.99 17 Sep 2026
DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE
97% match

DETERMINISTIC AND STOCHASTIC TOPICS IN COMPUTATIONAL FINANCE

World Scientific Publishing Company
£68.33 13 Sep 2026
Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)
97% match

Volatility Surface and Term Structure: High-profit Options Trading Strategies (Routledge Advances in Risk Management)

Routledge
£48.99 09 Sep 2026
Wiley The Volatility Smile - Finance Textbook for Students
97% match

Wiley The Volatility Smile - Finance Textbook for Students

Wiley
£39.28 19 Aug 2026
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
97% match

Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)

Springer
£94.74 24 Sep 2026
Forecasting Volatility in the Financial Markets
97% match

Forecasting Volatility in the Financial Markets

Butterworth-Heinemann
£71.00 18 Sep 2026
Volatility Surface and Term Structure - Options Trading Strategies
97% match

Volatility Surface and Term Structure - Options Trading Strategies

Routledge
£145.15 06 Oct 2026
Financial Economics, Risk And Information (2nd Edition)
97% match

Financial Economics, Risk And Information (2nd Edition)

World Scientific Publishing Company

£60.38 22 Sep 2026