£39.77

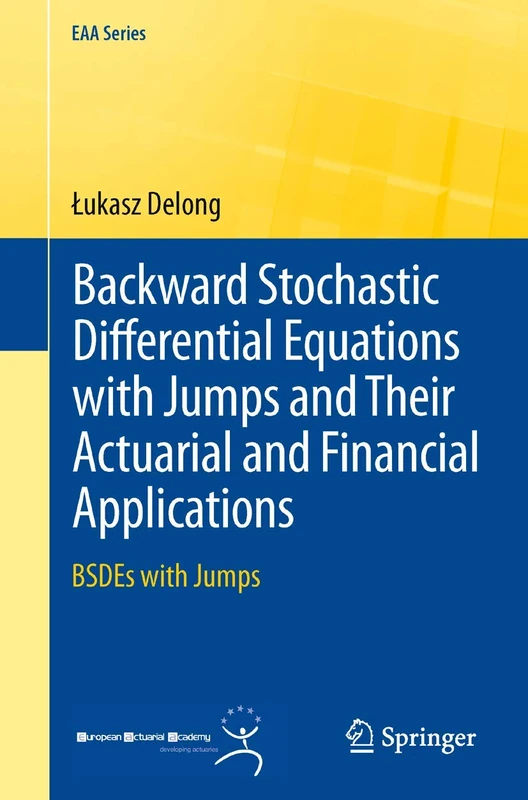
Springer Backward Stochastic Differential Equations with Jumps and Their Actuarial and Financial Applications: BSDEs with Jumps (EAA Series)

Price data checked 4 days ago

View at Amazon

We'll watch every seller, every day. One email when your price arrives.

This is the most expensive it has ever been. Walk away.

£40 today · previous high £40 · all-time low £30

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↓ Price chart
when this has been cheap or pricey
↓ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 87 days · 87 data points (no recent data)

Historical
Generating forecast…
£39.77 £28.84 £31.22 £33.61 £35.99 £38.38 £40.76 09 July 2026 30 July 2026 21 August 2026 11 September 2026 03 October 2026

Price Distribution

Price distribution over 87 days • 2 price levels

Days at Price
Current Price
3 days 84 days · current 0 21 42 63 84 £30 £40 Days at Price

Price Analysis

Most common price: £40 (84 days, 96.6%)

Price range: £30 - £40

Price levels: 2 different prices over 87 days

Description

Backward stochastic differential equations with jumps can be used to solve problems in both finance and insurance. Part I of this book presents the theory of BSDEs with Lipschitz generators driven by a Brownian motion and a compensated random measure, with an emphasis on those generated by step processes and Lévy processes. It discusses key results and techniques (including numerical algorithms) for BSDEs with jumps and studies filtration-consistent nonlinear expectations and g-expectations. Part I also focuses on the mathematical tools and proofs which are crucial for understanding the theory. Part II investigates actuarial and financial applications of BSDEs with jumps. It considers a general financial and insurance model and deals with pricing and hedging of insurance equity-linked claims and asset-liability management problems. It additionally investigates perfect hedging, superhedging, quadratic optimization, utility maximization, indifference pricing, ambiguity risk minimization, no-good-deal pricing and dynamic risk measures. Part III presents some other useful classes of BSDEs and their applications. This book will make BSDEs more accessible to those who are interested in applying these equations to actuarial and financial problems. It will be beneficial to students and researchers in mathematical finance, risk measures, portfolio optimization as well as actuarial practitioners.

Product Specifications

Format
paperback
Domain
Amazon UK
Publication Date
25 June 2013
Listed Since
10 May 2013

Barcode

No barcode data available

Similar Products You Might Like
Optional Processes: Theory and Applications (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Optional Processes: Theory and Applications (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£104.82 12 Sep 2026
Numerical Solution of Stochastic Differential Equations with Jumps in Finance: 64 (Stochastic Modelling and Applied Probability, 64)
97% match

Numerical Solution of Stochastic Differential Equations with Jumps in Finance: 64 (Stochastic Modelling and Applied Probability, 64)

Springer
£101.71 03 Oct 2026
Monte Carlo Methods and Models in Finance and Insurance
97% match

Monte Carlo Methods and Models in Finance and Insurance

CRC Press
£124.01 03 Oct 2026
STOCHASTIC PROCESSES, FINANCE AND CONTROL: A FESTSCHRIFT IN HONOR OF ROBERT J ELLIOTT: 1 (ADVANCES IN STATISTICS, PROBABILITY AND ACTUARIAL SCIENCE)
97% match

STOCHASTIC PROCESSES, FINANCE AND CONTROL: A FESTSCHRIFT IN HONOR OF ROBERT J ELLIOTT: 1 (ADVANCES IN STATISTICS, PROBABILITY AND ACTUARIAL SCIENCE)

World Scientific Publishing Company
£81.02 19 Sep 2026
Monte Carlo Methods and Models in Finance and Insurance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Monte Carlo Methods and Models in Finance and Insurance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£48.99 10 Sep 2026
Risk And Stochastics: Ragnar Norberg (Mathematical Finance Economics)
97% match

Risk And Stochastics: Ragnar Norberg (Mathematical Finance Economics)

World Scientific Publishing Company
£77.07 29 Aug 2026
Stochastic Processes with Applications to Finance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Stochastic Processes with Applications to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£103.17 01 Oct 2026
Mathematical and Statistical Methods for Actuarial Sciences and Finance: MAF 2018
97% match

Mathematical and Statistical Methods for Actuarial Sciences and Finance: MAF 2018

Springer
£160.88 18 Aug 2026
Applied Diffusion Processes: Engineering to Finance - Stochastic Methods
97% match

Applied Diffusion Processes: Engineering to Finance - Stochastic Methods

Wiley
£97.00 07 Oct 2026
Actuarial Finance: Derivatives, Quantitative Models and Risk Management
97% match

Actuarial Finance: Derivatives, Quantitative Models and Risk Management

Wiley
£92.28 11 Sep 2026
Mathematical and Statistical Methods for Actuarial Sciences and Finance
97% match

Mathematical and Statistical Methods for Actuarial Sciences and Finance

Springer
£82.29 06 Oct 2026
Advances in Heavy Tailed Risk Modeling: A Handbook of Operational Risk (Wiley Handbooks in Financial Engineering and Econometrics)
97% match

Advances in Heavy Tailed Risk Modeling: A Handbook of Operational Risk (Wiley Handbooks in Financial Engineering and Econometrics)

Wiley
£112.99 17 Sep 2026
Mathematical and Statistical Methods for Actuarial Sciences and Finance
97% match

Mathematical and Statistical Methods for Actuarial Sciences and Finance

Springer
£88.02 24 Sep 2026
Risk Analysis in Finance and Insurance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Risk Analysis in Finance and Insurance (Chapman and Hall/CRC Financial Mathematics Series)

Chapman and Hall/CRC
£59.35 03 Oct 2026
Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Introduction to Stochastic Calculus Applied to Finance (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£49.93 28 Aug 2026
Probability and Random Processes with One Thousand Exercises in Probability
97% match

Probability and Random Processes with One Thousand Exercises in Probability

Oxford University Press
£83.88 04 Sep 2026
Elements Of Stochastic Modelling (third Edition): 3rd Edition
97% match

Elements Of Stochastic Modelling (third Edition): 3rd Edition

World Scientific Publishing Company
£53.12 06 Oct 2026
Mathematical Risk Analysis: Dependence, Risk Bounds, Optimal Allocations and Portfolios (Springer Series in Operations Research and Financial Engineering)
97% match

Mathematical Risk Analysis: Dependence, Risk Bounds, Optimal Allocations and Portfolios (Springer Series in Operations Research and Financial Engineering)

Springer
£74.21 05 Aug 2026
Fundamentals of Actuarial Mathematics, 3rd Edition
97% match

Fundamentals of Actuarial Mathematics, 3rd Edition

Wiley
£58.45 29 Aug 2026
From Statistics to Mathematical Finance: Festschrift in Honour of Winfried Stute
97% match

From Statistics to Mathematical Finance: Festschrift in Honour of Winfried Stute

Springer
£86.11 24 Jul 2026
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Sep 2026
Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach
97% match

Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach

Wiley
£108.01 15 Aug 2026
Optimal Stopping and Free-Boundary Problems (Lectures in Mathematics. ETH Zürich)
97% match

Optimal Stopping and Free-Boundary Problems (Lectures in Mathematics. ETH Zürich)

Birkhauser
£115.83 25 Aug 2026
Actuarial Sciences and Quantitative Finance: ICASQF, Bogotá, Colombia, June 2014: 135 (Springer Proceedings in Mathematics & Statistics, 135)
97% match

Actuarial Sciences and Quantitative Finance: ICASQF, Bogotá, Colombia, June 2014: 135 (Springer Proceedings in Mathematics & Statistics, 135)

Springer

£72.17 31 Jul 2026