£183.52

It has never been this cheap. We have no record of a lower price.

£184 today · cheaper than every other day in the last 3 months

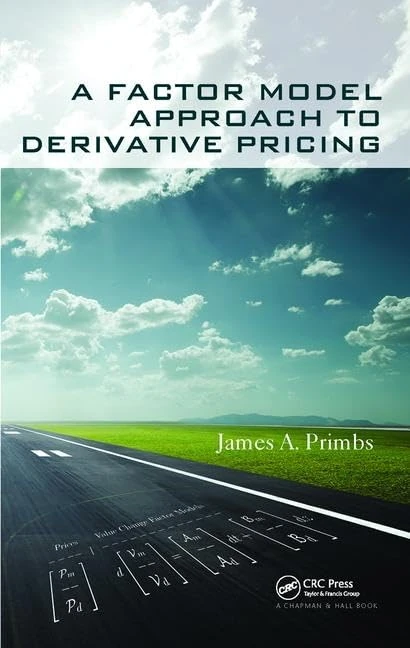
CRC Press A Factor Model Approach to Derivative Pricing

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 34 days · 34 data points (no recent data)

Historical
Generating forecast…
£183.52 £174.34 £178.01 £181.68 £185.36 £189.03 £192.70 01 August 2026 09 August 2026 17 August 2026 25 August 2026 03 September 2026
View at Amazon ↗

Price data last checked 50 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 34 days • 1 price levels

Days at Price
34 days 0 9 17 26 34 £184 Days at Price

Price Analysis

Most common price: £184 (34 days, 100.0%)

Price range: £184 - £184

Price levels: 1 different prices over 34 days

Description

Written in a highly accessible style, A Factor Model Approach to Derivative Pricing lays a clear and structured foundation for the pricing of derivative securities based upon simple factor model related absence of arbitrage ideas. This unique and unifying approach provides for a broad treatment of topics and models, including equity, interest-rate, and credit derivatives, as well as hedging and tree-based computational methods, but without reliance on the heavy prerequisites that often accompany such topics. Key features A single fundamental absence of arbitrage relationship based on factor models is used to motivate all the results in the book A structured three-step procedure is used to guide the derivation of absence of arbitrage equations and illuminate core underlying concepts Brownian motion and Poisson process driven models are treated together, allowing for a broad and cohesive presentation of topics The final chapter provides a new approach to risk neutral pricing that introduces the topic as a seamless and natural extension of the factor model approach Whether being used as text for an intermediate level course in derivatives, or by researchers and practitioners who are seeking a better understanding of the fundamental ideas that underlie derivative pricing, readers will appreciate the book‘s ability to unify many disparate topics and models under a single conceptual theme. James A Primbs is an Associate Professor of Finance at the Mihaylo College of Business and Economics at California State University, Fullerton.

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
27 July 2017
Listed Since
31 August 2017

Barcode

No barcode data available

Similar Products You Might Like
Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)
98% match

Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)

Wiley
£49.61 29 Aug 2026
Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach
98% match

Measure, Probability, and Mathematical Finance: A Problem-Oriented Approach

Wiley
£108.01 15 Aug 2026
PRICING DERIVATIVE SECURITIES (2ND EDITION): Second Edition
98% match

PRICING DERIVATIVE SECURITIES (2ND EDITION): Second Edition

World Scientific Publishing Company
£38.10 07 Oct 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
98% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Introduction to Stochastic Finance with Market Examples (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£105.00 20 Aug 2026
An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)
98% match

An Introduction to Exotic Option Pricing (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£182.82 20 Aug 2026
Stochastic Finance: A Numeraire Approach (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Stochastic Finance: A Numeraire Approach (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£190.00 21 Aug 2026
American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)
98% match

American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£118.75 14 Oct 2026
American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)
98% match

American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£63.17 19 Sep 2026
The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)
98% match

The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)

£30.33 22 Sep 2026
Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£95.72 25 Sep 2026
Financial Mathematics, Derivatives and Structured Products - Springer Finance
98% match

Financial Mathematics, Derivatives and Structured Products - Springer Finance

Springer
£55.90 09 Oct 2026
Pearson John Hull Options, Futures, and Other Derivatives 11th Ed
98% match

Pearson John Hull Options, Futures, and Other Derivatives 11th Ed

PEARSON EDUCATION
£53.90 18 Aug 2026
Financial Derivatives: Pricing, Applications, and Mathematics
98% match

Financial Derivatives: Pricing, Applications, and Mathematics

Cambridge University Press
£91.83 10 Oct 2026
Springer Stochastic Models for Energy and Commodity Markets
98% match

Springer Stochastic Models for Energy and Commodity Markets

Springer
£90.63 21 Aug 2026
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
98% match

Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation

MACMILLAN
£52.36 11 Sep 2026
Wiley Paul Wilmott on Quantitative Finance 2nd Edition
98% match

Wiley Paul Wilmott on Quantitative Finance 2nd Edition

Wiley
£160.98 21 Oct 2026
Computational Methods for Quantitative Finance: Finite Element Methods for Derivative Pricing (Springer Finance)
98% match

Computational Methods for Quantitative Finance: Finite Element Methods for Derivative Pricing (Springer Finance)

Springer
£58.50 07 Oct 2026
Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)
98% match

Stochastic Financial Models (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£93.79 11 Sep 2026
Princeton University Press - Interest-Rate Derivatives Book
98% match

Princeton University Press - Interest-Rate Derivatives Book

Princeton University Press
£131.86 22 Sep 2026
Computation and Simulation for Finance: An Introduction with Python (Springer Undergraduate Texts in Mathematics and Technology)
98% match

Computation and Simulation for Finance: An Introduction with Python (Springer Undergraduate Texts in Mathematics and Technology)

Springer

£46.51 11 Aug 2026
Academic Press Advanced Derivatives Pricing and Risk Management
98% match

Academic Press Advanced Derivatives Pricing and Risk Management

Elsevier
£469.79 11 Oct 2026
Derivatives Unlocked: A Practitioner’s Perspective
98% match

Derivatives Unlocked: A Practitioner’s Perspective

Chapman and Hall/CRC
£61.47 26 Aug 2026
Wiley Levy Processes in Finance: Pricing Financial Derivatives
98% match

Wiley Levy Processes in Finance: Pricing Financial Derivatives

Wiley

£93.72 18 Aug 2026