£66.99

It has never been this cheap. We have no record of a lower price.

£67 today · cheaper than every other day in the last 3 months

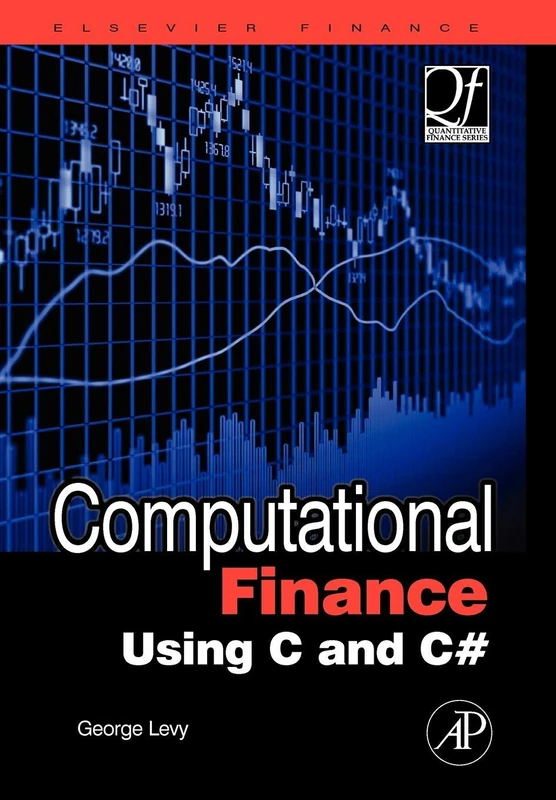
Elsevier Computational Finance Using C and C# (Quantitative Finance)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 59 days · 59 data points (no recent data)

Historical
Generating forecast…
£66.99 £63.64 £64.98 £66.32 £67.66 £69.00 £70.34 25 July 2026 08 August 2026 23 August 2026 06 September 2026 21 September 2026
View at Amazon ↗

Price data last checked 32 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 59 days • 1 price levels

Days at Price
59 days 0 15 30 44 59 £67 Days at Price

Price Analysis

Most common price: £67 (59 days, 100.0%)

Price range: £67 - £67

Price levels: 1 different prices over 59 days

Description

Computational Finance Using C and C# raises computational finance to the next level using the languages of both standard C and C#. The inclusion of both these languages enables readers to match their use of the book to their firm’s internal software and code requirements. The book also provides derivatives pricing information for equity derivates (vanilla options, quantos, generic equity basket options); interest rate derivatives (FRAs, swaps, quantos); foreign exchange derivatives (FX forwards, FX options); and credit derivatives (credit default swaps, defaultable bonds, total return swaps). This book is organized into 8 chapters, beginning with an overview of financial derivatives followed by an introduction to stochastic processes. The discussion then shifts to generation of random variates; European options; single asset American options; multi-asset options; other financial derivatives; and C# portfolio pricing application. The text is supported by a multi-tier website which enables purchasers of the book to download free software, which includes executable files, configuration files, and results files. With these files the user can run the C# portfolio pricing application and change the portfolio composition and the attributes of the deals. This book will be of interest to financial engineers and analysts as well as numerical analysts in banking, insurance, and corporate finance. Illustrates the use of C# design patterns, including dictionaries, abstract classes, and .NET InteropServices

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
12 June 2008
Listed Since
28 December 2007

Barcode

No barcode data available

Similar Products You Might Like
Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation
98% match

Analytical Finance: Volume II: The Mathematics of Interest Rate Derivatives, Markets, Risk and Valuation

MACMILLAN
£52.36 11 Sep 2026
Wiley Paul Wilmott on Quantitative Finance 2nd Edition
98% match

Wiley Paul Wilmott on Quantitative Finance 2nd Edition

Wiley
£160.98 21 Oct 2026
Wiley Problems and Solutions in Mathematical Finance Vol 2
98% match

Wiley Problems and Solutions in Mathematical Finance Vol 2

Wiley
£59.85 26 Aug 2026
Financial Engineering: Derivatives and Risk Management
98% match

Financial Engineering: Derivatives and Risk Management

Wiley
£46.54 08 Sep 2026
C++ for Financial Mathematics (Chapman and Hall/CRC Financial Mathematics Series)
98% match

C++ for Financial Mathematics (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£71.88 26 Aug 2026
Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1
97% match

Analytical Finance: Volume I: The Mathematics of Equity Derivatives, Markets, Risk and Valuation: 1

MACMILLAN
£46.24 08 Sep 2026
Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)
97% match

Foundations of the Pricing of Financial Derivatives: Theory and Analysis (Frank J. Fabozzi Series)

Wiley
£49.61 29 Aug 2026
Derivative Securities and Difference Methods (Springer Finance)
97% match

Derivative Securities and Difference Methods (Springer Finance)

Springer
£106.65 23 Sep 2026
Implementing Models in Quantitative Finance: Methods and Cases (Springer Finance)
97% match

Implementing Models in Quantitative Finance: Methods and Cases (Springer Finance)

Springer
£57.69 02 Oct 2026
Derivatives Unlocked: A Practitioner’s Perspective
97% match

Derivatives Unlocked: A Practitioner’s Perspective

Chapman and Hall/CRC
£61.47 26 Aug 2026
World Scientific Quantitative Analysis and Derivatives Modeling
97% match

World Scientific Quantitative Analysis and Derivatives Modeling

World Scientific Publishing Company
£82.86 02 Oct 2026
Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-Income Market
97% match

Quantitative Analysis, Derivatives Modeling, And Trading Strategies: In The Presence Of Counterparty Credit Risk For The Fixed-Income Market

World Scientific Publishing Company
£53.52 06 Sep 2026
American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)
97% match

American-Style Derivatives: Valuation and Computation (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£63.17 19 Sep 2026
Wiley Financial Instrument Pricing Using C++ Guide
97% match

Wiley Financial Instrument Pricing Using C++ Guide

Wiley
£77.58 25 Aug 2026
World Scientific Fitting Local Volatility - Finance Book
97% match

World Scientific Fitting Local Volatility - Finance Book

World Scientific Publishing Company
£55.68 03 Sep 2026
Pearson John Hull Options, Futures, and Other Derivatives 11th Ed
97% match

Pearson John Hull Options, Futures, and Other Derivatives 11th Ed

PEARSON EDUCATION
£53.90 18 Aug 2026
A Factor Model Approach to Derivative Pricing
97% match

A Factor Model Approach to Derivative Pricing

CRC Press
£183.52 03 Sep 2026
The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)
97% match

The Mathematics of Finance: Modeling and Hedging (Pure and Applied Undergraduate Texts)

£30.33 22 Sep 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
97% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Financial Mathematics: A Comprehensive Treatment in Discrete Time (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£95.72 25 Sep 2026
Wiley Pricing Financial Instruments: The Finite Difference Method
97% match

Wiley Pricing Financial Instruments: The Finite Difference Method

Wiley

£62.45 26 Sep 2026