£49.40

It has never been this cheap. We have no record of a lower price.

£49 today · cheaper than every other day in the last 3 months

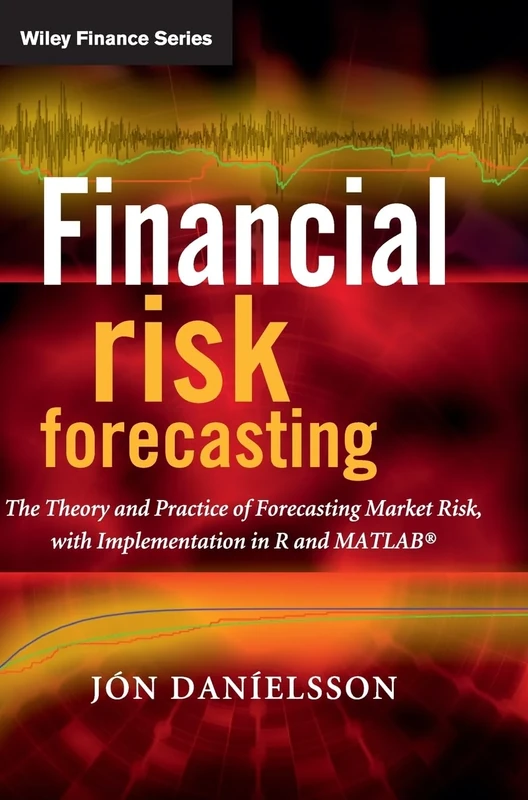
Wiley Financial Risk Forecasting: The Theory and Practice of Forecasting Market Risk with Implementation in R and Matlab (The Wiley Finance Series)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 39 days · 39 data points (no recent data)

Historical
Generating forecast…
£49.40 £46.93 £47.92 £48.91 £49.89 £50.88 £51.87 25 July 2026 03 August 2026 13 August 2026 22 August 2026 01 September 2026
View at Amazon ↗

Price data last checked 52 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 39 days • 1 price levels

Days at Price
39 days 0 10 20 29 39 £49 Days at Price

Price Analysis

Most common price: £49 (39 days, 100.0%)

Price range: £49 - £49

Price levels: 1 different prices over 39 days

Description

Financial Risk Forecasting is a complete introduction to practical quantitative risk management, with a focus on market risk. Derived from the authors teaching notes and years spent training practitioners in risk management techniques, it brings together the three key disciplines of finance, statistics and modeling (programming), to provide a thorough grounding in risk management techniques. Written by renowned risk expert Jon Danielsson, the book begins with an introduction to financial markets and market prices, volatility clusters, fat tails and nonlinear dependence. It then goes on to present volatility forecasting with both univatiate and multivatiate methods, discussing the various methods used by industry, with a special focus on the GARCH family of models. The evaluation of the quality of forecasts is discussed in detail. Next, the main concepts in risk and models to forecast risk are discussed, especially volatility, value-at-risk and expected shortfall. The focus is both on risk in basic assets such as stocks and foreign exchange, but also calculations of risk in bonds and options, with analytical methods such as delta-normal VaR and duration-normal VaR and Monte Carlo simulation. The book then moves on to the evaluation of risk models with methods like backtesting, followed by a discussion on stress testing. The book concludes by focussing on the forecasting of risk in very large and uncommon events with extreme value theory and considering the underlying assumptions behind almost every risk model in practical use – that risk is exogenous – and what happens when those assumptions are violated. Every method presented brings together theoretical discussion and derivation of key equations and a discussion of issues in practical implementation. Each method is implemented in both MATLAB and R, two of the most commonly used mathematical programming languages for risk forecasting with which the reader can implement the models illustrated in the book. The book includes four appendices. The first introduces basic concepts in statistics and financial time series referred to throughout the book. The second and third introduce R and MATLAB, providing a discussion of the basic implementation of the software packages. And the final looks at the concept of maximum likelihood, especially issues in implementation and testing. The book is accompanied by a website - www.financialriskforecasting.com – which features downloadable code as used in the book.

Key Features

New

Mint Condition

Dispatch same day for order received before 12 noon

Guaranteed packaging

No quibbles returns

Product Specifications

Brand
Wiley
Format
hardcover
Domain
Amazon UK
Release Date
25 March 2011
Listed Since
10 February 2010

Barcode

No barcode data available

Similar Products You Might Like
The VaR Modeling Handbook: Practical Applications in Alternative Investing, Banking, Insurance, and Portfolio Management (PROFESSIONAL FINANCE & INVESTM)
97% match

The VaR Modeling Handbook: Practical Applications in Alternative Investing, Banking, Insurance, and Portfolio Management (PROFESSIONAL FINANCE & INVESTM)

McGraw-Hill Education
£98.99 03 Oct 2026
Wiley Financial Modelling Theory and MATLAB Implementation
97% match

Wiley Financial Modelling Theory and MATLAB Implementation

Wiley
£72.29 19 Aug 2026
Wiley Value at Risk Models - Market Risk Analysis Book
97% match

Wiley Value at Risk Models - Market Risk Analysis Book

Wiley
£66.79 11 Aug 2026
Introduction to Credit Risk Modeling - CRC Press Finance
97% match

Introduction to Credit Risk Modeling - CRC Press Finance

CRC Press
£156.26 22 Oct 2026
Measuring Market Risk (The Wiley Finance Series)
97% match

Measuring Market Risk (The Wiley Finance Series)

Wiley
£65.34 17 Sep 2026
Risk and Asset Allocation - Springer Finance Guide
97% match

Risk and Asset Allocation - Springer Finance Guide

Springer
£55.84 22 Oct 2026
Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)
97% match

Machine Learning for Factor Investing: R Version (Chapman and Hall/CRC Financial Mathematics Series)

CRC Press
£74.45 25 Sep 2026
A Course on Statistics for Finance
97% match

A Course on Statistics for Finance

CRC Press
£119.35 02 Oct 2026
Research in Finance: 24
97% match

Research in Finance: 24

Jai Press Inc.
£61.20 23 Sep 2026
Handbook Of Heavy-Tailed Distributions In Asset Management And Risk Management: 7 (World Scientific Handbook in Financial Economics Series)
97% match

Handbook Of Heavy-Tailed Distributions In Asset Management And Risk Management: 7 (World Scientific Handbook in Financial Economics Series)

Scientific Publishing
£165.00 12 Aug 2026
Numerical Methods for Finance - Chapman & Hall/CRC
97% match

Numerical Methods for Finance - Chapman & Hall/CRC

CRC Press
£190.00 13 Oct 2026
Machine Learning for Financial Risk Management with Python: Algorithms for Modeling Risk
97% match

Machine Learning for Financial Risk Management with Python: Algorithms for Modeling Risk

O'Reilly
£47.24 26 Aug 2026
Springer Extreme Financial Risks - Risk Management Book
97% match

Springer Extreme Financial Risks - Risk Management Book

Springer
£55.38 19 Aug 2026
Statistische Verfahren für Diffusionsprozesse mit Anwendung auf stochastische Zinsmodelle der Finanzmathematik
97% match

Statistische Verfahren für Diffusionsprozesse mit Anwendung auf stochastische Zinsmodelle der Finanzmathematik

GRIN Verlag
£58.50 12 Sep 2026
Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R
97% match

Applied Probabilistic Calculus for Financial Engineering: An Introduction Using R

Wiley
£101.39 20 Oct 2026
Quantitative Finance: A Simulation-Based Introduction Using Excel
97% match

Quantitative Finance: A Simulation-Based Introduction Using Excel

CRC Press
£68.99 16 Sep 2026
Numerical Methods for Finance (Chapman & Hall/CRC Financial Mathematics)
97% match

Numerical Methods for Finance (Chapman & Hall/CRC Financial Mathematics)

CRC Press
£66.87 01 Oct 2026
Financial Signal Processing and Machine Learning (IEEE Press)
97% match

Financial Signal Processing and Machine Learning (IEEE Press)

Wiley
£81.49 19 Aug 2026
Handbook of Market Risk (Wiley Handbooks in Financial Engineering and Econometrics)
97% match

Handbook of Market Risk (Wiley Handbooks in Financial Engineering and Econometrics)

Wiley
£115.69 13 Aug 2026
Financial Economics, Risk And Information (2nd Edition)
97% match

Financial Economics, Risk And Information (2nd Edition)

World Scientific Publishing Company
£60.38 22 Sep 2026
Wiley Risk Management in Trading - Hedge Fund Guide
97% match

Wiley Risk Management in Trading - Hedge Fund Guide

Wiley
£52.88 10 Sep 2026
Princeton University Press Portfolio Risk Analysis Book
97% match

Princeton University Press Portfolio Risk Analysis Book

Princeton University Press
£100.61 01 Oct 2026
Model Risk Management: Risk Bounds under Uncertainty
97% match

Model Risk Management: Risk Bounds under Uncertainty

Cambridge University Press
£89.91 18 Aug 2026
Springer Machine Learning in Finance: Theory to Practice Book
97% match

Springer Machine Learning in Finance: Theory to Practice Book

Springer

£51.19 11 Aug 2026