£58.99

It has never been this cheap. We have no record of a lower price.

£59 today · cheaper than every other day in the last 3 months

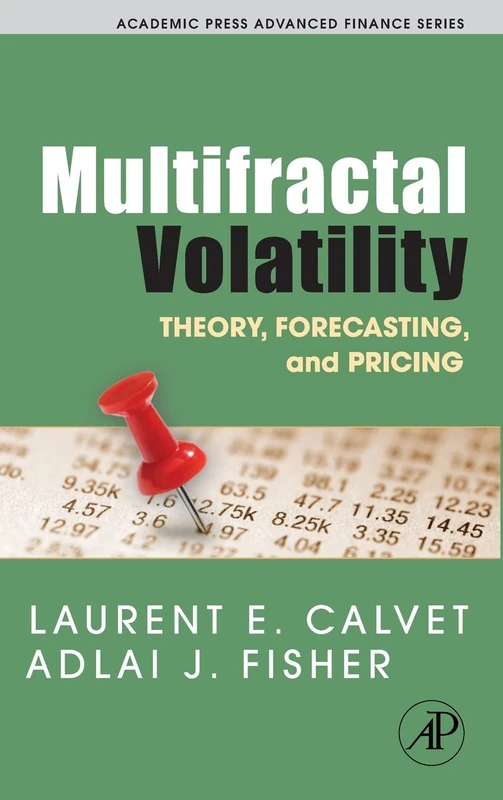
Elsevier Multifractal Volatility: Theory, Forecasting, and Pricing (Academic Press Advanced Finance Series)

View at Amazon

Price History & Forecast

Grey patches = out of stock. Cheaper = lower on the chart. Hover for exact prices.

Last 40 days · 40 data points (no recent data)

Historical
Generating forecast…
£58.99 £56.04 £57.22 £58.40 £59.58 £60.76 £61.94 25 July 2026 03 August 2026 13 August 2026 23 August 2026 02 September 2026
View at Amazon ↗

Price data last checked 51 day(s) ago - refreshing...

NEW HERE?

Amazon shows you one price. We show you all of them.

Tosheroon watches Amazon prices so you don't have to. Every product on Amazon has a price history — we make it visible. Set the price you'd actually pay, and we'll email you the second it gets there. No app, no account, one email.

WHAT'S ON THIS PAGE

↑ Price chart
when this has been cheap or pricey
↑ Forecast
where the price is heading next
↓ Statistics
all-time high & low, recent range
↑ Price alert
name your number, we'll email you

Price Distribution

Price distribution over 40 days • 1 price levels

Days at Price
40 days 0 10 20 30 40 £59 Days at Price

Price Analysis

Most common price: £59 (40 days, 100.0%)

Price range: £59 - £59

Price levels: 1 different prices over 40 days

Description

Calvet and Fisher present a powerful, new technique for volatility forecasting that draws on insights from the use of multifractals in the natural sciences and mathematics and provides a unified treatment of the use of multifractal techniques in finance. A large existing literature (e.g., Engle, 1982; Rossi, 1995) models volatility as an average of past shocks, possibly with a noise component. This approach often has difficulty capturing sharp discontinuities and large changes in financial volatility. Their research has shown the advantages of modelling volatility as subject to abrupt regime changes of heterogeneous durations. Using the intuition that some economic phenomena are long-lasting while others are more transient, they permit regimes to have varying degrees of persistence. By drawing on insights from the use of multifractals in the natural sciences and mathematics, they show how to construct high-dimensional regime-switching models that are easy to estimate, and substantially outperform some of the best traditional forecasting models such as GARCH. The goal of Multifractal Volatility is to popularize the approach by presenting these exciting new developments to a wider audience. They emphasize both theoretical and empirical applications, beginning with a style that is easily accessible and intuitive in early chapters, and extending to the most rigorous continuous-time and equilibrium pricing formulations in final chapters. Presents a powerful new technique for forecasting volatility Leads the reader intuitively from existing volatility techniques to the frontier of research in this field by top scholars at major universities The first comprehensive book on multifractal techniques in finance, a cutting-edge field of research

Product Specifications

Format
hardcover
Domain
Amazon UK
Release Date
12 September 2008
Listed Since
18 December 2006

Barcode

No barcode data available

Similar Products You Might Like
Forecasting Volatility in the Financial Markets (Quantitative Finance)
97% match

Forecasting Volatility in the Financial Markets (Quantitative Finance)

Elsevier
£71.00 06 Oct 2026
Stochastic Volatility and Realized Stochastic Volatility Models (SpringerBriefs in Statistics)
97% match

Stochastic Volatility and Realized Stochastic Volatility Models (SpringerBriefs in Statistics)

Springer
£40.73 22 Sep 2026
Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)
97% match

Continuous Time Processes for Finance: Switching, Self-exciting, Fractional and other Recent Dynamics: 12 (Bocconi & Springer Series, 12)

Springer
£94.74 24 Sep 2026
Forecasting Volatility in the Financial Markets
97% match

Forecasting Volatility in the Financial Markets

Butterworth-Heinemann
£71.00 18 Sep 2026
Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)
97% match

Derivatives and Internal Models: Modern Risk Management (Finance and Capital Markets Series)

MACMILLAN
£61.09 29 Aug 2026
Chapman and Hall/CRC Malliavin Calculus in Finance Textbook
97% match

Chapman and Hall/CRC Malliavin Calculus in Finance Textbook

Chapman and Hall/CRC
£104.00 15 Aug 2026
Market Risk Analysis, Practical Financial Econometrics (The Wiley Finance Series)
97% match

Market Risk Analysis, Practical Financial Econometrics (The Wiley Finance Series)

Wiley
£53.68 21 Oct 2026
Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models
97% match

Market Risk Analysis: Quantitative Methods in Finance, Practical Financial Econometrics, Pricing, Hedging and Trading Financial Instruments, Value-at-Risk Models

Wiley
£160.65 15 Aug 2026
The Econometrics of Financial Markets
97% match

The Econometrics of Financial Markets

Princeton University Press
£49.30 14 Aug 2026
Handbook of Volatility Models and Their Applications: 03 (Wiley Handbooks in Financial Engineering and Econometrics)
97% match

Handbook of Volatility Models and Their Applications: 03 (Wiley Handbooks in Financial Engineering and Econometrics)

Wiley
£123.96 15 Aug 2026
Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)
97% match

Listed Volatility and Variance Derivatives: A Python-based Guide (Wiley Finance)

Wiley
£60.99 17 Sep 2026
Statistical Methods for Financial Engineering
97% match

Statistical Methods for Financial Engineering

Chapman and Hall/CRC
£48.99 11 Sep 2026
Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)
97% match

Market Expectations and Option Prices: Techniques and Applications (Contributions to Economics)

Springer
£82.06 24 Sep 2026
The Volatility Surface: A Practitioner's Guide (Wiley Finance)
97% match

The Volatility Surface: A Practitioner's Guide (Wiley Finance)

Wiley
£33.68 05 Oct 2026
Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models
97% match

Volatility Markets: Consistent Modeling, Hedging, and Practical Implementation of Variance Swap Market Models

VDM Verlag
£61.00 11 Sep 2026
Springer Martingale Methods in Financial Modelling - 2nd Ed
97% match

Springer Martingale Methods in Financial Modelling - 2nd Ed

Springer
£96.99 21 Aug 2026
Springer Stochastic Models for Energy and Commodity Markets
97% match

Springer Stochastic Models for Energy and Commodity Markets

Springer
£90.63 21 Aug 2026
Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives
97% match

Multiscale Stochastic Volatility for Equity, Interest Rate, and Credit Derivatives

Cambridge University Press
£49.79 07 Oct 2026
Stochastic Finance with Python: Design Financial Models from Probabilistic Perspective
97% match

Stochastic Finance with Python: Design Financial Models from Probabilistic Perspective

Apress
£39.55 12 Aug 2026
Option Pricing Models and Volatility Using Excel-VBA
97% match

Option Pricing Models and Volatility Using Excel-VBA

Wiley
£49.01 03 Sep 2026
Chapman and Hall/CRC Financial Modelling with Jump Processes
97% match

Chapman and Hall/CRC Financial Modelling with Jump Processes

Chapman and Hall/CRC
£95.22 15 Aug 2026
Wiley Handbook of Modeling High-Frequency Data in Finance
97% match

Wiley Handbook of Modeling High-Frequency Data in Finance

Wiley
£121.00 03 Oct 2026
MIT Press - The Economics of Continuous-Time Finance Book
97% match

MIT Press - The Economics of Continuous-Time Finance Book

MIT Press
£44.21 22 Oct 2026
Semiparametric Modeling of Implied Volatility (Springer Finance)
97% match

Semiparametric Modeling of Implied Volatility (Springer Finance)

Springer

£59.93 17 Oct 2026